
Conditional Approval of Jibal Qutman Development
Summary by AI BETAClose X

Market Abuse Regulation (MAR) Disclosure: certain information contained in this announcement would have been deemed inside information for the purposes of Article 7 of Regulation (EU) No 596/2014 as it forms part of UK law by virtue of the European Union (Withdrawal) Act 2018, until the release of this announcement.
27 October 2026
KEFI Gold and Copper plc
("KEFI" or the "Company")
Conditional Approval of Development at Jibal Qutman
KEFI (AIM: KEFI), focussed on the Arabian-Nubian Shield, with projects in the Federal Democratic Republic of Ethiopia and the Kingdom of Saudi Arabia, announces that Gold and Minerals Company Limited ("GMCO"), its Saudi Arabian joint venture company, has approved the development of Stage 1 of the Jibal Qutman Gold Project ("JQ1"), subject to the completion of certain outstanding procedural requirements.
GMCO, in which KEFI holds a 13% interest and its long-standing Saudi Arabian partner, industrial conglomerate ARTAR holds the remaining 87%, has approved the approximately US$87 million capital development programme for JQ1, with development expected to commence during Q4 2026. The principal outstanding requirements to start development is the granting of a Mining Licence by the newly appointed Saudi Arabian Minister of Industry and Mineral Resources.
JQ1 is GMCO’s first development within its substantial Saudi Arabian portfolio, which contains aggregate Mineral Resources of approximately 4.0 million ounces of gold equivalent. The portfolio comprises the Jibal Qutman Gold Project and the Hawiah Copper-Gold Project, both of which are expected to be developed in stages.
Highlights
- Development approval: GMCO's Board has approved the c. US$87 million JQ1 development, subject to completion of the remaining procedural requirements, with commencement targeted for Q4 2026.
- Production: JQ1 is an oxide-ore gold development utilising conventional carbon-in-leach processing, with an estimated seven-year operating period and recovery of approximately 258,000 ounces of gold.
- Attractive project economics: At gold prices of US$3,000–5,000 per ounce, JQ1 is estimated to generate a post-tax net present value ("NPV") at a 5% discount rate of US$141–275 million and an internal rate of return ("IRR") of 23–60%.
- Financing: KEFI’s 13% contribution is c.US$10-12 million over 24 months, if all contributed as equity. Based on current discussions, it is expected that approximately 50% of the total capital requirements will be provided on commencement of development with the balance of US$5-6 million to be optimised as to quantum and sourcing after 12 months, having considered the financing alternatives.
- Operating and Financial Platform for Growth: JQ1 is intended to establish the operating and financial platform for subsequent developments at Jibal Qutman and Hawiah, with cash flows from the initial operation expected to underpin future exploration and sequential project developments.
- Significant Saudi Arabian portfolio: GMCO's aggregate Mineral Resources of approximately 4.0 million ounces of gold equivalent provide the foundation for the series of planned developments, with a longer-term aggregate production target in the order of 350,000 of gold and gold equivalent ounces per annum.
- KEFI's participation: KEFI retains the flexibility to participate in future equity funding requirements or accept proportionate dilution of its GMCO shareholding.
- GMCO has a stand-alone management and operating structure, with shareholder oversight.
Harry Anagnostaras-Adams, Executive Chairman of KEFI Gold and Copper, commented: “The conditional approval of the development of Jibal Qutman Stage 1 is an important milestone for GMCO and for KEFI's interests in Saudi Arabia. With the remaining procedural requirements expected to be completed shortly, we look forward to the commencement of development during the fourth quarter of this year.
"Jibal Qutman Stage 1 is an attractive project in its own right, and its wider significance lies in establishing the first producing operation within GMCO's substantial portfolio of gold and copper assets. We anticipate that the cash flows generated by this initial development will provide an important foundation for funding GMCO’s exploration activities and the progressive development of identified further projects at Jibal Qutman and Hawiah.
"For KEFI, our interest in GMCO provides exposure to a significant and growing Saudi Arabian mining business, alongside our principal development activities in Ethiopia. The joint venture's stand-alone management structure and our flexibility regarding future funding commitments allow us to participate in this opportunity while maintaining our focus on starting up Tulu Kapi, where we are recommencing a re-set development program following the recent security incident, commencing with community priorities.
“KEFI’s Ethiopian and Saudi development pipeline presents us with a pathway to a beneficial interest in a combined 205,000 oz gold and gold equivalent production."
Jibal Qutman Stage 1 Development
JQ1 comprises the initial development of the oxide gold resources at Jibal Qutman and is designed as a conventional carbon-in-leach gold operation. Based on the Definitive Feasibility Study, the project has an estimated capital development cost of approximately US$87 million and is expected to recover approximately 258,000 ounces of gold over an initial seven-year operating period.
The estimated economics of JQ1, based on two illustrative gold price scenarios, are summarised below:
|
|
US$3,000/oz gold |
US$5,000/oz gold |
|
Capital expenditure (US$m) |
87 |
87 |
|
Initial equity funding (US$m) |
44 |
44 |
|
Average gold grade (g/t) |
0.5 |
0.5 |
|
Gold recovery (%) |
87 |
87 |
|
Seven-year operating period |
|
|
|
Gold production (000 oz) |
258 |
258 |
|
Revenue (US$m) |
800 |
1,317 |
|
Operating costs (US$m) |
623 |
777 |
|
EBIT (US$m) |
177 |
540 |
|
Tax (US$m) |
38 |
126 |
|
Profit after tax (US$m) |
139 |
414 |
|
Net cash generated (US$m) |
264 |
627 |
|
Payback (years) |
1.9 |
0.9 |
|
Breakeven gold price (US$/oz) |
1,871 |
1,871 |
|
IRR (%) |
23 |
60 |
|
NPV at 5% discount rate (US$m) |
141 |
275 |
These estimates demonstrate the potential for JQ1 to generate attractive returns as a standalone operation, while establishing the infrastructure and operating capability to support GMCO's broader development strategy.
Development Financing
The proposed financing structure for JQ1 envisages at least half of the initial development capital being provided through equity contributions from GMCO's shareholders, with the balance to be provided through other financing arrangements. On this basis, the anticipated initial equity contributions would be c. US$38 million from ARTAR, reflecting its 87% interest, and c. US$6 million from KEFI, reflecting its 13% interest.
The financing mix for subsequent rounds of capital injection will be determined in due course. GMCO's objective is for cash flows generated by JQ1 to fund its ongoing exploration activities and, together with appropriate project financing, progressively support the development of subsequent projects.
Wider Saudi Arabian Development Portfolio
JQ1 is the first stage of a planned series of mine developments across GMCO's Jibal Qutman and Hawiah projects.
The next anticipated development is Stage 2 of Jibal Qutman, targeting the project's sulphide gold resources. This is expected to be followed by the initial development of oxide resources at the Hawiah Copper-Gold Project and subsequently by underground mining Hawiah's sulphide resources.
GMCO's aggregate Mineral Resources currently total approximately 4.0 million ounces of gold equivalent, approximately twice the scale of the Mineral Resources at KEFI's Tulu Kapi Gold Project in Ethiopia.
The longer-term development strategy envisages aggregate production from the Saudi Arabian portfolio in the order of 350,000 of gold and gold equivalent ounces per annum. At KEFI's current 13% interest, this would represent attributable production of approximately 45,000 of gold and gold equivalent ounces per annum, equivalent to approximately 28% of KEFI's anticipated attributable production from Tulu Kapi.
The development of the Saudi Arabian portfolio therefore represents a significant opportunity for KEFI to diversify its future production and earnings across multiple projects and jurisdictions.
Importantly, GMCO operates through its own management structure, with responsibility for the development and operation of its projects resting with the joint venture rather than KEFI.
Longer-Term Value Potential
The estimated after tax NPV of JQ1, using a 5% discount rate and assumed gold prices of US$3,000–5,000 per ounce, is US$141–275 million.
Beyond JQ1, GMCO's wider development portfolio includes substantial additional mineral resources, with the subsequent projects expected to offer higher grades and potentially stronger economic returns.
As an illustration of the potential scale of the portfolio, the JQ1 NPV of US$141-275 million for a gold price range of US$3,000-5,000/oz, is based on the recovery of 258,000 oz gold of GMCO’s total 4.0 million ounces gold-equivalent resources in which KEFI holds a 13% beneficial interest.
Mineral Resource Estimate (“MRE”)
As announced on 18 February 2025, the 2025 Hawiah MRE is classified as:
- Indicated - Open Pit - 12.7Mt at 0.85% copper, 0.83% zinc, 0.81g/t gold and 10.8g/t silver
- Indicated - Underground - 17.8Mt at 0.85% copper, 0.91% zinc, 0.56g/t gold and 9.9g/t silver
- Inferred - Open Pit - 0.01Mt at 1.18% copper, 1.14% zinc, 0.65g/t gold and 9.6g/t silver
- Inferred - Underground – 5.7 Mt at 0.69% copper, 0.74% zinc, 0.51g/t gold and 8.4g/t silver
Based on the 2025 MRE, the Hawiah deposit is estimated to contain a total of 297,000 tonnes of copper, 310,000 tonnes of zinc, 745,000 gold ounces and 11.6 million silver ounces.
As announced on 26 February 2025, the 2025 Jibal Qutman MRE is classified as follows:
MRE of 37.0Mt at 0.76g/t gold, containing 902,000 ounces of gold.
This included 30.5Mt at 0.76g/t gold, containing 748,000 ounces in the Indicated category, representing approximately 83% of the total resource. Oxide Resources totals 13.2Mt at 0.75g/t gold, containing 318,000 ounces, providing a strong foundation for near-surface, open-pit development.
Gold Equivalency Calculations
Gold equivalency has been calculated as per the metal values and recoveries used in the most recent Mineral Resource Estimates for the JORC compliant GMCO resources.
The total equivalency includes the Hawiah and Al Godeyer polymetallic VMS deposits and the Jabal Qutman gold project. The factors and equation used in the calculation are provided below. Note that gold equivalency is provided for illustration to allow for comparison between deposits where varying commodities are present and should not be treated as actual. The full MRE statements and JORC Table 1. for the three deposits have been previously announced. An abridged version of these statements is also provided in the appendix below.
As each deposit domain has variable metal recoveries, each has been calculated separately and combined to provide an overall gold equivalent (“AuEq”) total.
Table 1 - Metal values and recoveries used in AuEq calculation
|
Metal |
Market price |
Unit |
Recovery (%) |
|
Gold (Au) |
US$2,300 |
oz (troy) |
74.0 |
|
Silver (Ag) |
US$30 |
oz (troy) |
83.0 |
|
Copper (Cu) |
US$9,350 |
Tonne (t) |
90.0 |
|
Zinc (Zn) |
US$3,300 |
Tonne (t) |
90.0 |
|
Silver (Ag) VMS Oxide |
US$30 |
oz (troy) |
15.0 |
|
Gold (Au) VMS Oxide |
US$2,300 |
oz (troy) |
84.0 |
The following equation was used to calculate the equivalency. Note that percentages and grams were normalised as part of the process:
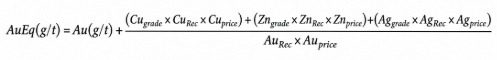
Table 2 – Gold equivalency by deposit
|
Deposit |
Gold Equivalent (million oz) |
AuEq grade |
|
Hawiah |
2.9 |
2.51 |
|
Al Godeyer |
0.2 |
3.04 |
|
Jibal Qutman |
0.9 |
0.76 |
|
Total |
4.0 |
|
Management and Governance
GMCO operates with an independent management structure responsible for progressing its Saudi Arabian exploration and development portfolio.
KEFI maintains representation and oversight through its Executive Chairman, Harry Anagnostaras-Adams, who serves as a director of GMCO, and through representation on GMCO's Operations Steering Committee. This structure enables KEFI to participate in the development and potential value creation of GMCO's substantial Saudi Arabian assets without assuming the primary project sponsorship and operating responsibilities associated with its Tulu Kapi Gold Project in Ethiopia.
Enquiries
|
KEFI Gold and Copper plc |
|
|
Harry Anagnostaras-Adams (Executive Chairman) |
+357 2225 6161 |
|
John Leach (Finance Director) |
|
|
SP Angel Corporate Finance LLP (Nominated Adviser) |
+44 (0) 20 3470 0470 |
|
Caroline Rowe / Adam Cowl |
|
|
Stifel Nicolaus Europe Limited (Financial Adviser and Joint Broker) Ashton Clanfield / Varun Talwar |
+44 (0) 20 7710 7600 |
|
Tavira Financial Limited (Joint Broker) |
+44 (0) 20 7100 5100 |
|
Oliver Stansfield / Jonathan Evans |
|
|
IFC Advisory Ltd (Financial PR and IR) |
+44 (0) 20 3934 6632 |
|
Tim Metcalfe / Florence Staton |
|
Further information can be viewed at https://www.kefi-goldandcopper.com
Appendix
Hawiah MRE
As announced on 18 February 2025, GMCO appointed The MSA Group (Pty) Ltd (“MSA”) as the Independent Consultants and Competent Person to prepare an updated MREs for Hawiah and Al Godeyer in accordance with the Australasian Code for the Reporting of Exploration Results, Mineral Resources and Ore Reserves (“JORC Code 2012”). The Hawiah and Al Godeyer MREs were recently signed off by MSA and then reviewed by GMCO and KEFI.
The updated MRE for the Hawiah deposit is detailed in Table 1 below and totals:
- 36.2 Mt at 0.82% copper, 0.85% zinc, 0.64g/t gold and 10.0g/t silver.
Resources are classified as:
- Indicated - Open Pit – 12.7Mt at 0.85% copper, 0.83% zinc, 0.81g/t gold and 10.8g/t silver
- Indicated - Underground – 17.8Mt at 0.85% copper, 0.91% zinc, 0.56g/t gold and 9.9g/t silver
- Inferred - Open Pit – 0.01Mt at 1.18% copper, 1.14% zinc, 0.65g/t gold and 9.6g/t silver
- Inferred - Underground – 5.7 Mt at 0.69% copper, 0.74% zinc, 0.51g/t gold and 8.4g/t silver
Based on this MRE, the Hawiah deposit is estimated to contain a total of 297,000 tonnes of copper, 310,000 tonnes of zinc, 745,000 gold ounces and 11.6 million silver ounces.
Table 1 - Hawiah Mineral Resource as at 9 January 2025
|
Class |
Mining |
Material |
Tonnes |
Grade |
Metal Content |
||||||
|
Cu |
Zn |
Au |
Ag |
Cu |
Zn |
Au |
Ag |
||||
|
Indicated |
Open Pit |
Oxide |
1.2 |
- |
- |
2.11 |
8.0 |
0 |
0 |
83 |
313 |
|
Transition |
2.9 |
1.22 |
0.72 |
0.72 |
13.0 |
36 |
21 |
68 |
1217 |
||
|
Fresh |
8.5 |
0.84 |
0.99 |
0.65 |
10.4 |
72 |
84 |
179 |
2862 |
||
|
Underground |
Oxide |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
|
|
Transition |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
||
|
Fresh |
17.8 |
0.85 |
0.91 |
0.56 |
9.9 |
151 |
162 |
322 |
5651 |
||
|
Inferred |
Open Pit |
Oxide |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
|
Transition |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
||
|
Fresh |
0.01 |
1.18 |
1.14 |
0.65 |
9.6 |
0.1 |
0.1 |
0.2 |
3.4 |
||
|
Underground |
Oxide |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
|
|
Transition |
0.0 |
- |
- |
- |
- |
0 |
0 |
0 |
0 |
||
|
Fresh |
5.7 |
0.69 |
0.74 |
0.51 |
8.4 |
39 |
42 |
93 |
1543 |
||
|
Total Indicated |
Open Pit |
12.7 |
0.85 |
0.83 |
0.81 |
10.8 |
107 |
105 |
330 |
4392 |
|
|
Underground |
17.8 |
0.85 |
0.91 |
0.56 |
9.9 |
151 |
162 |
322 |
5651 |
||
|
All |
30.5 |
0.85 |
0.88 |
0.67 |
10.3 |
258 |
267 |
652 |
10043 |
||
|
Total Inferred |
Open Pit |
0.01 |
1.18 |
1.14 |
0.65 |
9.6 |
0.1 |
0.1 |
0.2 |
3.4 |
|
|
Underground |
5.7 |
0.69 |
0.74 |
0.51 |
8.4 |
39 |
42 |
93 |
1543 |
||
|
All |
5.7 |
0.69 |
0.74 |
0.51 |
8.4 |
39 |
42 |
93 |
1546 |
||
|
Total Mineral Resource |
Open Pit |
12.7 |
0.85 |
0.83 |
0.81 |
10.8 |
107 |
105 |
330 |
4395 |
|
|
Underground |
23.5 |
0.81 |
0.87 |
0.55 |
9.5 |
190 |
204 |
415 |
7194 |
||
|
All |
36.2 |
0.82 |
0.86 |
0.64 |
10.0 |
297 |
310 |
745 |
11589 |
||
Notes:
- koz = one thousand ounces, kt = one thousand metric tonnes, Mt = one million metric tonnes.
- All tabulated data have been rounded and as a result minor computational errors may occur.
- Mineral Resources, which are not Mineral Reserves, have no demonstrated economic viability.
- The Gross Mineral Resource for the Project is reported.
- The Mineral Resource is reported in accordance with the guidelines of the 2012 Edition of The Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves ('the JORC Code').
- A Whittle optimised pit shell was used to report open-pit Mineral Resources and a mineable shape optimisation (MSO) was completed for underground Mineral Resources outside the open-pit shell. The Whittle, MSO and cut-off grades were derived using the following assumed technical parameters:
No Oxide and Transition mined underground.
Pit slope angle: Fresh 53°, Transition and Oxide: 42°.
Dilution included in regularised block model (5 mX by 5 mY by 2.5 mZ) for open pit.
A minimum stope width of 2 m, and 0.2m dilution applied for underground.
Concentrator Recovery: Cu & Zn 90% in transitional and fresh; Au 84% in oxide and 74% in fresh; Ag 15% in oxide and 83% in transitional and fresh. No recovery of zinc and copper in oxide. Metallurgical factors based on initial metallurgical test-work.
Cost and revenue assumptions:
Metal Price: Cu 9350 USD/t, Zn 3300 USD/t, Au 2300 USD/oz, Ag 30 USD/oz.
Smelter recovery/payability: Cu concentrate - Cu 96.5%, Au 90%, Ag 90%. Zn concentrate - Zn 83.5%. Au Dore - Au 99.5%, Ag 99.6%.
Total mining cost: open pit oxide 2.2 USD/t, open pit transition and fresh 2.4 USD/t, underground 30.0 USD/t. Cost adjustment for open-pit depth USD 0.004/ vertical m.
Total Processing cost: oxide 13.86 USD/t, transition and fresh 21.4 USD/t.
Rehandling: 0.70 USD/t
G&A: 5.6 USD/t ore.
- The cut-off grade was applied on a NSR basis: underground fresh ore 57.7 USD/t, open-pit transitional and fresh ore 27.7 USD/t, open-pit oxide ore 20.16 USD/t. NSR was calculated for each block model cell using the following formulae:
Oxide = (Cu %*0)+(Zn%*0)+(Au g/t 61.7895 )+(Ag g/t*0.1409)
Transition and Fresh = (Cu %*76.5870)+(Zn%*20.1118)+(Au g/t *54.4336)+(Ag g/t*0.7797).
Hawiah MRE Comparison
The previous (12 December 2022) Hawiah MRE totalled 29.0 Mt at 0.89% copper, 0.94% zinc, 0.67 g/t gold and 10.1 g/t silver.
The updated Hawiah MRE represents a significant increase in tonnage from 29.0Mt to 36.2Mt and small decreases in grades to 0.82% copper to 0.89%, 0.85% zinc, 0.64g/t gold and 10.0 g/t silver. The additional resource tonnage is largely driven by the expansion of Crossroads Extension Lode at depth.
Hawiah Open Pit Indicated Resources have increased by 3.5Mt to 12.7Mt. This continues to demonstrate a robust case for a lower cost open-pit development during the early years of the Project, further strengthening the economic case.
Updated Al Godeyer MRE
The updated MRE for the Al Godeyer deposit is detailed in Table 2 below and totals:
- 2.0 Mt at 0.93% copper, 0.53% zinc, 1.21g/t gold and 7.4g/t silver.
And 94% of the MRE is now in the Indicated Resource category (previously all in the Inferred Resource category).
Based on this MRE, the Al Godeyer deposit is estimated to contain a total of 18,500 tonnes of copper, 10,600 tonnes of zinc, 77,900 gold ounces and 0.5 million silver ounces.
Table 2 – Al Godeyer Mineral Resource as at 9 December 2024
|
Class |
Mining Type |
Material Type |
Tonnes (Mt) |
Grade |
Metal Content |
||||||
|
Cu |
Zn |
Au |
Ag |
Cu |
Zn |
Au |
Ag |
||||
|
Indicated |
Open Pit |
Oxide |
0.28 |
- |
- |
1.48 |
1.38 |
0.0 |
0.0 |
13.4 |
12.9 |
|
Transition |
0.22 |
0.70 |
0.22 |
0.91 |
6.88 |
1.6 |
0.5 |
6.5 |
49.3 |
||
|
Fresh |
1.38 |
1.12 |
0.65 |
1.19 |
8.28 |
15.4 |
8.9 |
52.7 |
366.4 |
||
|
Total Indicated |
|
All |
1.88 |
0.90 |
0.50 |
1.20 |
7.08 |
17.0 |
9.4 |
72.6 |
428.2 |
|
Inferred |
Open Pit |
Oxide |
0.00 |
- |
- |
- |
- |
0.0 |
0.0 |
0.0 |
0.0 |
|
Transition |
0.00 |
- |
- |
- |
- |
0.0 |
0.0 |
0.0 |
0.0 |
||
|
Fresh |
0.12 |
1.36 |
1.10 |
1.42 |
12.17 |
1.6 |
1.3 |
5.3 |
45.3 |
||
|
Total Inferred |
|
All |
0.12 |
1.36 |
1.10 |
1.42 |
12.17 |
1.6 |
1.3 |
5.3 |
45.3 |
|
Total Resource |
|
All |
2.00 |
0.93 |
0.53 |
1.21 |
7.37 |
18.5 |
10.6 |
77.9 |
473.8 |
Notes:
- koz = one thousand ounces, kt = one thousand metric tonnes, Mt = one million metric tonnes.
- All tabulated data have been rounded and as a result minor computational errors may occur.
- Mineral Resources, which are not Mineral Reserves, have no demonstrated economic viability.
- The Gross Mineral Resource for the Project is reported.
- The Mineral Resource is reported in accordance with the guidelines of the 2012 Edition of The Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves” (‘the JORC Code’).
- A Whittle optimised pit shell was used to report open-pit Mineral Resources. The Whittle optimisation was based on the following assumed technical parameters:
Pit slope angle: Fresh 56°, Transition 51° and Oxide: 44°.
Dilution of 10% and mining recovery of 95%
Concentrator Recovery: Cu 90%, Zn 90%, Au 85%, Ag 60% No recovery of zinc and copper in oxide. Metallurgical factors based on initial metallurgical test-work.
Cost and revenue assumptions:
Metal Price: Cu 9,350 USD/t, Zn 3,300 USD/t, Au 2,300 USD/oz, Ag 30 USD/oz.
Smelter recovery/payability: Cu 96.5%, Zn 83.5%. Au Dore - Au 99.5%, Ag 99.6%.
Mining cost: open pit oxide 2.2 USD/t, open pit transition and fresh 2.4 USD/t. Transport to Hawiah plant 1.125 USD/t and rehandling cost of 0.7 USD/t. Cost adjustment for open-pit depth USD 0.004 / vertical m.
Total Processing cost: oxide 13.9 USD/t, transition and fresh 21.4 USD/t.
G&A: 5.6 USD/t ore.
- The cut-off grade was applied on a net smelter return (NSR) basis: open-pit transition and fresh ore 31.2 USD/t, open-pit oxide ore 23.5 USD/t. NSR was calculated for each block model cell using the following formulae:
Oxide = (Cu %*0)+(Zn%*0)+(Au g/t*62.5251 )+(Ag g/t*0.5637)
Transition and Fresh = (Cu %*76.5870)+(Zn%*20.1118)+(Au g/t *62.5251)+(Ag g/t*0.5637).
Al Godeyer MRE Comparison
The previous (27 March 2023) Al Godeyer MRE totalled 1.35Mt at 0.6% copper, 0.54% zinc, 1.4g/t gold and 6.6g/t silver.
Infill drilling allowed better definition of the high-grade zone in the core of the deposit and high-grade copper intersections enhanced the fresh zone copper grade.
The updated Al Godeyer MRE represents a 0.65Mt increase in tonnage from 1.35Mt to 2.0Mt. The additional resource tonnage is largely driven by further drilling extending the resource. The average resource grades are similar except for the copper grade increasing 55% to 0.93g/t copper.
Competent Person Statement - Hawiah
The Hawiah and Al Godeyer Mineral Resource estimates were completed by Mr. Jeremy Charles Witley (BSc Hons, MSc (Eng.)) who is a geologist with 36 years’ experience in base and precious metals exploration and mining as well as Mineral Resource evaluation and reporting. He is a Principal Mineral Resource Consultant for The MSA Group (an independent consulting company). He is registered with the South African Council for Natural Scientific Professions (“SACNASP”), is a Fellow of the Geological Society of South Africa (“GSSA”) and a Fellow of the Professional Society of Independent Experts of the Subsurface Resources (“PONEN”), Kazakhstan. Mr. Witley has the appropriate relevant qualifications and experience to be considered a “Competent Person” as defined by JORC (2012) for the style and type of mineralisation and activity being undertaken.
The information in this announcement that relates to exploration results and geological interpretaion is based on information compiled by Mr Tomos Bryan for GMCO. Mr Bryan is a member of the AusIMM. Mr Bryan is a geologist with sufficient relevant experience for Company reporting to qualify as a Competent Person as defined in the JORC Code 2012. Mr Bryan consents to the inclusion in this announcement of the matters based on this information in the form and context in which it appears.
Jibal Qutman MRE
As announced on 26 February 2025, GMCO appointed The MSA Group (Pty) Ltd (“MSA”) as the Independent Consultants and Competent Person to prepare an updated MRE for Jibal Qutman in accordance with the Australasian Code for the Reporting of Exploration Results, Mineral Resources and Ore Reserves (“JORC Code 2012”). The MRE was signed off by MSA and then reviewed by GMCO and KEFI.
The Jibal Qutman MRE is detailed in Table 1 below and totals 37.0Mt at 0.76g/t gold, containing 902,000 ounces of gold.
Key points to note in the MRE:
- Indicated Resources total 30.5Mt containing 748,000 ounces (83% of total MRE)
- Oxide Resources total 13.2Mt at 0.75g/t gold, containing 318,000 ounces
- The three zones providing the most ounces are Main and West (292,000 ounces), South Combined (243,000 ounces) and Red Hill (183,000 ounces).
Table 1 - Jibal Qutman Mineral Resource as at 30 November 2024
|
Zone |
Oxide State |
Cut-off grade (g/t) |
Classification |
Tonnes |
Au Grade |
Au |
|
3K Hill |
Oxide |
0.24 |
Indicated |
1 614 |
1.03 |
53 |
|
Inferred |
144 |
0.62 |
3 |
|||
|
Subtotal |
1 758 |
0.99 |
56 |
|||
|
Sulphide |
0.29 |
Indicated |
1 160 |
1.18 |
44 |
|
|
Inferred |
715 |
0.87 |
20 |
|||
|
Subtotal |
1 875 |
1.06 |
64 |
|||
|
Oxide and Sulphide |
Total |
3 633 |
1.03 |
120 |
||
|
4K Hill |
Oxide |
0.22 |
Indicated |
1 379 |
0.53 |
24 |
|
Inferred |
362 |
0.41 |
5 |
|||
|
Subtotal |
1 741 |
0.51 |
28 |
|||
|
Sulphide |
0.29 |
Indicated |
1 698 |
0.53 |
29 |
|
|
Inferred |
329 |
0.45 |
5 |
|||
|
Subtotal |
2 027 |
0.52 |
34 |
|||
|
Oxide and Sulphide |
Total |
3 768 |
0.51 |
62 |
||
|
South Combined |
Oxide |
0.22 |
Indicated |
3 352 |
0.64 |
69 |
|
Inferred |
110 |
0.50 |
2 |
|||
|
Subtotal |
3 462 |
0.63 |
70 |
|||
|
Sulphide |
0.29 |
Indicated |
6 283 |
0.66 |
133 |
|
|
Inferred |
1 825 |
0.66 |
39 |
|||
|
Subtotal |
8 108 |
0.66 |
172 |
|||
|
Oxide and Sulphide |
Total |
11 570 |
0.65 |
243 |
||
|
Red Hill |
Oxide |
|
Indicated |
1 674 |
0.82 |
44 |
|
Inferred |
41 |
0.53 |
1 |
|||
|
Subtotal |
1 715 |
0.81 |
45 |
|||
|
Sulphide |
|
Indicated |
4 559 |
0.77 |
113 |
|
|
Inferred |
1 113 |
0.72 |
26 |
|||
|
Subtotal |
5 672 |
0.76 |
138 |
|||
|
Oxide and Sulphide |
Total |
7 387 |
0.77 |
183 |
||
|
Main & West |
Oxide |
|
Indicated |
4 263 |
0.82 |
112 |
|
Inferred |
206 |
0.62 |
4 |
|||
|
Subtotal |
4 469 |
0.81 |
116 |
|||
|
Sulphide |
|
Indicated |
4 505 |
0.88 |
128 |
|
|
Inferred |
1 506 |
1.00 |
48 |
|||
|
Subtotal |
6 011 |
0.91 |
176 |
|||
|
Oxide and Sulphide |
Total |
10 480 |
0.87 |
292 |
||
|
Pyrite Hill |
Oxide |
|
Indicated |
- |
0.00 |
0 |
|
Inferred |
108 |
0.56 |
2 |
|||
|
Subtotal |
108 |
0.56 |
2 |
|||
|
Sulphide |
|
Indicated |
- |
0.00 |
0 |
|
|
Inferred |
7 |
0.53 |
0 |
|||
|
Subtotal |
7 |
0.53 |
0 |
|||
|
Oxide and Sulphide |
Total |
115 |
0.56 |
2 |
||
|
Total |
Oxide |
Indicated |
12 282 |
0.76 |
301 |
|
|
Inferred |
971 |
0.52 |
16 |
|||
|
Subtotal |
13 253 |
0.75 |
318 |
|||
|
Sulphide |
Indicated |
18 205 |
0.76 |
446 |
||
|
Inferred |
5 494 |
0.78 |
138 |
|||
|
Subtotal |
23 700 |
0.77 |
585 |
|||
|
Oxide and Sulphide |
Indicated |
30 487 |
0.76 |
748 |
||
|
Inferred |
6 466 |
0.74 |
154 |
|||
|
Total |
36 953 |
0.76 |
902 |
|||
Notes:
- koz = one thousand ounces (31.10348 Troy ounce conversion to grams), kt = one thousand metric tonnes.
- All tabulated data have been rounded and as a result minor computational errors may occur.
- The Mineral Resource is reported in accordance with the guidelines of the 2012 Edition of The Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves (“'the JORC Code”).
- Assumed open pit mining with 2 million tonne per annum CIL plant.
-
A Whittle optimised pit shell was used to report open-pit Mineral Resources. The Whittle pits and cut-off grades were derived using the following assumed technical parameters:
- Pit slope angle:
- Oxide: All zones = 49°
-
Fresh: 3K & 4K = 64°, RH & SZ = 62°, Main & West = 58°
- Dilution 10%, Mining Losses 5%
- Carbon in Leach Recovery for Residue Grade (g/t) in Oxide:
- 3K: y=0.0513*ln[head grade (g/t)]+0.1392
- All other zones: y=0.0596*ln[head grade (g/t)]+0.0921
- Carbon in Leach Recovery for Solution Grade in Oxide: For all zones excl. 3K: 91.7%, 3K only: 87.7%
- Carbon in Leach Recovery for Solution Grade in Fresh for all zones: 69.43%
- Metallurgical factors based on initial metallurgical test-work.
-
Cost and revenue assumptions:
- Gold Price: USD 2 300/oz, 99.5% payability for nett of USD 2 254.17/oz
- Total mining cost: 2.1 USD/t, Cost adjustment for open-pit depth USD 0.03 per 10 vertical m.
- Total Processing cost: 9.94 USD/t
- Refining and Transport Cost: USD 0.56/oz
- G&A: 2.87 USD/t ore.
- State Royalty 1.5%.
Jibal Qutman MRE Comparison
In May 2015, KEFI released MRE of 28.4 million tonnes at 0.80g/t gold, containing 733,045 ounces for Jibal Qutman.
Key changes in the updated Jibal Qutman MRE are that:
- Oxide Resources have increased from 287,000 ounces to 318,000 ounces
- Indicated Resources have increased from 18.0Mt to 30.5Mt (to 83% of total MRE)
- Total tonnage has increased 8.6Mt to 37.0Mt (+30%)
- Total ounces have increased 169,000 ounces to 902,000 ounces (+23%)
The upgrading of and increase in the MRE is largely driven by additional drilling extending mineralisation at Red Hill and better defining the resources in key high grade areas, which when coupled with the higher gold price has allowed the whittle pits to drive deeper and expand along strike.
Competent Person Statement – Jibal Quatman
The Jibal Qutman Mineral Resource estimates were completed by Mr. Jeremy Charles Witley (BSc Hons, MSc (Eng.)) who is a geologist with 36 years’ experience in base and precious metals exploration and mining as well as Mineral Resource evaluation and reporting. He is a Principal Mineral Resource Consultant for The MSA Group (an independent consulting company). He is registered with the South African Council for Natural Scientific Professions (“SACNASP”), is a Fellow of the Geological Society of South Africa (“GSSA”) and a Fellow of the Professional Society of Independent Experts of the Subsurface Resources (“PONEN”), Kazakhstan. Mr. Witley has the appropriate relevant qualifications and experience to be considered a “Competent Person” as defined by JORC (2012) for the style and type of mineralisation and activity being undertaken.
The information in this announcement that relates to Exploration Results and geological interpretation is based on information compiled by Mr Tomos Bryan, for Gold & Minerals Limited. Mr Bryan is a member of the Australasian Institute of Mining and Metallurgy ("AusIMM"). Mr Bryan is a geologist with sufficient relevant experience for Company reporting to qualify as a Competent Person as defined in the JORC Code 2012. Mr Bryan consents to the inclusion in this announcement of the non-financial matters based on this information in the form and context in which it appears.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 59 minutes ago IWG
- 59 minutes ago Porvair
- 13 hours ago Colefax Group
- 15 hours ago Hays
- 15 hours ago Aberdeen Group plc