
Interim Results for six-month ending 30 June 2026
Summary by AI BETAClose X

21 September 2026
CleanTech Lithium PLC
(“CleanTech Lithium" or “CTL” or the “Company”)
Interim Results for six-month period ending 30 June 2026
CleanTech Lithium PLC (AIM:CTL), an exploration and development company advancing sustainable lithium projects in Chile, is pleased to announce its Interim Results for the six-month period ended 30 June 2026 ("1H 2026" or "the Period"). These results have been formally reviewed by the Company’s auditors for the purposes of the planned listing on the ASX.
Highlights from the period and events following the period end include:
- Special Lithium Operating Contract (CEOL): CTL agreed the contractual terms of a 40-year CEOL for Laguna Verde with Chile’s Ministry of Mining, one of the only non-state companies to achieve this. Those terms set out the proposed contractual framework for project development. Recent comments and interviews from the Minister of Economy and Mining confirm the Decree is subject to final review by the Comptroller General’s Office.
- Pre-Feasibility Study (PFS): Completion of the Laguna Verde PFS defined a maiden Probable Ore Reserve of 378,000 tonnes of LCE and a 15,000 tonne per annum (tpa) operation over 25 years, with a pre-tax NPV8 of approximately US$1.4 billion and pre-tax IRR of approximately 24%.
- Funding and balance sheet: CTL received approximately £1.01 million through advance recovery of Chilean input VAT and announced a £5.3 million fundraising across two tranches, including £2.3 million received by 30 June 2026 and further approximately £3.0 million gross received in days after period end. All outstanding convertible loan notes and accrued premium were converted into equity.
- Strategic partner: Potential partners have progressed through confidentiality, data-room, and initial due-diligence stages following publication of the PFS, as CTL advances its strategic-partner selection and project-financing process.
- Laguna Verde licences: After period end, CTL restructured the consideration payable for its acquisition of 23 Laguna Verde concessions, reducing aggregate cash consideration from US$35.0 million to US$14.0 million and settling historic vendor claims. Of the US$11.5m remaining, US$9.0m is aligned with future production milestones.
- ASX and Board: CTL submitted formal documentation for a proposed ASX dual-listing, targeted for Q4 2026 subject to regulatory approval and market conditions, and appointed Todd Ross and Leo Koot as Non-Executive Directors.
- Direct Lithium Extraction (DLE): CTL continued to validate and optimise its DLE process. After the period end, five campaigns produced approximately 330kg of high-purity lithium carbonate from Laguna Verde eluate, with final product purity of 99.9%.
Ignacio Mehech, Chief Executive Officer of CleanTech Lithium Plc said:
“I joined the company 18 months ago and my goal was to deliver the PFS for Laguna Verde, scale lithium carbonate production, and secure the CEOL for the project. We have achieved two of these critical milestones, with the CEOL, we believe, just around the corner following the recent comments made by the Minister of Economy and Mining at Chile Day in London and recent interviews. With a change of government in Chile, there is a growing optimistic feeling that Chile is committed to expand the lithium industry and invite investment into the country.
With this backdrop, our focus is firmly on execution: advancing the remaining technical work to move towards the Definitive Feasibility Study (DFS), commence the environmental impact assessment (EIA) and permitting work, and selecting the right strategic partner. In addition with the ASX dual-listing, the next few months are very important for the Company, and we will continue to manage capital carefully and maintain close engagement with government, communities, and potential partners as we work to realise the long-term value of Laguna Verde for all stakeholders.”
CEO REVIEW
CleanTech Lithium starts exciting new chapter
The first half of 2026 was a significant period for CleanTech Lithium. We agreed the terms of the Special Lithium Operating Contract (CEOL) for Laguna Verde with the Ministry of Mining in Chile, one of the only non-state companies to achieve this, we completed the project’s Pre-Feasibility Study (PFS) which set out the strong economics for the project, and we continued to optimise the lithium carbonate production process, proving the entire flowsheet from brine to final battery-grade product. We are one of the most advanced companies in Chile developing a Direct Lithium Extraction (“DLE”) project, against a backdrop of a new government in Chile that is fully supportive of scaling the country's lithium production.
The importance of these milestones in the first six months of the year extends beyond the progress made because they mark a change in the maturity of CleanTech Lithium. We have moved from being a greenfield company focused principally on establishing a resource into the next phase of project-development.
Our focus is now firmly on execution: completing the technical and environmental work required to support a Definitive Feasibility Study (DFS) and Environmental Impact Assessment (EIA), selecting the right strategic partner and establishing a credible financing pathway through to a Final Investment Decision (FID) and, ultimately, building the project. This is a demanding stage in the development of any major industrial project, and it will require sustained technical progress, disciplined use of capital, and close engagement with government, indigenous communities, prospective partners, and shareholders.
Setting a strong foundation for long-term success
In March 2026, CleanTech Lithium and the Chilean Ministry of Mining formally agreed the contractual terms of the CEOL for Laguna Verde. The 40-year contract covers the whole project life: from evaluation, construction, lithium production, and ultimately to closure. Agreeing these terms represented a significant de-risking event because it provides the long-term contractual framework within which Laguna Verde will be developed.
The decree approving the contract was subsequently submitted to the Comptroller General’s Office for its final constitutional and legal review. Although we had initially expected this administrative process to be completed during the second quarter, it has taken longer than anticipated as the Comptroller works through the CEOL decrees submitted by the previous Government. We have had positive engagement with the new Ministers and will be updating the market and our shareholders as soon as we have material news on the ratification.
Completion of the Laguna Verde PFS at the end of March was the principal technical milestone of the period. The study declared a maiden Probable Ore Reserve of 378,000 tonnes of lithium carbonate equivalent and outlined a 15,000 tonnes per annum operation over 25 years. It reported a pre-tax net present value, using an 8% discount rate, of approximately US$1.37 billion and a pre-tax internal rate of return of approximately 24.2%.
|
Key economic metrics from the Pre-Feasibility Study: |
|
|
Pre-Tax NPV8 |
US$1.37bn |
|
Pre-Tax IRR |
24.2% |
|
Post-Tax NPV8 |
US$959 million |
|
Post-Tax IRR |
21.2% |
|
Capex (including contingency of c. 20%) |
US$748 million |
|
Opex |
US$5,768 per tonne |
|
Payback Period |
4 Years |
The PFS provides a robust basis for the next stage of engineering, permitting, and strategic partner engagement. It supports our view that Laguna Verde has the potential to become a competitive producer of battery-grade lithium carbonate using DLE, while giving prospective partners a detailed technical and economic foundation on which to assess the project.
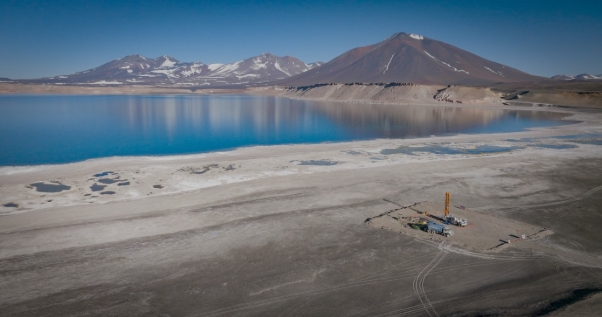
Fig. 1: Laguna Verde
From PFS to development execution
After finalising the PFS, we are now moving forwards to develop the EIA and DFS and continuing our technical work programmes so that momentum is maintained while the strategic-partner selection process progresses.
These programmes include, for example, on-going validation of our DLE processes and comparison of alternative adsorbents and evaluation of spent-brine reinjection options. Since the period end, approximately 330kg of high-purity lithium carbonate has been produced from Laguna Verde eluate, with the final of five campaigns achieving a purity of 99.91%. Further DFS-level adsorbent testing and reinjection analysis is also underway with industry leading companies from USA, Europe, and China. This work intends to confirm the preferred technical configuration and identify opportunities to improve efficiency and project economics ahead of the DFS.
|
|
|
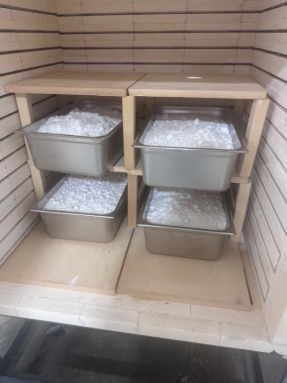
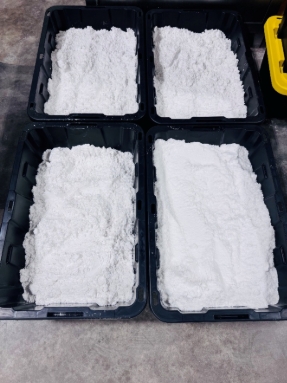
Fig. 2: Lithium Carbonate in drying kiln and product in bulk storage (via Empower)
Environmental and social considerations remain integral to our approach. The proposed use of DLE and reinjection is intended to avoid the extensive evaporation ponds associated with conventional brine operations. Our long-standing engagement and agreements with local indigenous communities provide an important foundation as we prepare the EIA. We recognise that maintaining trust through transparent and consistent engagement is essential throughout the development of Laguna Verde.
Funding the next phase
All of this will require an appropriately structured funding solution and a partner with the capacity and alignment to support the project. At the beginning of the year, we appointed Cutfield Freeman & Co as corporate finance adviser to assist with the strategic-partner selection and the financing pathway towards commercial production.
Following publication of the PFS, interested parties have progressed through confidentiality, data-room and initial due-diligence stages. In June, I travelled to China, South Korea, and the USA to meet with notable industry players in the battery supply chain. It was a worthwhile trip to hear directly the motivations and ambitions of leading companies looking to secure their supply of lithium. The selection of a strategic partner is critical for project development, and our priority is to maximise value for shareholders. The structure must support development of Laguna Verde while preserving appropriate value and strategic flexibility for CTL shareholders.
In March, Atacama Salt Lakes SpA received approximately CLP1.25 billion, equivalent to £1.01 million, through the advance recovery of VAT incurred on Laguna Verde. The receipt strengthened the Group’s funding position and, importantly, established a mechanism through which VAT arising on future qualifying project expenditure should be recoverable more promptly.
During June, we announced an institutional placing and retail offer together with the agreed conversion of the outstanding loan notes and accrued premium into equity. Shareholders approved the relevant resolutions after the period end. The funds provide capital for priority activities while the strategic partner selection process progresses, and the conversion of the loan notes removed the cash burden of debt repayment whilst simplifying the Company’s capital structure. At the reporting date, £2.3 million had been received, in the days following 30 June 2026 a further £3.0 million before expenses was also received.
Since the period end, CTL and its subsidiaries, CleanTech Laguna Verde SpA and Atacama Salt Lakes SpA, have also entered into a Settlement and Amendment Agreement (SAA) with the vendors of 23 mining concessions at Laguna Verde. The agreement amends the original Sale and Purchase Agreement (SPA) dated April 2024 and provides for the withdrawal and settlement of the historic legal claims and allegations between the parties. Reaching this agreement addressed several outstanding issues at once and demonstrates the vendors' long-term belief in the overall success of the Company.
The agreement reduces the aggregate cash consideration for the concessions from US$35.0 million to US$14.0 million, of which US$2.5 million has been paid. Of the US$11.5 million remaining, US$9.0 million will only become payable when specified lithium sales-volume milestones are achieved. CTL will also issue an aggregate of 6.6 million consideration shares in three equally sized tranches, each linked to specified milestones and each subject to a six-month lock-in. The revised structure substantially aligns the remaining consideration with future financing, construction and production milestones at Laguna Verde.
Political and regulatory environment in Chile
Chile has also seen a change in government during the period, with José Antonio Kast being appointed President and setting out plans to stimulate economic growth through his National Reconstruction Plan. Most relevant to the Company and the wider lithium industry is a proposed reduction in corporate tax from 27% to 23%, to be phased in over the coming years. The new government has also signalled a clear commitment to streamlining the environmental permitting process, with the stated aim of supporting the growth of new companies and ensuring that projects are not delayed by administrative or procedural inefficiencies.
Advancing the ASX listing and strengthening the board
We are advancing CTL’s proposed admission to the Australian Securities Exchange (ASX) and have submitted formal application documentation to the ASX authorities. Subject to completion of the regulatory process and market conditions, we are targeting completion during the fourth quarter of 2026. The proposed listing is intended to broaden access to specialist mining and lithium investors, improve liquidity and increase market visibility. It is an enabler of our strategy rather than a change to it, and Laguna Verde remains at the centre of our investment proposition.
During the period, we have also sought to strengthen our board. April 2026 saw the appointment of Todd Ross as our Australian-based Non-Executive Director. Todd will play an integral role in our marketing efforts in the local market. He has an extensive background in investment banking and project finance, having served as Managing Director, Head of Western Australia and Head of Metals and Mining at BNP Paribas. During his more than 20-year banking career, Todd played a key role in the development of BNP Paribas' position as a leading financier in the Australian lithium sector contributing to a number of major lithium mining project financings between 2016 and 2022 including a major transaction involving Pilbara Minerals. Todd is currently Managing Director and CEO of ASX-listed Talisman Mining Ltd, having been appointed in June 2026.
In June 2026, Leo Koot was also appointed as a Non-Executive Director, who since August 2025 acted as a Board Observer on behalf of the convertible loan noteholders. Leo brings more than 30 years of experience in financing and developing projects across the energy and natural resources sector. His career spans complex, capital-intensive projects at the international level, including the navigation and delivery of a billion-dollar project in the Middle East.
We are grateful for the support shown by existing and new shareholders. Since joining this Company as CEO approximately 18 months ago, I have been encouraged by the project development we have been able to achieve, the partners we are collaborating with, and the quality of engagement with our shareholders from all over the world. I believe we are at a very promising moment in the Company's history, and we are putting in place the right team to continue this momentum for the next set of milestones.
A longer-term regional ambition
Laguna Verde is our operational and capital-allocation priority. Successfully advancing the project will establish the capabilities, relationships, and funding platform from which we can grow.
However, our longer-term ambition is not to remain a one-project company. We have retained the licences at Viento Andino and Arenas Blancas, which sit on the periphery of Salar de Atacama, ready and waiting to be further developed once additional funds are secured. Furthermore, we believe there are opportunities to build a broader Latin American mining and development business over time, with greater asset and geographic diversity. We will approach that ambition cautiously and selectively, using our existing knowledge and experience, assessing opportunities against disciplined technical, jurisdictional and capital-allocation criteria. Any expansion will be appropriately timed and must complement, rather than compromise, the delivery and funding of Laguna Verde.
Outlook
Our priorities for the remainder of 2026 are clear: confirm the ratification of the CEOL for Laguna Verde; advance the selection of a strategic partner; prepare the DFS and EIA programmes; complete the priority process-optimisation studies which are underway; and complete the proposed ASX dual-listing. We will continue to manage expenditure carefully and align the pace of activity with available funding.
The progress achieved during the first half, together with the post-period settlement with the Laguna Verde Vendors, has strengthened the foundations of the project and removed associated legal overhangs. CTL enters this next phase with a positive PFS, an agreed CEOL framework, further results to report on DLE process work, a restructured licence consideration and an active strategic partner-selection process.
I would like to thank our employees, contractors and technical partners for their commitment; the Chilean authorities, the indigenous communities and other local stakeholders for their constructive engagement; and our shareholders for their continued support. We are now focused on converting the progress achieved to date into the next stage of development for Laguna Verde and long-term value for CTL’s stakeholders.
Ignacio Mehech, Chief Executive Officer
CleanTech Lithium Plc
INDEPENDENT REVIEW REPORT TO CLEANTECH LITHIUM PLC
Conclusion
We have been engaged by the company to review the condensed set of financial statements in the half-yearly financial report for the six months ended 30 June 2026 which comprises:
- the condensed consolidated statement of comprehensive income
- the condensed consolidated statement of financial position
- the condensed consolidated statement of changes in equity
- the condensed statement of consolidated cash flows and
- the related explanatory notes.
Based on our review, nothing has come to our attention that causes us to believe that the condensed set of financial statements in the half-yearly financial report for the six months ended 30 June 2026 is not prepared, in all material respects, in accordance with UK-adopted International Accounting Standard 34 and the AIM Rules for Companies.
Basis for Conclusion
We conducted our review in accordance with International Standard on Review Engagements (UK) 2410, “Review of Interim Financial Information Performed by the Independent Auditor of the Entity” issued for use in the United Kingdom. A review of interim financial information consists of making enquiries, primarily of persons responsible for financial and accounting matters, and applying analytical and other review procedures. A review is substantially less in scope than an audit conducted in accordance with International Standards on Auditing (UK) and consequently does not enable us to obtain assurance that we would become aware of all significant matters that might be identified in an audit. Accordingly, we do not express an audit opinion.
As disclosed in note 2, the annual financial statements of the group are prepared in accordance with UK-adopted international accounting standards. The condensed set of financial statements included in this half-yearly financial report has been prepared in accordance with UK-adopted International Accounting Standard 34, “Interim Financial Reporting”.
Conclusions Relating to Going Concern
Based on our review procedures, which are less extensive than those performed in an audit as described in the Basis of Conclusion section of this report, nothing has come to our attention to suggest that management have inappropriately adopted the going concern basis of accounting or that management have identified material uncertainties relating to going concern that are not appropriately disclosed.
This conclusion is based on the review procedures performed in accordance with this ISRE (UK), however future events or conditions may cause the entity to cease to continue as a going concern.
Material Uncertainty Related to Going Concern
We draw attention to note 2 in the interim financial information which indicates that the group is in a pre-revenue phase of development and until its transition to revenue generation and profitability the group will be required to rely on externally sourced funding to continue as a going concern. As stated in note 2, these events or conditions, indicate that a material uncertainty exists that may cast significant doubt on the entity’s ability to continue as a going concern.
Our conclusion is not modified in respect of the matter.
Responsibilities of directors
The directors are responsible for preparing the half-yearly financial report in accordance with the AIM Rules for Companies.
In preparing the half-yearly financial report, the directors are responsible for assessing the group’s ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless the directors either intend to liquidate the group or to cease operations, or have no realistic alternative but to do so.
Auditor’s Responsibilities for the review of the financial information
In reviewing the half-yearly report, we are responsible for expressing to the Company a conclusion on the condensed set of financial statement in the half-yearly financial report. Our conclusion, including our Conclusions Relating to Going Concern, are based on procedures that are less extensive than audit procedures, as described in the Basis for Conclusion paragraph of this report.
Use of our report
This report is made solely to the Company in accordance with International Standard on Review Engagements 2410 (UK) “Review of Interim Financial Information Performed by the Independent Auditor of the Entity” issued by the Financial Reporting Council. Our review work has been undertaken so that we might state to the Company those matters we are required to state to them in this report and for no other purpose. To the fullest extent permitted by law, we do not accept or assume responsibility to anyone other than the Company for our review work, for this report, or for the conclusions we have formed.
Crowe U.K. LLP,
Statutory Auditors, London, United Kingdom
18 September 2026
INTERIM FINANCIAL RESULTS
Condensed Consolidated Statement of Comprehensive Income
|
|
|
Note |
Unaudited |
Unaudited | |
|
|
|
|
£ |
£ | |
|
Income |
|
|
- |
- | |
|
Administrative costs |
|
(1,467,128) |
(1,897,434) | ||
|
Operating loss |
|
|
(1,467,128) |
(1,897,434) | |
|
|
|
|
|
| |
|
Finance costs |
|
(1,053,715) |
(884,847) | ||
|
Foreign exchange (loss) / income |
|
(525,634) |
856,136 | ||
|
Loss before tax |
|
|
(3,046,477) |
(1,926,145) | |
|
|
|
|
|
| |
|
Income tax |
|
- |
| ||
|
Loss for the period after tax |
|
|
(3,046,477) |
(1,926,145) | |
|
|
|
|
|
| |
|
Other comprehensive income / (loss): |
|
|
|
| |
|
Exchange differences arising on translation of functional currencies |
|
367,241 |
(470,795) | ||
|
Total comprehensive loss for the period |
|
|
(2,679,236) |
(2,396,940) | |
|
|
|
|
|
| |
|
Loss per share basic |
|
(0.014) |
(0.020) | ||
The accompanying notes are an integral part of these unaudited condensed consolidated interim financial statements.
Condensed Consolidated Statement of Financial Position
|
|
|
Unaudited 30-Jun-26 |
Audited |
|
|
Note |
£ |
£ |
|
|
|
|
|
|
Exploration and evaluation assets |
43,427,524 |
42,108,783 | |
|
Non-current assets |
|
43,427,524 |
42,108,783 |
|
|
|
|
|
|
Cash and cash equivalents |
|
2,429,086 |
1,837,420 |
|
Trade and other receivables |
222,149 |
1,239,535 | |
|
Current assets |
|
2,651,235 |
3,076,955 |
|
|
|
|
|
|
Trade and other payables |
(81,507) |
(176,239) | |
|
Provisions and accruals |
(825,405) |
(821,148) | |
|
Loans notes |
- |
(3,086,617) | |
|
Deferred consideration |
(2,469,083) |
(3,013,331) | |
|
Current liabilities |
|
(3,375,995) |
(7,097,335) |
|
|
|
|
|
|
Deferred consideration |
(20,296,279) |
(18,697,954) | |
|
Non-current liabilities |
|
(20,296,279) |
(18,697,954) |
|
|
|
|
|
|
Net assets |
|
22,406,486 |
19,390,449 |
|
|
|
|
|
|
Share capital |
|
34,031,519 |
32,218,322 |
|
Capital reserve |
|
(77,237) |
(77,237) |
|
Share based payment reserve |
14,676,322 |
10,794,246 | |
|
Foreign exchange reserve |
|
(1,678,574) |
(2,045,815) |
|
Accumulated losses |
|
(24,545,544) |
(21,499,067) |
|
|
|
|
|
|
Equity and reserves |
|
22,406,486 |
19,390,449 |
The accompanying notes are an integral part of these consolidated financial statements.
These financial statements were approved and authorised for issue by the Board of directors on 18 September 2026 and are signed on its behalf by: Ignacio Mehech, Director
Condensed Consolidated Statement of Changes in Equity
|
|
Share capital |
Capital reserve |
Share based payment reserve |
Foreign exchange reserve |
Accumulated losses |
Total |
|
|
£ |
£ |
£ |
£ |
£ |
£ |
|
|
|
|
|
|
|
|
|
At 1 January 2025 |
28,443,989 |
(77,237) |
6,869,574 |
(2,595,588) |
(18,690,502) |
13,950,236 |
|
|
|
|
|
|
|
|
|
Loss for the period |
- |
- |
- |
- |
(1,926,145) |
(1,926,145) |
|
Other comprehensive loss |
- |
- |
- |
(470,795) |
- |
(470,795) |
|
Total comprehensive loss |
- |
- |
- |
(470,795) |
(1,926,145) |
(2,396,940) |
|
|
|
|
|
|
|
|
|
Shares issued |
2,297,840 |
- |
- |
- |
- |
2,297,840 |
|
Share options and warrants |
(209,280) |
- |
983,360 |
- |
- |
774,080 |
|
30 June 2025 |
30,532,549 |
(77,237) |
7,852,934 |
(3,066,383) |
(20,616,647) |
14,625,216 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
At 1 January 2026 |
32,218,322 |
(77,237) |
10,794,246 |
(2,045,815) |
(21,499,067) |
19,390,449 |
|
|
|
|
|
|
|
|
|
Loss for the period |
- |
- |
- |
- |
(3,046,477) |
(3,046,477) |
|
Other comprehensive income |
- |
- |
- |
367,241 |
- |
367,241 |
|
Total comprehensive loss |
- |
- |
- |
367,241 |
(3,046,477) |
(2,679,236) |
|
|
|
|
|
|
|
|
|
Shares issued |
1,813,197 |
- |
- |
- |
- |
1,813,197 |
|
Share options and warrants |
- |
- |
3,882,076 |
- |
- |
3,882,076 |
|
|
1,813,197 |
- |
3,882,076 |
- |
- |
5,695,273 |
|
|
|
|
|
|
|
|
|
30 June 2026 |
34,031,519 |
(77,237) |
14,676,322 |
(1,678,574) |
(24,545,544) |
22,406,486 |
The accompanying notes are an integral part of these consolidated financial statements.
These financial statements were approved and authorised for issue by the Board of directors on 18 September 2026 and were signed on their behalf by: Ignacio Mehech, Director
Condensed Consolidated Statement of Cash Flows
|
|
|
Unaudited |
Unaudited |
|
|
Note |
£ |
£ |
|
|
|
|
|
|
Loss after tax for the period |
|
(3,046,477) |
(1,926,145) |
|
Non-cash items: |
|
|
|
|
Fair value of loan note warrants |
|
- |
376,820 |
|
Fair value recognition of share options and warrants |
|
38,130 |
- |
|
Movement in trade and other receivables |
|
1,028,837 |
70,634 |
|
Movement in payables, provisions and accruals |
|
(167,085) |
(677,272) |
|
Finance costs |
|
1,053,715 |
884,847 |
|
Net cash used in operating activities |
|
(1,092,880) |
(1,271,115) |
|
Expenditure on exploration and evaluation assets |
|
(578,493) |
(935,912) |
|
Net cash used in investing activities |
|
(578,493) |
(935,912) |
|
|
|
|
|
|
Proceeds from issue of ordinary shares |
|
2,132,616 |
2,297,840 |
|
Warrants pending issuance |
|
45,386 |
- |
|
Net cash generated from financing activities |
|
2,178,002 |
2,297,840 |
|
|
|
|
|
|
Net cash flow |
|
506,629 |
90,812 |
|
|
|
|
|
|
|
|
|
|
|
Cash and cash equivalents brought forward |
|
1,837,420 |
134,247 |
|
Net cash flow |
|
506,629 |
90,812 |
|
Effect of exchange rate changes |
|
85,037 |
(81,835) |
|
Cash and cash equivalents carried forward |
|
2,429,086 |
143,225 |
The accompanying notes are an integral part of these interim unaudited condensed consolidated financial statements.
Notes to the Financial Statements
1. GENERAL INFORMATION
CleanTech Lithium Plc (“CTL Plc”, or the “Company”)
The condensed consolidated interim financial statements of CleanTech Lithium Plc for the first six months ended 30 June 2026 were approved for issue on 18 September 2026.
CleanTech Lithium Plc was incorporated and registered as a private company, initially with the name CleanTech Lithium (Jersey) Ltd, in Jersey on 1 December 2021 with registered number 139640. It was subsequently reregistered as a public limited company on 20 January 2022 and on 2 February 2022 it changed its name to CleanTech Lithium Plc.
On 14 February 2022, a share-for-share exchange between the shareholders of CleanTech Lithium Ltd (CTL Ltd, or the U.K. entity) and CTL Plc completed, resulting in CTL Plc acquiring and becoming the parent company of CTL Ltd and its wholly owned subsidiaries, together “CleanTech Lithium Group” or the “Group”. References to the Group and Company are made interchangeably in this financial information.
In the year ended 31 December 2024, CleanTech Lithium Chile SpA, a company with registered number, RUT 77.905.882-4, was incorporated to serve as holding company for the Chilean entities. The debt and equity interests held by CTL Ltd in each of the Chilean subsidiaries were transferred to CleanTech Chile SpA and CleanTech Chile SpA issued an equal value of debt and equity as consideration to CleanTech Lithium Limited, such that the transaction had a neutral economic effect for the group.
2. BASIS OF PREPARATION
The condensed consolidated interim financial statements for the Group have been prepared in accordance IAS 34 ‘Interim Financial Reporting’ per the U.K.-adopted international accounting standards. As such, they do not include all the information required for the preparation of the annual consolidated financial statements and should be read in conjunction with the audited consolidated financial statements for the year ended 31 December 2025 of CleanTech Lithium Plc, that can be found on the website: https://www.ctlithium.com. The auditor’s report on those accounts was unmodified but it did make reference to a material uncertainty related to going concern.
The amounts in this document are presented in British Pounds (GBP), unless noted otherwise. Due to rounding, numbers presented throughout these condensed consolidated Interim financial statements may not add up precisely to the totals provided and percentages may not precisely reflect the absolute figures.
A summary of the material accounting policies can be found in the Company’s consolidated financial statements for the year ended 31 December 2025, on pages 49 to 52. The accounting policies used to prepare these condensed consolidated interim financial statements are consistent with those. Furthermore, there are no new standards or interpretations applicable from 1 January 2026 which have a significant impact on these condensed consolidated interim financial statements.
Significant accounting judgments, estimates and assumptions
In preparing this interim financial report, it has been necessary to make judgments, estimates and assumptions to form the basis of presentation, recognition and measurement of the Group’s assets, liabilities, income statement items, accompanying disclosures and the disclosure of contingent liabilities. Uncertainty about these assumptions and estimates could result in outcomes that require a material adjustment to the carrying amount of assets or liabilities affected in future periods.
The significant judgments, estimates and assumptions made when applying the Group’s accounting policies are consistent with those applied to the consolidated financial statements for the year ended 31 December 2025.
Although the judgment relating to the deferred consideration arising on the acquisition of the LV licences remained unchanged at the reporting date, subsequent to 30 June 2026, CleanTech entered into an agreement to amend certain commercial terms of that consideration, as set out in Note 14. These revised terms will require updated judgments in determining the amount and timing of consideration payable.
The significant judgments in assessing the exploration and evaluation assets for the existence of indicators of impairment at the reporting date are set out in Note 9.
Going Concern
The Group is in a pre-revenue phase of development and until its transition to revenue generation and profitability the Group will be required to rely on externally sourced funding to continue as a going concern. The Board recognises this condition may indicate the existence of material uncertainties which in turn may cast doubt on the Group’s ability to continue as a going concern. Notwithstanding, the Directors have a demonstrated record of successfully raising capital for projects and ventures of this nature and are confident in being able to secure the funding needed for the Group to deliver on its commitments and continue as a going concern.
3. ADMINISTRATION EXPENSES
Administration expenses in the six months to 30 June 2026 totalled £1.5 million (H1 2025 £1.9 million), reflecting cash costs of £1.5 million (H1 2025 £1.4 million); in H1 2025, non-cash costs and unrealised foreign exchange gains totalled £0.5 million.
Of the £1.5 million in cash costs, approximately £0.4 million relates to directors and staff costs (H1 2025: £0.4 million), £0.1 million relates to promotion, public and investor relations and travel (H1 2025: £0.1 million), £0.9 million relates to legal and professional support including listing and compliance, audit and insurance costs (H1 2025: £0.7 million), and the balance of £0.1 million comprises a variety of other and general administrative costs (H1 2025: £0.1 million).
4. FINANCE COST
The finance charge in the period of £1.05 million (H1 2025 £0.9 million) reflects the unwinding of deferred consideration discount of £0.9 million (H1 2025: £0.8 million) and the finance costs associated with the loan notes of £0.2 million (H1 2025 £0.1 million). Both charges are non-cash in nature.
5. FOREIGN EXCHANGE ON FINANCING TRANSACTIONS
The foreign exchange loss of £0.5 million reflects the translation exchange on the USD $ denominated buy out of the LV licences and the exchange rate impact of the conversion of the loan notes in June 2026.
6. SEGMENTAL INFORMATION
The Group operates in a single business segment, being the exploration and evaluation of mineral properties, activities which are undertaken in Chile where all the Group’s non-current assets are held.
7. INCOME TAX
The accrued income tax expense continues to be £nil as the Group remains in a loss-making position. No deferred tax asset is recognised on these losses due to the uncertainty over the timing of future profits and gains.
8. LOSS PER SHARE
The calculation of basic loss per ordinary share is based on the loss after tax and on the weighted average number of ordinary shares in issue during the period.
A diluted loss per share assumes conversion of all potentially dilutive Ordinary Shares arising from the share schemes. Potential ordinary shares resulting from the exercise of warrants and options have an anti-dilutive effect due to the Group being in a loss position. As a result, diluted loss per share is disclosed as the same value as basic loss per share.
|
|
|
Unaudited 30-Jun-2026 |
Unaudited | |
|
Basic and diluted loss per share |
|
|
| |
|
Loss after taxation |
|
(3,046,477) |
(1,926,145) | |
|
Basic weighted average number of ordinary shares (millions) |
|
215.20 |
96.35 | |
|
Basic loss per share (GBP £) |
|
(0.014) |
(0.020) | |
9. EXPLORATION AND EVALUATION ASSETS
Expenses incurred to date by the Chilean entities on feasibility studies, mineral exploration and delineation were capitalised as “exploration and evaluation assets” within “non-current assets” in accordance with the Group’s accounting policy.
|
Exploration and evaluation assets |
Unaudited six months ended 30-Jun-2026 |
Audited Year ended 31-Dec-2025 |
|
|
£ |
£ |
|
|
|
|
|
Opening balance |
42,108,783 |
32,583,274 |
|
Fair value of licence acquisitions |
- |
7,173,664 |
|
Additions |
589,896 |
1,404,740 |
|
Effect of foreign exchange translations |
728,846 |
947,105 |
|
Closing balance |
43,427,524 |
42,108,783 |
Of the £0.6 million additions in the period, approximately £0.2 million related to pre-feasibility costs for the Laguna Verde project and £0.4 million to mining licences costs.
The fair value of licence acquisitions in 2025 reflects the present value of total consideration for licences acquired under the LV Purchase Agreement (refer Note 14).
Impairment assessments
The Directors assess for impairment when facts and circumstances suggest that the carrying amount of an exploration & evaluation asset (E&E) may exceed its recoverable amount. In making this assessment, the Directors have regard to the facts and circumstances noted in IFRS 6 paragraph 20. In performing their assessment of each of these factors, at 18 September 2026, the Directors have:
- reviewed the time period that the Group has the right to explore the area and noted no instances of expiration, or licences that are expected to expire in the near future and not be renewed;
- determined that further E&E expenditure is either budgeted or planned for all licences;
- not decided to discontinue exploration activity due to there being a lack of quantifiable mineral resource; and
- not identified any instances where sufficient data exists to indicate that there are licences where the E&E spend is unlikely to be recovered from successful development or sale.
Based on the above assessment, the Directors are not aware of any facts or circumstances that would suggest the carrying amount of the E&E asset may exceed its recoverable amount. Consequently, the Directors do not consider there is any indication of impairment.
10. TRADE AND OTHER RECEIVABLES
|
|
Unaudited as at 30-Jun-26 |
Audited |
|
|
£ |
£ |
|
|
|
|
|
Prepayments and deposits |
61,586 |
51,084 |
|
VAT |
144,916 |
1,154,564 |
|
Other receivables |
15,647 |
33,887 |
|
Total |
222,149 |
1,239,535 |
Prepayments and deposits largely reflect prepaid insurance and other commercial subscriptions which renew variously and annually as well as office rental deposit amounts paid.
In February 2026, VAT which had been historically incurred on the Laguna Verde project was approved for advance refund. Please see Note 16 for fuller description of the contingent liability.
Other receivables comprise multiple smaller working capital balances in Chile.
11. SHARE BASED PAYMENTS AND WARRANT RESERVE
Share based payments
The Group’s share-based-payment reserve increased by approximately £3.88 million during the six months ended 30 June 2026. This movement primarily reflected the recognition of fair value of existing share options and the fair value of warrants associated with the first tranche of the fundraising announced in June 2026 (see below). This movement is non-cash in nature.
Although a contractual obligation arose to grant warrants pursuant to the first tranche of the fundraising in June 2026, the granting of warrants was deferred until shareholder approval was received at the general meeting on 1 July 2026 (see below). As such, no warrants or share options were granted during the six months ended 30 June 2026. Approximately 33,000 share options with an exercise price of £1.14 were relinquished following changes to the Company’s management team and 159,350 warrants, originally issued to subscribers in the February 2025 fundraising, were exercised at an exercise price of £0.11 per ordinary share. The exercise resulted in the issue of ordinary shares in March 2026.
June 2026 fundraising warrants
In connection with the fundraising announced in June 2026, the Company issued approximately 39.2 million ordinary shares under the first tranche of the placing and retail offer. The terms of the fundraising included the issue of associated warrants, subject to shareholder approval.
The estimated value of the warrants relating to the tranche-one shares was approximately £0.8 million. This amount was recorded as an allocation within a warrant reserve in equity and did not affect the Group’s loss for the period, total equity or cash balances.
On 1 July 2026, shareholders approved the issue of these warrants and they were subsequently issued by the Company.
Awards approved after the reporting date
Also on 1 July 2026, shareholders approved the granting of share options to certain Directors and members of senior management. The awards comprised 19,966,431 options, of which 17,466,321 options are exercisable at £0.02 per ordinary share and 2,500,000 options are exercisable at £0.20 per ordinary share.
Shareholders also approved the issue of warrants to the Company’s bookrunner and to subscribers in connection with the June 2026 placing and retail offer. These awards were approved after the reporting date and are not included in the movements in share options and warrants for the period ended 30 June 2026.
12. PAYABLES, PROVISIONS AND ACCRUALS
|
|
Unaudited |
Audited |
|
|
30-Jun-2026 |
31-Dec-25 |
|
|
£ |
£ |
|
Trade payables |
(81,507) |
(176,239) |
|
Provisions |
(74,110) |
(72,848) |
|
Other taxes and social security |
(43,676) |
(28,434) |
|
Accruals |
(707,619) |
(719,866) |
|
Total |
(906,912) |
(997,387) |
Trade and other payables include routine trade creditors.
Other taxes and social security balances largely relate to people-related costs and tax balances at the period end. Accruals include routine accruals for professional services rendered not invoiced at period end.
13. LOAN NOTES
At 31 December 2025, the Group had Convertible Loan Notes (“CLNs”) with a carrying amount of £3,086,617. The CLNs comprised instruments denominated in pounds sterling and Australian dollars, had a maturity date of 30 June 2026 and carried a premium of 12% per annum payable on redemption or conversion. The liability component of the CLNs was measured at amortised cost using the effective interest method. The conversion option attached to the sterling-denominated CLNs was classified as an equity component under IAS 32. The conversion option attached to the Australian-dollar-denominated CLNs did not meet the “fixed-for-fixed” criterion and was accounted for separately as a derivative financial liability measured at fair value through profit or loss. Further details of the restructuring and accounting treatment of the CLNs are set out in Note 18 to the Group’s financial statements for the year ended 31 December 2025
On 4 June 2026, following receipt of conversion notices from the CLN holders, the Company agreed that all amounts outstanding under the CLNs, together with the premium accrued and the premium that would otherwise have accrued to the contractual maturity date of 30 June 2026, would be converted into ordinary shares. The aggregate amounts converted were AUD 5,064,778 and £758,022.
The conversion became effective on 10 June 2026 on admission of 64,464,675 new ordinary shares of £0.02 each to trading on AIM. The conversion shares represented 31.5% of the Company’s issued ordinary share capital immediately before the conversion and 20.9% of the issued ordinary share capital immediately following the associated first admission. The conversion resulted in the full settlement of the CLNs and, accordingly, no CLNs remained outstanding at 30 June 2026.
Immediately before conversion, the liability component of the CLNs was increased by an effective-interest charge of £0.2 million for the period from 1 January 2026 to 10 June 2026. The Australian-dollar conversion derivative was remeasured to fair value at the conversion date, resulting in a fair-value gain of £0.06 million recognised within finance income. The carrying amounts derecognised and amounts recognised in equity on conversion were as follows:
|
|
£ |
|
Carrying amount of CLN liability as at 1 January 2026 |
3,086,617 |
|
Effective-interest charge and premium accretion to conversion date |
196,175 |
|
Foreign-exchange movement |
(59,558) |
|
Carrying amount of CLN liability derecognised on conversion |
3,223,234 |
|
|
|
|
Share capital: 64,464,675 ordinary shares of £0.02 each |
1,289,294 |
|
Share premium / other equity reserve recognised on conversion |
1,933,940 |
|
|
3,223,234 |
|
CLNs and associated derivative liability as at 30 June 2026 |
- |
The conversion was a non-cash financing transaction. It is therefore excluded from cash proceeds from financing activities in the condensed consolidated statement of cash flows and disclosed separately as a material non-cash transaction.
14. DEFERRED CONSIDERATION
Laguna Verde Option buy-out
In April 2024, CleanTech Laguna Verde SpA (“CLV”), a wholly owned subsidiary of the Group, entered into a sale and purchase agreement (the “LV Purchase Agreement”) to acquire the legal and beneficial interest in 23 mining licences at Laguna Verde. The original contractual cash consideration was US$35.0 million, comprising fixed payments of US$10.5 million and two deferred payments totalling US$24.5 million linked to specified production milestones or, if earlier, the tenth anniversary of the agreement.
The acquisition was accounted for as an asset acquisition. The fair value of the consideration was recognised as part of the cost of the relevant exploration and evaluation assets, with the associated deferred consideration recognised as a financial liability. The non-current element of the deferred consideration was initially discounted using a rate of 8%, with subsequent unwinding of the discount recognised within finance costs.
At 31 December 2025, the second and third fixed milestone payments under the LV Purchase Agreement remained unpaid and were included within current deferred consideration. During the six months ended 30 June 2026, the Group recognised finance costs of £0.9 million from unwinding the discount on the deferred consideration and foreign-exchange losses of £0.5 million. The carrying amount of the deferred consideration relating specifically to the LV Purchase Agreement was as follows:
|
|
Unaudited at 30-Jun-26 |
Audited at 31-Dec-25 |
|
|
£ |
£ |
|
|
|
|
|
Deferred consideration, current |
2,469,083 |
3,013,331 |
|
Deferred consideration, non-current |
20,296,279 |
18,697,954 |
|
Total |
22,765,362 |
21,711,285 |
The Group continued to recognise the obligations arising under the LV Purchase Agreement at 30 June 2026. The amounts recognised at that date have not been adjusted for the Settlement and Amendment Agreement described below, which was executed after the reporting date.
At 30 June 2026, legal proceedings brought by the vendors in relation to unpaid milestone consideration remained ongoing and no separate provision has been made in respect of the proceedings. The Group acknowledged that the relevant contractual milestone payments were due and these amounts were included within deferred consideration. The Directors considered whether these matters, including the lien and reversionary-interest provisions under the original agreement, indicated that the Laguna Verde exploration and evaluation assets might be impaired and concluded that no impairment was required at 30 June 2026.
On 19 August 2026, the Company, CLV and Atacama Salt Lakes SpA entered into a Settlement and Amendment Agreement (“SAA”) with the vendors. The SAA amended the LV Purchase Agreement and established a process for the withdrawal and settlement of the historic legal claims and allegations between the parties.
Under the SAA, aggregate cash consideration for the licences was reduced from US$35.0 million to US$14.0 million. Of the revised cash consideration, US$2.5 million has been paid, including US$1.25 million paid on execution of the SAA. Of the remaining US$11.5 million, US$9.0 million is payable only after specified cumulative lithium sales-volume milestones are achieved at Laguna Verde.
In addition to the revised cash consideration, the Company agreed to issue 6,600,000 new ordinary shares to the vendors in three tranches of 2,200,000 shares per tranche. The first tranche was issuable on execution of the SAA. The second and third tranches are conditional upon, respectively, receipt of more than US$10.0 million under a strategic partnership agreement and commencement of construction at Laguna Verde. Each tranche is subject to a six-month lock-in arrangement.
The revised consideration is summarised below:
|
|
Milestone |
Date |
USD $m |
Shares in # |
Rev. Interest % |
|
1 |
Signature of the Sale and Purchase Agreement
|
Apr-24 |
1.25 |
- |
- |
|
2 |
Signature of the SAA |
Aug-26 |
1.25 |
2,200,000 |
- |
|
3 |
Receipt of funds from an agreement with a Strategic Partnership which exceeds US$10 million |
TBC
|
1.00 |
2,200,000 |
49% |
|
4 |
Start of construction at Laguna Verde |
TBC |
1.50 |
2,200,000 |
40% |
|
5 |
60 days after reaching cumulative sales of 10,000 tonnes of LCE or Lithium derivatives at Laguna Verde |
TBC |
4.50 |
- |
30% |
|
6 |
60 days after reaching cumulative sales of 35,000 tonnes of LCE or Lithium derivatives at Laguna Verde |
TBC |
4.50 |
- |
20% |
|
|
Total consideration |
|
14.00 |
6,600,000 |
|
If specified milestone payments are not made, the vendors may become entitled to a reversionary interest of up to 49% of the shares held by Atacama Salt Lakes SpA in CLV. The applicable percentage reduces for later milestones. Atacama Salt Lakes SpA retains the right to repurchase any shares transferred under this mechanism by settling the missed milestone payment that triggered the transfer.
The vendors are required under the SAA to take the agreed steps to waive, withdraw and settle the historic legal claims and to withdraw the criminal allegations previously filed with the Public Prosecutor’s office.
The SAA is considered a material non-adjusting event after the reporting period because it was executed after 30 June 2026 and introduced materially revised contractual terms. Accordingly, the amounts recognised at 30 June 2026 continue to reflect the LV Purchase Agreement in force at that date.
The SAA reduces the Group’s remaining nominal contingent cash payments under the LV Purchase Agreement to US$11.5 million and introduces contingent share consideration; the revised reversionary-interest mechanism described above is substantively unchanged from the original purchase agreement. The Group is assessing the fair value and accounting classification of the revised consideration and the accounting effect of modifying the existing deferred-consideration liability. Accordingly, the accounting effect of the SAA cannot yet be estimated reliably.
15. SHARE CAPITAL
In early June 2026, CleanTech announced a two-tranche equity fundraising. Under the terms of the fundraising, investors were issued one warrant for every two subscription shares subscribed for.
The full balance of the relevant share authority available to directors at that date were issued as new ordinary shares, and the issue of the associated warrants deferred pending shareholder approval at the General Meeting on 1 July 2026, namely one day after the period end. In addition to approving the warrants associated with the first tranche, the shares and warrants for the second tranche were also approved by shareholders and subsequently issued in accordance with the terms of the fundraising.
The estimated value of the warrants relating to the tranche-one shares was approximately £0.8 million. This amount was recorded as an allocation within a warrant reserve in equity and did not affect the Group’s loss for the period, total equity or cash balances.
On 1 July 2026, shareholders approved the issue of these warrants and they were subsequently issued by the Company.
16. CONTINGENT LIABILITY
Conditional VAT recovery advance
During the period, the Group received approximately £1.0 million as an advance of Chilean input VAT previously incurred on qualifying expenditure in Chile, following approval by the Chilean tax authorities under the applicable early VAT recovery regime.
The advance was received in respect of VAT that had already been paid by the Group on purchases and was previously recognised as a VAT receivable. Under the terms of the approval, the Group is required to make qualifying VAT-able sales within the prescribed period in order to retain the benefit of the early recovery. If CTL does not satisfy the relevant conditions, including the requirement to make qualifying VAT-able sales within the applicable period, the advance will become repayable to the Chilean State. However, it may become enforceable earlier if the Chilean tax authority determines that the Group has failed to comply with the terms of the relevant approval.
The Group expects to make qualifying VAT-able sales within the applicable period and, accordingly, considers that repayment is not probable at the reporting date. No liability has therefore been recognised in respect of the advance.
Although the arrangement requires qualifying VAT-able sales to be made by the end of 2029, the Group may seek an extension of that period from the Chilean authorities should it be appropriate; no extension has been assumed unless and until formally granted.
Management will reassess the accounting and disclosure at each reporting date in light of progress toward commercial production and taxable sales, the continuing validity of the approval, compliance with its conditions, and any relevant communications from the Chilean tax authorities.
17. SUBSEQUENT EVENTS
Important matters and events which have occurred after the period end are outlined in the CEO’s review. In addition, the following are noted:
Completion of fundraising
As announced on 1 July 2026, shareholders approved the conditional elements of the fundraising announced on 4 June 2026, and 55,007,875 new ordinary shares were admitted to trading on AIM on 2 July 2026, generating cash proceeds of approximately £3.0 million before expenses. The shares issued included 4,604,550 subscription shares, valued at approximately £276,000, issued to the Chairman to extinguish deferred fees that remained payable at 30 June 2026; the completion of the fundraising was a non-adjusting event after the reporting period and therefore not included within the cash balance at the period end.
Grant of share options
As announced on 1 July 2026, the Company granted 19,966,431 options over ordinary shares following shareholder approval, comprising 17,466,321 options exercisable at £0.02 per share and 2,500,000 options exercisable at £0.20 per share. The awards were granted after the reporting date and no related share-based payment expense has been recognised in the six months ended 30 June 2026.
Laguna Verde Settlement and Amendment Agreement
As announced on 20 August 2026, the Company and its relevant subsidiaries entered into a Settlement and Amendment Agreement with the vendors of 23 mining licences at Laguna Verde, reducing aggregate cash consideration from US$35.0 million to US$14.0 million, of which US$2.5 million had been paid, and providing for the issue of 6,600,000 ordinary shares in three equal tranches. The agreement is a material non-adjusting event and no adjustment has been made to the deferred-consideration liability recognised at 30 June 2026; the Group is completing its assessment of the accounting effect of the revised arrangements.
Laguna Verde technical results
As announced on 24 July 2026, the Group produced approximately 330 kilograms of high-purity lithium carbonate through processing campaigns using eluate generated at the Laguna Verde direct lithium extraction pilot plant; the results were operational in nature and had no material immediate financial effect on the Group.
**ENDS**
|
For further information contact: |
|
|
CleanTech Lithium PLC |
|
|
Ignacio Mehech/Gordon Stein/Nick Baxter |
Office: +44 (0) 1534 668 321 Mobile: +44 (0) 7494 630 360 Email: info@ctlithium.com
|
|
Beaumont Cornish Limited (Nominated Adviser) Roland Cornish/Asia Szusciak
|
+44 (0) 20 7628 3396 |
|
Fox-Davies Capital Limited (Capital Markets Adviser and Sole Bookrunner) Daniel Fox-Davies
|
+44 (0) 20 3884 8450 |
|
Canaccord Genuity (Broker) James Asensio |
+44 (0) 20 7523 4680 |
Beaumont Cornish Limited ("Beaumont Cornish") is the Company's Nominated Adviser and is authorised and regulated by the FCA. Beaumont Cornish's responsibilities as the Company's Nominated Adviser, including a responsibility to advise and guide the Company on its responsibilities under the AIM Rules for Companies and AIM Rules for Nominated Advisers, are owed solely to the London Stock Exchange. Beaumont Cornish is not acting for and will not be responsible to any other persons for providing protections afforded to customers of Beaumont Cornish nor for advising them in relation to the proposed arrangements described in this announcement or any matter referred to in it.
Notes
CleanTech Lithium (AIM:CTL, Frankfurt:T2N) is an exploration and development company advancing lithium projects in Chile for the clean energy transition. CleanTech Lithium has two key lithium projects in Chile, Laguna Verde and Viento Andino, and exploration stage project in Arenas Blancas (Salar de Atacama), located in the lithium triangle, a leading centre for battery grade lithium production. CleanTech Lithium and the Mining Ministry in Chile have agreed the contractual terms for the Special Lithium Operating Contract ("CEOL") for Laguna Verde, subject to final ratification.
CleanTech Lithium is committed to utilising Direct Lithium Extraction ("DLE") with reinjection of spent brine. Direct Lithium Extraction is a transformative technology which removes lithium from brine with higher recoveries, short development lead times and no extensive evaporation pond construction. For more information, please visit: www.ctlithium.com
**ENDS**
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 9 hours ago Mcbride
- 10 hours ago Next
- 10 hours ago Craneware
- 10 hours ago Solid State
- 10 hours ago Coca-Cola Europacific Partners (DI)