
Interim Results
Summary by AI BETAClose X

18 September 2026
Savannah Resources Plc
(AIM: SAV) (‘Savannah’, or the ‘Company’)
Interim Results for the six months ending 30 June 2026
Savannah Resources Plc, the developer of the Barroso Lithium Project (the 'Project') in Portugal, a 'Strategic Project' under the European Critical Raw Materials Act, is pleased to provide its interim results for the six months ended 30 June 2026.
Major highlights in H1 2026 and the year to date include:
- Grant finance: Savannah was awarded a non-reimbursable Portuguese State grant for up to €110m, including €82.25m for initial development capital expenditure.
- Phase 1 Definitive Feasibility Study completed (‘DFS’): Based on an initial 14 year life producing 183ktpa of 5.5% Li2O spodumene concentrate, second quartile* C1 (US$473/t) and All in Sustaining costs (US$646/t) and an average sales price of US$1,788/t, the Phase 1 DFS reported strong financials. This included US$3.2Bn EBITDA, US$1.9Bn free cash flow, unlevered Post-tax NPV8 US$913m, post-tax IRR of 43% and a Post-tax payback period of 1.9 years.
- First JORC Reserve: The first JORC Probable Ore Reserve was estimated at 20.0Mt at 0.99% Li₂O. The Reserve was estimated using a conservative US$1,200/t SC6 price, supporting Project resilience and future Resource conversion potential.
- Agreements with local community groups: Ten Memorandums of Understanding (MoUs) were signed during the period with influential local and regional organisations.
- Additional Land access: The State granted a second temporary land access award for fieldwork purposes and Savannah signed MoUs and agreements including land access with two local landowner community groups which manage land on the Concession areas. This includes 154 hectares covering Blocks A and C of the C-190 (‘Aldeia’) Mining Concession.
*On Benchmark Mineral Intelligence’s 2030 concentrate cost curves including by-product credits (Lithium Total Cost Model Q2 2026).
Other important milestones and progress made in H1 2026 and the year to date includes:
JORC Resources
- An updated Mineral Resource was estimated at 39.2Mt at 1.05% Li₂O, approximately twice the size of the initial JORC Reserve estimate, providing potential for mine-life and production growth.
Environmental licencing
- RECAPE preparation continued with additional detailed water engineering commissioned to strengthen the RECAPE submission, which is expected to be made in Q4 2026. The regulator then has 50 working days to review the submission and publish its decision (expected Q1 2027).
Fieldwork & Front End Engineering Design (‘FEED’)
- The current geotechnical and hydrogeological focused field programme is proceeding well with two rigs currently operating on site.
- A FEED engineer was appointed in August and a processing plant FEED vendor has been selected with work expected to start shortly.
Infrastructure
- Design work advanced across roads, water systems, tailings, power, telecommunications and community infrastructure during the period.
- As part of the Boticas bypass road’s environmental licencing process, a public consultation was opened in June. Subject to the environmental review continuing on the anticipated timetable, Savannah expects the road’s Declaration of Environmental Impact (‘DIA’) to be issued in Q4 2026.
Land acquisition and access arrangements
- In addition to the second temporary land access awarded for fieldwork purposes and land access agreements with two local community groups, total plots purchased or under deed from private owners is expected to reach 114 by the end of September. Meanwhile preparations continued for compulsory land acquisition or access where voluntary agreements cannot be reached.
Project Finance and offtake partnerships
Additional stock market listing
Project development timetable
Financials
Outlook
CHAIRMAN’S STATEMENT FOR THE SIX MONTHS ENDED 30 JUNE 2026
The first half of 2026 and the September quarter to date have seen Savannah take further significant steps towards delivering the Barroso Lithium Project (the ‘Project’).
The progress made by our dedicated team over the last 6 months reinforce Savannah’s commitment to being a responsible supplier of lithium raw material within Europe.
While a significant programme of work remains before construction can begin, the Project now has a strong technical, economic and commercial foundation. This progress has been made against the backdrop of a robust lithium market and growing recognition of the risks associated with highly concentrated critical raw material supply chains, as geopolitical uncertainty and volatile energy markets continue to dog the global economy.
Shareholders will find further details of the progress made across all the key workstreams in the Operational Review. However, the achievements and themes which particularly stand out to me are:
- the award of a Portuguese State grant of up to €110m;
- completion of an economically robust Phase 1 Definitive Feasibility Study (‘DFS’);
- the delivery of a maiden JORC Ore Reserve; and
- the increasing number and breadth of agreements reached with local stakeholder organisations.
It was also pleasing to note the first capital equipment commitment made for the construction phase for an electrical transformer in May.
Signing of the investment contract for a non-reimbursable Portuguese State grant of up to €110m got the year off to a great start for the Company. Of this amount, 75%, or €82.25m (c.US$95m), is available to contribute towards the Project’s initial development capital expenditure, with the remaining 25% linked to performance milestones during operations. Based on the DFS model, this contribution would reduce the amount of financing required from other sources by around 23% to approximately US$323m. Hence, it represents a very material contribution to the Project’s financing and an equally important State endorsement of its anticipated industrial, economic and regional benefits.
State support was also demonstrated by the swift resolution of issues causing disruption to our fieldwork, with the Portuguese Government referencing the Project’s contribution to national and European critical raw materials policy, investment, employment, population retention and territorial cohesion.
The Project also continues to benefit from its classification as a Strategic Project under the EU Critical Raw Materials Act.
Following much hard work throughout the first half of the year, completion of the Phase 1 DFS in July was a defining milestone. The study established an initial 14-year operation based on a maiden JORC-compliant Probable Ore Reserve of 20.0Mt at an average grade of 0.99% Li₂O, drawn from the Project’s five existing orebodies with an average strip ratio of just 5.2:1 (waste: ore). From this feed, the 1.5Mtpa processing plant is expected to produce an average of approximately 183ktpa of 5.5% Li₂O spodumene concentrate. Based on the DFS assumptions, including highly competitive, second quartile, costs of US$473/t (C1) and US$646/t (all-in sustaining costs) and an average concentrate price of US$1,788/t, the Project generates attractive financials including total post-tax free cash flow of US$1.9bn, post-tax Net Present Value at an 8% discount rate of US$913m, a post-tax Internal Rate of Return of 43.2% and a payback period of 1.9 years.
The DFS also confirms that the Project can combine these appealing economics with the environmental and social requirements expected of a modern European mine development such as a lined dry-stack tailings facility, on-site water storage, treatment and recycling, use of low-carbon electricity, and comprehensive closure and rehabilitation plans. It also includes approximately US$61m for the proposed Boticas bypass road, which is intended to take Project traffic away from local communities while providing a new public connection to the national highway network. Furthermore, the Project is expected to create approximately 300–350 direct jobs during construction, 480–500 on-site positions during operations which will make it one of the biggest employers in the area, as well as significant indirect and induced employment.
There is also meaningful potential beyond the initial Phase 1 development. The updated Mineral Resource totals 39.2Mt at 1.05% Li₂O and is approximately twice the size of the maiden Reserve. In addition, the Project has an Exploration Target of 35–62Mt1 at an estimated grade range of 0.9%–1.2% Li₂O. This provides Savannah with options to evaluate future Reserve growth, mine-life extensions and, potentially, an increase in production after Phase 1 has been established. The DFS design includes selected additional capacity intended to make a later expansion more capital-efficient.
Aside from the DFS other workstreams including the RECAPE (environmental licence) submission, geotechnical drilling, and the Front End Engineering Design work are progressing well.
Project Finance and offtake discussions continue to progress. Following receipt of initial non-binding financing proposals, Savannah is working with a shortlist of potential lenders and has appointed independent technical, environmental, social and legal advisers to support the due diligence process. Discussions also continue in relation to the potential German Government-supported financing associated with our non-binding offtake Heads of Terms with AMG. In parallel, the Company is progressing discussions with prospective counterparties for a second spodumene concentrate offtake agreement and with potential purchasers of the Project’s mineral by-products. Our objective remains to secure a second lithium offtake and receive conditional Project Finance proposals by the end of 2026.
As I say, the progress made in establishing formal relationships with local stakeholders in the first half of the year has been particularly impressive. By the end of June, ten Memorandums of Understanding had been signed in total with a wide range of local organisations which include hundreds of group members from across the area. These agreements clearly demonstrate the growing acceptance and support for the Project among local stakeholders as well as an appreciation of the opportunities it represents for the local area and its people. Savannah values all these agreements which include two with local groups (‘Baldios’), which manage community land in and around the concession area, the regional Secretariat of the Baldios of Trás-os-Montes and Alto Douro, and the body responsible for the parish church of Boticas. Participating groups will be represented on the Project’s Local Advisory and Monitoring Committee, while the Barroso Lithium Foundation is intended to provide a minimum of €500,000 annually once the Project is operating for local social, cultural and development initiatives.
There remains much to do, but Savannah will end 2026 as a materially more advanced company than it entered the year. Our remaining priorities are to achieve conditional Project Finance and secure an additional offtake agreement, submit the RECAPE, complete the current field programme, commence FEED and detailed engineering and announce further agreements with local community groups. Achieving these targets should keep us on target to take FID in early 2027, commence construction later that year and work towards commissioning and first concentrate in late 2028.
The progress achieved during the first half and since the period end reflects a sizeable collective effort. On behalf of the Board, I would like to thank all our staff and consultants for all their hard work and ongoing commitment. I also thank our shareholders, stakeholders and partners for their continuing engagement and support.
We enter the next phase of the Project’s development with a completed DFS, meaningful State support and growing local, commercial and financial engagement. While the work ahead will demand the same discipline and determination shown to date, the foundations are now in place to move the Barroso Lithium Project towards financing, construction and its intended role as an important source of lithium for Europe.
Rick Anthon
Chairman
Date: 17 September 2026
Cautionary statement: The potential quantity and grade of the Exploration Target are conceptual in nature. There has been insufficient exploration work to estimate a Mineral Resource and it is uncertain whether further exploration will result in the definition of a Mineral Resource.
OPERATIONAL REVIEW FOR THE SIX MONTHS ENDED 30 JUNE 2026
Operational Review
Phase 1 Definitive Feasibility Study
During the period, Savannah advanced the final technical, engineering, operating and financial workstreams required to complete the Phase 1 Definitive Feasibility Study (‘DFS’) for the Barroso Lithium Project (the ‘Project’). Following the end of the reporting period, on 15 July 2026, Savannah published the key results from the Phase 1 DFS.
The DFS was prepared with input from a group of international and Portuguese consultants covering geology, mining, metallurgy, process engineering, infrastructure, water management, tailings, environmental matters and financial modelling. The principal international consultants included Sedgman-Minsol, Nagrom, ALS, Ashmore Advisory, Snowden Optiro, Knight Piésold and Model Answer, together with Portuguese specialists including Quadrante, TPF and Portugal’s national civil engineering laboratory, LNEC.
The study confirmed an initial 14-year operation based on a maiden 20.0Mt at 0.99% Li2O JORC Probable Ore Reserve spread across the Project’s five existing orebodies, which will be worked sequentially. Extraction will be performed by conventional open pit mining with an average stripping ratio of 5.2: 1 (waste: ore). Ore will then be hauled by truck the short distances from each pit to a central processing plant incorporating crushing, grinding, Dense Media Separation and flotation circuits operating at a throughput rate of 1.5Mtpa. This will produce an average of 183ktpa of 5.5% Li2O spodumene concentrate (‘SC5.5’) and a suite of by-products which can be sold into local industrial markets.
In addition to safe operation and delivering a strong economic performance, the design outlined in the DFS is focused on minimising the Project’s impact and features a dry-stack and lined Tailings Storage Facility, on-site water sourcing, treatment and recycling and a connection to Portugal’s low-carbon electrical grid power (existing power line in-situ). As part of the Project’s road infrastructure a new, 17km by-pass road, long called for by local stakeholders, will be constructed around the town the Boticas, providing a direct link to the region’s highway network for both Project-related traffic and the public.
The DFS reported an initial capital expenditure (‘capex’) requirement of US$418m which includes contingency, pre-stripping costs, the proposed Boticas bypass road and redundant capacity in certain areas which will allow potential production expansion in the future. The contribution modelled from the non-reimbursable Portuguese State Grant (see below for further details) reduces the initial funding requirement from other sources to approximately US$323m.
Phase 1 DFS Capital Expenditure
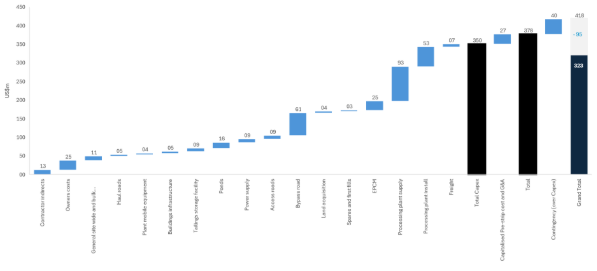
Based on an average SC5.5 price of US$1,788/t (SC6 equivalent of US$1,951/t vs. SC6 spot of US$2,025-2,255/t), the Project generates total EBITDA of US$3,226m, total post-tax free cash flow of US$1,941m, a post-tax Net Present Value (at an 8% discount rate) of US$913m, post-tax IRR of 43.2% and a payback period of just 1.9 years.
Phase 1 DFS Operating costs (‘opex’), US$/t SC5.5 concentrate
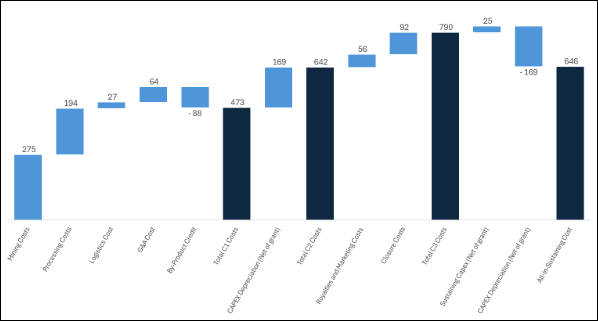
Summary of key Phase 1 DFS operating and capital parameters
Operating parameter |
Unit |
2026 DFS base case |
JORC Resources, including Reserve / average Li₂O grade |
Mt / % Li₂O |
39.1 / 1.05 |
Total JORC Reserve / average Li₂O grade |
Mt / % Li₂O |
20.0 / 0.99 |
Life of mine |
Years |
14 |
Total ore throughput / head grade |
Mt / % Li₂O |
20.6 / 0.98 |
Average annual throughput / head grade |
Mt / % Li₂O |
1.47 / 0.98 |
Average life-of-mine strip ratio |
Waste : ore |
5.2 : 1 |
Plant Li₂O recovery |
% |
69.6 |
Life-of-mine spodumene concentrate production, minimum 5.5% Li₂O |
Mt |
2.56 |
Average annual spodumene concentrate production |
ktpa |
183 |
Life-of-mine by-product sales |
Mt |
8.3 |
Average annual by-product sales |
ktpa |
600 |
Initial CAPEX, including contingencies and pre-strip |
US$m |
418 |
Initial CAPEX, excluding contingencies |
US$m |
377 |
Initial CAPEX, net of Portuguese State Grant and excluding contingencies |
US$m |
283 |
Life-of-mine operating expenditure |
US$m |
1,436 |
Average life-of-mine C1 operating cost1 |
US$/t concentrate (SC5.5) |
473 |
Sustaining capital, net of Portuguese State Grant contribution |
US$m |
65 |
Closure costs |
US$m |
237 |
Average life-of-mine all-in sustaining cost (‘AISC’)2 |
US$/t concentrate (SC5.5) |
646 |
1The C1 cost estimate includes mining, processing, transport, general and administrative and community costs, net of ceramic by-product credits.
2AISC additionally includes royalties, sustaining capital expenditure and closure and rehabilitation costs, net of by-product credits and the operating milestone payments expected under the Portuguese State Grant.
Summary of key Phase 1 DFS economic parameters
Economic parameter |
Unit |
2026 DFS base case |
Average 5.5% Li₂O concentrate price, FOB Portugal |
US$/t concentrate |
1,788 |
Life-of-mine spodumene concentrate revenue |
US$m |
4,579 |
Life-of-mine by-product revenue |
US$m |
224 |
Life-of-mine total revenue |
US$m |
4,804 |
Average annual revenue |
US$m |
389 |
Life-of-mine royalties, representing 3% of revenues |
US$m |
142 |
Life-of-mine EBITDA |
US$m |
3,226 |
Average annual EBITDA |
US$m |
230 |
Life-of-mine corporate and municipal taxes |
US$m |
670 |
Life-of-mine post-tax free cash flow |
US$m |
1,941 |
Average annual post-tax free cash flow |
US$m |
139 |
Pre-tax NPV₈ |
US$m |
1,233 |
Pre-tax IRR |
% |
50.0 |
Pre-tax payback period |
Years |
1.67 |
Post-tax NPV₈ |
US$m |
913 |
Post-tax IRR |
% |
43.2 |
Post-tax payback period |
Years |
1.9 |
Concentrate breakeven price, post-tax NPV₀ = 0 |
US$/t |
747 |
Concentrate breakeven price, post-tax NPV₈ = 0 |
US$/t |
816 |
Sensitivity Analysis
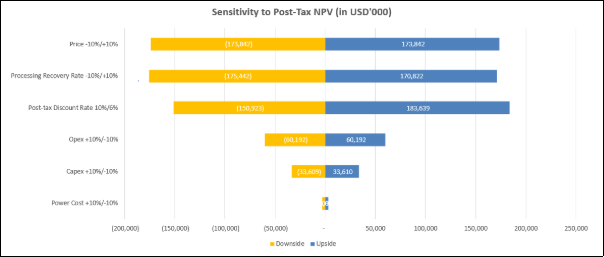
Variations in key inputs to the DFS’ economics show that the largest influence on the post-tax NPV (excluding changes to the discount rate applied) of the Project is the assumed spodumene concentrate price, closely followed by the processing recovery rate. Meanwhile, changes to opex and capex have a far smaller effect on NPV, highlighting the Project’s robustness to any increase in input costs and its leverage to the underlying lithium price.
Phase 1 DFS sensitivity analysis
Upside to Phase 1 DFS
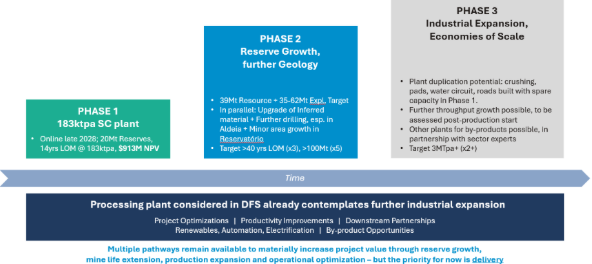
As highlighted above, the DFS design and capex includes optionality in some areas, principally in and around the processing plant, which will reduce the future capital requirements for any subsequent expansion of the Project. Based on the JORC Resources which weren’t converted into Reserves (c.19Mt) and the additional Exploration Target (35-62Mt)2, Savannah believes the opportunity exists to expand the Project’s production rate to twice the currently targeted rate. Hence, the modest additional capex and design elements included in the DFS now will help to support subsequent execution of this option with later capex likely to be a fraction of that required for the initial mine build.
2 Cautionary statement: The potential quantity and grade of the Exploration Target are conceptual in nature. There has been insufficient exploration work to estimate a Mineral Resource and it is uncertain whether further exploration will result in the definition of a Mineral Resource.
Summary of the long term development strategy for the Project
JORC Reserves and Resources
In support of the Phase 1 DFS Mine plan, a principal objective of Savannah’s technical programme was to convert c.75% of the Project’s current Measured and Indicated JORC Mineral Resources into a maiden Ore Reserve.
During the first half of 2026, significant work was undertaken with the Reserve assessment undertaken by Snowden Optiro with an updated Mineral Resource estimate prepared by Ashmore Advisory. Both estimates were prepared in accordance with the JORC Code 2012.
The maiden JORC-compliant Probable Ore Reserve as announced in parallel with the DFS post the reporting period in July, totals 20.0Mt at an average grade of 0.99% Li₂O. The Reserve was estimated using a conservative long-term concentrate price assumption of US$1,200/t for 6% Li₂O concentrate (US$1,100/t SC5.5 equivalent), which is materially below the prevailing spot price, providing a strong degree of resilience in the estimation process. Hence, the opportunity exists to replace and increase the initial Reserve tonnage through subsequent conversion of the remaining c.7Mt Measured and Indicated tonnage (and upgrade and conversion of Inferred Resources) as well as through application of higher price assumptions in future estimations.
JORC-compliant Probable Ore Reserve estimate, July 2026 (0.5% Li2O cut-off)
Deposit |
Tonnes (Mt) |
Li₂O (%) |
Fe₂O₃ (%) |
Aldeia |
1.6 |
1.09 |
0.97 |
Grandão |
11.4 |
0.98 |
0.94 |
NOA |
0.5 |
0.90 |
1.66 |
Pinheiro |
2.1 |
1.02 |
1.03 |
Reservatório |
4.4 |
0.95 |
1.09 |
Total |
20.0 |
0.99 |
1.00 |
Rounding discrepancies may occur.
The associated JORC Mineral Resource was also updated during the period as part of the DFS preparations from the previous September 2025 estimate to include the latest estimate for the Aldeia orebody. The estimate now totals 39.2Mt at 1.05% Li₂O, containing approximately 409,200 tonnes of Li₂O. This includes 8.7Mt in the Measured category, 18.1Mt in the Indicated category and 12.3Mt in the Inferred category. The Mineral Resource Estimate is inclusive of the Ore Reserve and uses a 0.5% Li₂O cut-off.
JORC Mineral Resource Estimate, April 2026 (inclusive of Ore Reserves, 0.5% Li₂O cut-off)
Deposit |
Resource classification |
Tonnes (Mt) |
Li₂O (%) |
Fe₂O₃ (%) |
Contained Li₂O (tonnes) |
Grandão |
Measured |
8.7 |
1.06 |
0.7 |
93,100 |
Indicated |
5.0 |
1.03 |
0.8 |
51,100 | |
Inferred |
4.4 |
1.06 |
0.8 |
46,400 | |
Total |
18.1 |
1.05 |
0.7 |
190,600 | |
Reservatório – within C-100 |
Measured |
– |
– |
– |
– |
Indicated |
5.3 |
0.98 |
0.9 |
52,000 | |
Inferred |
0.8 |
1.10 |
0.9 |
9,200 | |
Total |
6.2 |
0.99 |
0.9 |
61,100 | |
Reservatório – area under application |
Measured |
– |
– |
– |
– |
Indicated |
2.8 |
1.02 |
0.9 |
28,600 | |
Inferred |
3.2 |
0.89 |
0.8 |
28,100 | |
Total |
6.0 |
0.95 |
0.9 |
56,700 | |
Reservatório – total |
Measured |
– |
– |
– |
– |
Indicated |
8.1 |
1.00 |
0.9 |
81,200 | |
Inferred |
4.0 |
0.90 |
0.9 |
36,100 | |
Total |
12.1 |
0.97 |
0.9 |
117,300 | |
Pinheiro |
Measured |
– |
– |
– |
– |
Indicated |
2.6 |
1.11 |
0.7 |
28,500 | |
Inferred |
2.2 |
1.08 |
0.7 |
23,300 | |
Total |
4.8 |
1.09 |
0.7 |
51,800 | |
NOA |
Measured |
– |
– |
– |
– |
Indicated |
0.6 |
1.03 |
0.8 |
6,300 | |
Inferred |
0.1 |
0.95 |
0.5 |
400 | |
Total |
0.7 |
1.03 |
0.8 |
6,700 | |
Aldeia |
Measured |
– |
– |
– |
– |
Indicated |
1.8 |
1.25 |
0.5 |
22,600 | |
Inferred |
1.7 |
1.16 |
0.5 |
19,700 | |
Total |
3.5 |
1.21 |
0.5 |
42,300 | |
All deposits – excluding area under application |
Measured |
8.7 |
1.06 |
0.7 |
93,100 |
Indicated |
15.3 |
1.05 |
0.8 |
160,400 | |
Inferred |
9.1 |
1.09 |
0.7 |
99,000 | |
Total |
33.2 |
1.06 |
0.8 |
352,500 | |
All deposits – grand total |
Measured |
8.7 |
1.06 |
0.7 |
93,100 |
Indicated |
18.1 |
1.05 |
0.8 |
189,000 | |
Inferred |
12.3 |
1.04 |
0.8 |
127,100 | |
Total |
39.2 |
1.05 |
0.8 |
409,200 |
Rounding discrepancies may occur.
As highlighted, the Mineral Resource base provides potential routes to future Reserve growth. These include evaluating the remaining Measured and Indicated Resources not included in the Phase 1 Reserve, upgrading the 12.3Mt of Inferred material through additional drilling and, subject to the relevant concession adjustment, evaluating the 2.8Mt of Indicated Resources in the Reservatório area currently under application. Longer-term potential may also arise from the conversion of Exploration Targets (see below) into Mineral Resources and subsequently into Ore Reserves.
No assurance can be given that all or any of the remaining Mineral Resources or Exploration Targets will be converted into Ore Reserves. However, the scale of the current Resource relative to the maiden Reserve provides Savannah with options to evaluate mine-life and production growth after the Phase 1 development has been established.
Exploration Targets
Savannah maintained the Project’s Exploration Target at 35–62Mt at an estimated grade range of 0.9%–1.2% Li₂O. The Exploration Target is additional to the current Mineral Resource Estimate and covers potential extensions to the existing Mineral Resource-bearing orebodies as well as a number of regional pegmatite prospects identified through drilling, mapping and surface sampling.
The Exploration Target continues to represent a possible longer-term source of Mineral Resource and Reserve growth. Further exploration work is expected to be prioritised once the Project is in production.
Exploration Target summary
Deposit or area |
Lower tonnage range (Mt) |
Upper tonnage range (Mt) |
Li₂O grade range |
Reservatório |
5.0 |
7.0 |
0.9%–1.2% |
Grandão |
4.0 |
8.0 |
1.0%–1.2% |
Pinheiro |
2.0 |
4.0 |
1.0%–1.3% |
Aldeia Block A |
2.0 |
4.0 |
1.0%–1.3% |
NOA |
2.0 |
4.0 |
1.0%–1.2% |
Regional prospects (see details below) |
20.0 |
35.0 |
0.9%–1.2% |
Total Exploration Target |
35.0 |
62.0 |
0.9%–1.2% |
Regional Exploration Target summary
Prospect |
Lower tonnage range (Mt) |
Upper tonnage range (Mt) |
Li₂O grade range |
Altos da Urreta |
2.0 |
3.0 |
0.7%–1.0% |
Altos dos Corticos |
3.0 |
6.0 |
0.9%–1.2% |
Carvalha da Bacora |
3.0 |
6.0 |
0.9%–1.2% |
Aldeia Block B |
7.0 |
10.0 |
0.9%–1.2% |
Piagro Negro |
1.0 |
2.0 |
0.7%–1.0% |
Grandão Northwest |
1.0 |
2.0 |
0.7%–1.1% |
Grandão North |
1.0 |
2.0 |
0.8%–1.1% |
Aldeia Block C |
2.0 |
4.0 |
1.1%–1.5% |
Total regional Exploration Target |
20.0 |
35.0 |
0.9%–1.2% |
Cautionary statement: The potential quantity and grade of the Exploration Target are conceptual in nature. There has been insufficient exploration work to estimate a Mineral Resource and it is uncertain whether further exploration will result in the definition of a Mineral Resource.
Location of the Project’s orebodies and Exploration Targets across the C-100 Concession and Blocks A & B of the C-190 (Aldeia) Concession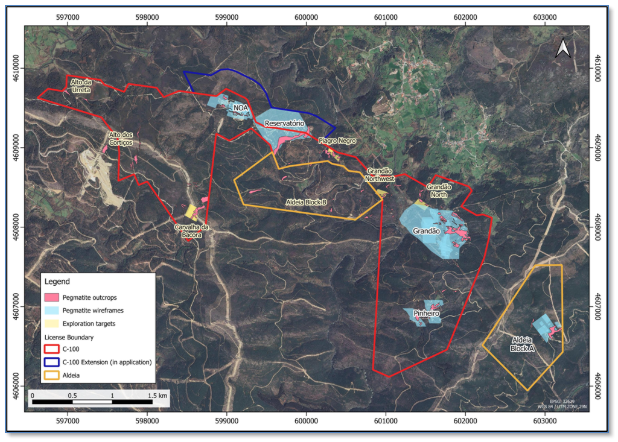
Environmental licencing & monitoring
During the period, Savannah continued to advance the detailed compliance report, or RECAPE, required for the final stage of the Project’s environmental licencing process. The purpose of the RECAPE is to demonstrate that the Project’s detailed design complies with the conditions attached to the favourable Declaration of Environmental Impact (“DIA”) issued in May 2023.
Following engagement with LNEC, the Portuguese governmental body advising the environmental regulator, APA, on water-related infrastructure, Savannah decided to bring forward detailed engineering work on the Project’s water infrastructure to strengthen the RECAPE submission and reduce the risk of subsequent information requests or delays during APA’s review.
Portuguese engineering company COBA was appointed in May 2026 to undertake the additional water infrastructure work. COBA has domestic and international experience in water-related infrastructure and mining projects. Factoring in this additional engineering, Savannah revised the expected RECAPE submission date from July to Q4 2026.
Hence, depending on the precise date of submission, an APA decision would therefore be expected in Q1 2027.
Savannah also maintained the environmental monitoring framework established during earlier phases of Project development. This framework covers parameters including noise, vibration, air and water quality, groundwater and surface-water levels, flora and fauna and other ecological indicators. This regular monitoring helps to establish base lines for the Project’s subsequent phases and helps to identify any issue occurring during the current phase.
Infrastructure
Infrastructure design continued to advance during the reporting period as part of the DFS, environmental licencing and construction-readiness workstreams. The principal infrastructure packages comprise the internal and external road network, water sourcing and storage, the Tailings Storage Facility, the electricity connection and associated telecommunications and community infrastructure.
Geotechnical work required for the proposed processing plant, internal roads and other infrastructure was enabled by the second temporary land access order granted in May. Although work on the affected land was briefly suspended following a legal challenge in June (see Legal section), that work is now underway.
Road network
The Project design includes internal haul roads connecting the proposed mining areas to the processing plant, an approximately 10.9km northern access road and an approximately 16.9km bypass around Boticas town connecting the Project area to the A24 national highway network.
The bypass is designed to reduce the amount of Project-related traffic passing through local communities. It will also be available for public use, providing improved regional connectivity and reducing journey times to services, including medical facilities in Chaves and Vila Real. The Phase 1 DFS includes approximately US$61m of capital expenditure for the bypass.
The bypass road development has its own environmental licencing process independent of the Project’s licence, and the Environmental Impact Assessment submission previously made by Savannah for the road was deemed to be in compliance by the regulator during the period. This triggered the opening in June of a public consultation on the bypass proposal, covering the two principal alignment alternatives passing to the north or south of Boticas town. The public consultation subsequently closed in July. Subject to the environmental review continuing in accordance with the anticipated timetable, Savannah expected the road’s DIA to be issued in early Q4 2026.
Water infrastructure and tailings storage facility
As highlighted, the Project’s design incorporates water storage, treatment and recycling and a lined dry-stack Tailings Storage Facility. These measures are intended to reduce water consumption and wastage. Water storage for firefighting and potential public use also forms part of the wider infrastructure concept.
Water-related engineering was an important focus during the period. As noted above, following discussions with LNEC, Savannah appointed COBA to complete additional detailed engineering work on the Project’s reservoirs and water management infrastructure. This work is being undertaken both to enhance the RECAPE submission and to advance the engineering package ahead of construction.
Power supply
The Project is expected to connect to the Portuguese electricity grid through infrastructure comprising the rerouting of part of an existing overhead line, a switching station and a dedicated Project connection. The use of grid electricity which at present has an average of 80% renewable contribution is an important element of the Project’s intended lower-carbon operating profile.
In May 2026, Savannah ordered a transformer for the Project. This represented the first purchase of capital equipment included within the Project’s initial capital programme. Although limited in value compared with the overall development budget, the early purchase was intended to manage the long delivery periods commonly associated with this type of equipment and reduce the risk of a future schedule delay.
Land acquisition and access arrangements
Savannah continued to apply its established approach to securing the land ownership and access rights required for the Project. This comprises voluntary land purchases and access agreements, temporary access under Portuguese law for defined field activities and, where voluntary arrangements cannot be concluded, the potential use of statutory compulsory acquisition or access procedures available to the holder of the Mining Lease.
The voluntary land acquisition programme continued during the period with two further plots purchased during in the year to date more expected to be purchased in September. As a result total plots purchased or under deed is expected to be 114 by the end of September.
The principal land-access development during the period was the completion of the second temporary access process in May 2026. The approval was published in the Portuguese Government’s official gazette and gave Savannah access for up to one year to land within the C-100 Mining Lease that the Company did not own. This access was required to undertake geotechnical drilling and related work for the processing plant and infrastructure.
Savannah commenced communications with affected stakeholders and landowners regarding the work and the payment of the applicable compensation. Initial activity focused on ground preparation and vegetation clearance, with the mobilisation of drilling equipment to follow.
On 9 June 2026, Savannah was informed that the Covas do Barroso Baldios had filed a precautionary measure against the Portuguese Ministry for the Environment and Energy in relation to the temporary access order. Under Portuguese law, the filing automatically suspended the effect of the order pending the relevant response and judicial consideration. Savannah stopped work on the affected land while continuing permitted activities on land it owned or otherwise had the right to access.
On 29 June, the Portuguese State issued a Reasoned Resolution. This removed the suspension of the order and allowed Savannah to resume the field programme immediately. The State’s response referred to the Project’s national and European strategic significance, its potential contribution to employment, economic development, population retention and territorial cohesion and Savannah’s compliance with the conditions applying to the first temporary easement programme undertaken in 2025.
Savannah also continued to process to prepare for compulsory acquisition or access through a Declaration of Public Utility process where land required for the Project cannot be secured through voluntary agreement. A £2.4m bank guarantee is already in place in relation to anticipated future land purchases under the compulsory purchase plan.
In relation to the C-190 Aldeia Mining Lease, the vendor instructed the relevant authority in December 2025 to transfer the lease to Savannah following completion of the financial and legal steps under the acquisition agreement. Formal registration of the transfer remained outstanding during the period. A separate £2.6m bank guarantee is in place to fund the balance of the acquisition consideration once the transfer is confirmed.
Project development timetable
The principal development milestones reached during the period were the award of the up to €110m non-reimbursable Portuguese State Grant in January, the award of the second temporary land access in May, which has enabled the outstanding infrastructure-related geotechnical fieldwork programme, the first three agreements with key local groups in June, and the progress made on the Phase 1 DFS and maiden JORC Reserve, which were subsequently completed in July as per market guidance. Further important progress was also made with the RECAPE (environmental licence), Project Finance and offtake, Front End Engineer & Design and subsequent additional stakeholder agreements.
In the remainder of the year Savannah expects to deliver on a number of these workstreams which should lead to finalisation of the environmental licence, Project Finance and offtake in Q1 2027 and allow a Final Investment decision to be made.
Project development timeline
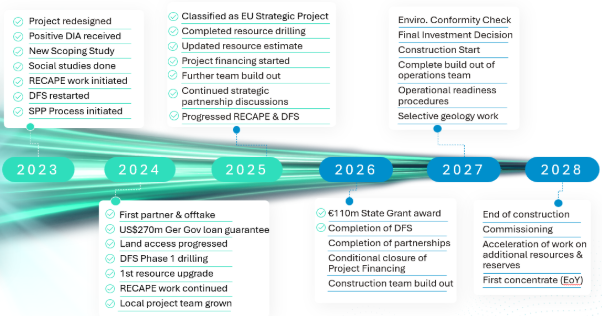
If the current development schedule can be maintained, Savannah expects to begin construction later in 2027 which will then be completed during 2028, allowing for commissioning and first concentrate in late 2028.
Portuguese Government Engagement
Savannah continued its engagement with the Portuguese Government, AICEP and other relevant State agencies during the period. The Project remained supported by AICEP’s Permanent Committee for Investor Support (CPAI), which is intended to facilitate coordination between significant investment projects and the public authorities involved in their development.
The most significant governmental development was the signing of the investment contract with AICEP for a non-reimbursable Portuguese State Grant of up to €110m in January. The Grant is divided into tranches: 75% (€82.5m, c.US$95m) is to be committed to the Project's initial development capex, and the remaining 25% (€27.5m, c.US$32m) linked to performance milestones during the operational phase. Hence, the grant represents a very material potential contribution to the Project’s construction funding and provides formal recognition by the State of the Project’s anticipated industrial, economic and regional importance.
The DFS models a grant contribution equivalent to approximately US$95m towards initial capital expenditure. On that basis, the initial funding requirement including contingencies reduces from US$418m to approximately US$323m.
Government support was also evident in the temporary land access process. The second access order was approved in May and published in the official gazette. Following the precautionary measure filed in June, the Ministry then issued a Reasoned Resolution that restored the effectiveness of the order and allowed the field programme to restart.
In that Resolution, the State described the Project as an instrument for implementing national and European public policy in relation to critical raw materials and strategic autonomy. It also referred to potential benefits from foreign investment, employment, associated value-chain development, regional economic activity and population retention. In addition, the State referred to Savannah’s compliance with the approved work programme and applicable environmental and legal requirements during the earlier temporary access programme.
Engagement also continued with technical and regulatory bodies, including APA, LNEC and the Directorate-General for Energy and Geology. The decision to undertake additional water engineering before RECAPE submission followed this engagement and is intended to provide a more complete technical basis for the environmental regulator’s review.
While the State’s actions do not remove the need for Savannah to complete the remaining licencing, financing, land and technical processes, they do represent clear tangible support for the Project and are relevant to the assessment of its development framework by prospective lenders, commercial partners and other stakeholders.
European Commission engagement
During the period the Company maintained its relationships with the European Commission at a range of levels. Also, the Project continued to benefit from its classification as a ‘Strategic Project’ under the European Critical Raw Materials Act. The classification, announced by the European Commission in March 2025, recognises the Project’s potential contribution to the European Union’s security of supply, strategic autonomy and development of a domestic lithium battery value chain.
Furthermore, the status has helped to catalyse the Company’s financing and commercial discussions and was also referred to by the Portuguese State when responding to the June land access challenge. The State’s Reasoned Resolution linked the Project to European critical raw materials policy and the European Union’s strategic autonomy objectives.
While enhancing and deepening the offer associated with the Critical Raw Materials Act, the Commission also continued to develop complementary policies including the RESourceEU Action Plan. This contains measures directed towards mobilising funding, accelerating Strategic Projects, strengthening supply-chain resilience and facilitating demand aggregation and offtake relationships.
Project Finance, strategic partnerships and offtake partnerships
Savannah continued to advance its financing and commercial workstreams in parallel with completion of the DFS. The objective is to assemble a financing package capable of funding construction while retaining appropriate flexibility over the Company’s ownership and future product sales.
During the reporting period, Savannah and its Project Finance adviser, Cutfield Freeman & Co, continued engagement with potential commercial lenders. The initial market-sounding exercise identified interest from European and international banks and other finance providers with experience in mining and project development. Discussions were supported by the Project’s location in Portugal, its designation as a European Strategic Project, the Portuguese State Grant and the economics subsequently confirmed by the DFS.
Savannah also continued discussions with KfW IPEX-Bank and Euler Hermes in relation to a potential German Government loan guarantee and associated debt facility. This process originated from Savannah’s non-binding offtake Heads of Terms with AMG Critical Materials N.V. and the Project’s previous confirmation as being eligible in principle for a German Government guarantee on a loan of up to US$270m. Any such facility remains subject to due diligence, approvals, final documentation and satisfaction of applicable conditions.
Following receipt of some initial non-binding financing proposals the Company is working with a shortlist of potential lenders and currently is finalizing a set of due diligence reports required by Lender’s with a panel of independent experts (technical, environmental and social, market and legal due diligence reports). The panel includes Palaris for the technical workstream, ERM for the environmental and social workstream and Fastmarkets on the market workstream. Portuguese law firm Morais Leitão Advogados and international law firm Herbert Smith Freehills Kramer were appointed to support the legal aspects of the proposed financing.
Since progress to date and completion of the DFS, Savannah stated that it expected to receive post-due-diligence conditional Project Finance offers by the end of 2026. Debt financing is expected to comprise the largest component of the funding package complemented by the non-reimbursable Portuguese State Grant, equity and potential offtake-related finance.
Spodumene concentrate offtake
Savannah’s existing non-binding offtake Heads of Terms with AMG provide for an initial arrangement covering 45ktpa for five years. Subject to the associated financing solution being secured, the Heads of Terms contemplate an increase up to 90ktpa for ten years. The arrangement leaves Savannah with full ownership of the Project and at least half of the anticipated concentrate production available for sale to other parties.
During 2026, Savannah undertook a market-sounding process for this remaining production. Interest was received from a range of participants across the international lithium value chain, and the Company progressed discussions with a shortlist of potential counterparties. Following the reporting period, Savannah stated that it was working to secure a second potential offtake partnership during the remainder of 2026.
By-product offtake
The DFS anticipates the production of several mineral by-product streams, including Dense Media Separation floats, process tails, a mica concentrate and flotation tails. Potential uses include ceramic, sand and other industrial applications.
Savannah engaged with industrial users, producers and traders and obtained a number of non-binding Letters of Intent (LoIs) indicating potential demand of up to approximately 865ktpa. The DFS assumes average combined by-product sales of 600ktpa at a weighted average price of US$27/t. On the DFS assumptions, these sales contribute approximately US$224m of life-of-mine revenue, equivalent to approximately 5% of total Project revenue.
The proposed sale of by-products would also reduce the quantity of material requiring storage at the Project. Savannah intends to continue negotiations with potential counterparties with the objective of converting selected LoIs into formal sales arrangements. The current Letters of Intent are non-binding and do not guarantee future sales volumes or prices.
Additional stock market listing
Savannah also announced that it was assessing a potential dual listing on a regulated stock market. The review is focused on European markets and established international mining equity markets and is intended to improve access to the Company’s shares, broaden its investor base and support future financing flexibility.
Subject to the outcome of the review and market conditions, a listing is expected to take place in 2027. The Company expects to make further announcements on this in due course as appropriate.
Team expansion and recruitment
Savannah entered 2026 with a broader senior finance, commercial, technical and human resources team following the appointments made during 2025. This expanded capability provided valuable support on key workstreams completed in the year to date and will continue to do so as the Company transitions from feasibility and assessment towards financing, detailed engineering, procurement and construction preparation. The team currently consists of just over 40 members of staff with 85% based full time in Portugal with over 60% based at the Project.
As the Project further advances, so the Company’s staffing requirements will increase with the Phase 1 DFS assuming 300-350 jobs will be created during the construction phase and 480-500 on-site jobs during the operating phase (plus hundreds of indirect and induced jobs). The Company’s latest appointment, made following the period, was Jose Almeida joined as FEED engineer in August, with Project Director and Contracts/Procurement Manager recruitment processes well underway. Ten additional technical roles are expected to be filled by end of 2026.
Stakeholder engagement
Savannah continued to expand its engagement with local communities, associations, businesses, landowners, public authorities and other stakeholders during the period. The Company held public meetings across the Project area and maintained regular communication through formal and informal meetings, local media, social channels, Project publications and participation in community activities.
An important development was the expansion of Savannah’s Memorandums of Understanding (MoU) with local and regional organisations. By June 2026, ten MoUs had been signed. This total included the agreement announced in 2025 with local healthcare provider Terra Quente Saúde Group and a series of further agreements with community organisations.
The first three of the new organisations publicly identified were with recreational associations which operate in the municipalities of Boticas and Ribeira de Pena and collectively represent approximately 250 members, including residents living near the Project.
Following the end of the period further important MoUs and agreements were also announced with two of the local landowner community groups (‘Baldios’) which manage land on the Concession areas. This included an agreement with the Baldios of the villages of Alijó, Canedo and Penalonga within the Canedo Parish relating to 154 hectares of land covering Blocks A and C of the Aldeia Mining Concession. Another MoU was signed with the regional Secretariat of the Baldios of Trás-os-Montes and Alto Douro and with the body responsible for the parish church of Boticas.
The agreements are intended to formalise engagement and create a framework through which these community organisations and others can participate in the Project’s future development and social monitoring. The participating groups are expected to be represented on the Project’s Local Advisory and Monitoring Committee. This body is intended to contribute to the monitoring of social matters and to oversee the allocation of community funding through the Barroso Lithium Foundation.
Once the Project is operating, the Foundation is expected to have a minimum annual budget of €500,000 to support local development, social and cultural initiatives. The proposed arrangements are intended to provide a transparent mechanism for community participation in the identification and oversight of initiatives funded by the Project.
Savannah also increased its engagement with the local business community. In collaboration with Associação Mais Boticas, the Boticas Chamber of Commerce, the Company held a dedicated session attended by approximately 25 local business representatives. Savannah presented the Project’s indicative development timetable and discussed potential construction and operating opportunities in sectors including transport, logistics and services. The Company also reiterated its intention to use local suppliers. Following the event, a group of local businesspeople indicated its intention to create a cooperative venture focused on rehabilitating local housing, with the objective of retaining a greater proportion of Project-related economic activity within the region.
The DFS further developed the framework for managing the Project’s social impacts and benefits. The proposed framework draws on Portuguese requirements, the IFC Performance Standards, the Equator Principles and the United Nations Guiding Principles. Nine integrated management plans are expected to address matters including community benefit sharing, local employment and procurement, cultural heritage, traffic management, agricultural systems and stakeholder engagement.
The Project design does not require the relocation of any community or household. In addition to the Savannah Foundation, the proposed Good Neighbour Plan is intended to address compensation and other arrangements with neighbouring communities.
As highlighted, the DFS estimates that approximately 300–350 direct jobs could be created during construction and approximately 480–500 on-site jobs during operation, in addition to indirect and induced employment. It also identifies wider potential benefits from the Boticas bypass, improvements to local infrastructure, increased procurement and the payment of taxes and royalties.
These initiatives represent measurable progress in establishing formal stakeholder relationships and Savannah intends to continue engaging with stakeholders, responding to reasonable concerns and providing accurate information as the Project progresses.
Legal matters
Project-related legal challenges from groups opposed to its development continued during the period. As in the previous claims brought in relation to the Project, the one claim brought during the period, relating to the second temporary land access order awarded to Savannah, proved to be unsuccessful in its attempt to cause meaningful impact on the Project.
Precautionary Measure brought against the second temporary land access order
As expected by the Company, the Covas do Barroso Baldios filed a precautionary measure on 9 June at the Administrative and Fiscal Court of Mirandela against the Ministry for the Environment and Energy and challenging the second temporary land access order approved in May.
As a consequence of the filing, the legal effect of the access order was automatically suspended before the court had considered the merits of the measure. Savannah complied with the suspension, stopped work on the affected land and secured the relevant work areas and equipment. Work continued on land owned by Savannah or subject to other valid access rights.
Savannah participated as a counter-interested party and began preparing its response with its legal advisers. At the time of the filing, the Company noted that Portuguese courts had issued eight previous decisions in favour of Savannah and/or the Project, including two decisions involving precautionary measures.
On 29 June, the Portuguese State issued a Reasoned Resolution in response to the measure. The Resolution removed the suspension of the temporary access order and allowed Savannah to recommence the field programme immediately.
The Reasoned Resolution addressed the public interest associated with the Project, including its relationship to Portuguese and European critical raw materials policy, employment, investment, regional economic development and population retention. It also referred to Savannah’s compliance with applicable requirements during the previous temporary access programme.
Other legal matters
With the exception of the short suspension of works relating to the challenge to the second temporary land access in June, Savannah was able to continue unencumbered with all its workstreams during the period. The Company will continue to operate in accordance with all relevant laws and guidelines and will robustly defend its legal position if challenged.
Financials
The Company ended the period with a cash position of GBP 17.1m (30 June 2025 GBP 11.9m). The total cash position includes GBP 4.9m pledged against bank guarantees for future land acquisitions (GBP 2.4m) and completion of the Aldeia Mining Concession (GBP 2.5m), leaving GBP 12.2m in cash at hand for ongoing project development (30 June 2025 GBP 9.5m). Following the gross fundraising of GBP 14.6m in 2025, no further funds were raised during the period.
Losses from continued operations during the period increased by 34% versus first half 2025 to GBP 2.0m (30 June 2025: GBP 1.5m) due to higher administrative expenses from increased activity and a reduced foreign exchange gain. In contrast, cash expenditure committed to exploration and development (GBP 2.1m vs. 30 June 2025: GBP 3.2m) fell by 33% due to the lower amount of fieldwork and drilling during the period. As a result, Intangible assets grew by just 5% vs. end of the 2025 to GBP 32.3m within a total asset base of GBP 54.4m (GBP 57.0m at 31 December 2025), slightly reduced by cash spending during the period.
Outlook
The remainder of 2026 is set to be a very busy period for the Company as it looks to make further progress towards FID on the Project next year. With significant milestones ahead and regular news flow Savannah will look to further consolidate its position in European and global lithium supply sector.
In terms of workstreams, on a technical front, the current geotechnical and geological drilling programme will be completed, FEED and detailed engineering will advance, the RECAPE submission will be made (Q4 2026) and the DIA decision on the bypass road is expected. In support of this, further strategic hires will be made to the team to manage ongoing preparations for eventual construction.
On a financing and commercial front, the Company expects to achieve conditional agreement on a Project Finance package, which together with the Portuguese State Grant contribution (c.US$95m) are expected to cover the majority of the Project’s forecast US$418m total initial capex. Securing another offtake partner before the end of the year will also help to give further visibility on the Project’s future revenue streams and support the financing process.
Governmental engagement will also be maintained across all relevant ministries and agencies to ensure that key milestones which require State input are prioritised, while at the European level Savannah will continue to lobby for the importance of local critical raw material projects to be recognised and assess the opportunities presented by the recent raft of policies.
Finally, at the local level, Savannah expects to continue to engage regularly with the authorities, work with local businesses, and to announce further agreements with key local stakeholders groups as it looks to share the benefits that the Project can bring. It will also continue to build its place in local communities through the revitalisation its growing workforce will generate in the area’s towns and villages.
CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME FOR THE SIX MONTHS ENDED 30 JUNE 2026
|
Unaudited Six months to 30 June 2026 |
Unaudited Six months to 30 June 2025 |
Audited Year ended 31 December 2025 | |
|
Notes |
£ |
£ |
£ |
|
|
|
|
|
CONTINUING OPERATIONS |
|
|
|
|
Revenue |
|
- |
- |
- |
Administrative Expenses |
|
(2,166,047) |
(1,793,790) |
(4,413,039) |
Foreign Exchange Gain |
|
32,428 |
165,413 |
231,552 |
OPERATING LOSS |
|
(2,133,619) |
(1,628,377) |
(4,181,487) |
Finance Income |
|
148,900 |
144,530 |
230,050 |
Finance Costs |
|
(5,995) |
(2,320) |
(9,453) |
LOSS FROM CONTINUING OPERATIONS BEFORE TAX |
|
(1,990,714) |
(1,486,167) |
(3,960,890) |
Tax Expense |
|
- |
- |
- |
LOSS FROM CONTINUING OPERATIONS AFTER TAX |
3 |
(1,990,714) |
(1,486,167) |
(3,960,890) |
LOSS ON DISCONTINUED OPERATIONS NET OF TAX |
3 |
(11,100) |
(24,728) |
(101,597) |
LOSS AFTER TAX ATTRIBUTABLE TO EQUITY OWNERS OF THE PARENT |
|
(2,001,814) |
(1,510,895) |
(4,062,487) |
OTHER COMPREHENSIVE INCOME |
|
|
|
|
Items that will not be reclassified to Profit or Loss: |
|
|
|
|
Net Change in Fair Value through Other Comprehensive Income of Equity Investments |
|
2,331 |
(748) |
(383) |
Items that will or may be reclassified to Profit or Loss: |
|
|
|
|
Exchange (Loss) / Gain arising on translation of foreign operations |
|
(437,432) |
674,813 |
1,150,767 |
OTHER COMPREHENSIVE (LOSS) / INCOME FOR THE PERIOD |
|
(435,101) |
674,065 |
1,150,384 |
TOTAL COMPREHENSIVE LOSS FOR THE PERIOD ATTRIBUTABLE TO EQUITY OWNERS OF THE PARENT |
|
(2,436,915) |
(836,830) |
(2,912,103) |
Loss per Share attributable to Equity Owners of the parent expressed in pence per share: |
|
|
|
|
Basic and Diluted |
|
|
|
|
From Operations |
3 |
(0.08) |
(0.07) |
(0.18) |
From Continued Operations |
3 |
(0.08) |
(0.07) |
(0.17) |
From Discontinued Operations |
3 |
(0.00) |
(0.00) |
(0.00) |
The notes form part of this Interim Financial Report.
CONSOLIDATED STATEMENT OF FINANCIAL POSITION AS AT 30 JUNE 2026
|
Unaudited 30 June |
Unaudited 30 June |
Audited 31 December | |
|
|
2026 |
2025 |
2025 |
|
Notes |
£ |
£ |
£ |
ASSETS |
|
|
|
|
NON-CURRENT ASSETS |
|
|
|
|
Intangible Assets |
4 |
32,334,215 |
25,757,380 |
30,740,159 |
Right-of-Use Assets |
5 |
638,460 |
748,902 |
678,597 |
Property, Plant and Equipment |
6 |
2,118,626 |
2,106,607 |
2,137,061 |
Other Receivables |
7 |
460,471 |
436,120 |
465,920 |
Other Non-Current Assets |
8 |
365,323 |
109,633 |
116,579 |
Bank Deposits |
9 |
4,911,767 |
2,356,464 |
4,974,935 |
TOTAL NON-CURRENT ASSETS |
|
40,828,862 |
31,515,106 |
39,113,251 |
CURRENT ASSETS |
|
|
|
|
Equity Instruments at FVTOCI |
10 |
863,376 |
3,583 |
178,446 |
Trade and Other Receivables |
7 |
528,627 |
665,503 |
503,234 |
Bank Deposits |
9 |
7,039 |
507,804 |
6,813 |
Cash and Cash Equivalents |
9 |
12,211,351 |
9,530,835 |
17,170,029 |
TOTAL CURRENT ASSETS |
|
13,610,393 |
10,707,725 |
17,858,522 |
TOTAL ASSETS |
|
54,439,255 |
42,222,831 |
56,971,773 |
EQUITY AND LIABILITIES |
|
|
|
|
SHAREHOLDERS’ EQUITY |
|
|
|
|
Share Capital |
13 |
25,754,497 |
21,727,742 |
25,741,497 |
Share Premium |
|
69,198,903 |
59,215,369 |
69,198,903 |
Merger Reserve |
|
6,683,000 |
6,683,000 |
6,683,000 |
Foreign Currency Reserve |
|
373,855 |
335,333 |
811,287 |
Share Based Payment Reserve |
|
1,557,368 |
663,348 |
1,242,325 |
FVTOCI Reserve |
|
(23,355) |
(49,429) |
(49,064) |
Retained Earnings |
|
(54,705,218) |
(50,166,161) |
(52,717,753) |
TOTAL EQUITY ATTRIBUTABLE TO EQUITY HOLDERS OF THE PARENT |
|
48,839,050 |
38,409,202 |
50,910,195 |
LIABILITIES |
|
|
|
|
NON-CURRENT LIABILITIES |
|
|
|
|
Lease Liabilities |
12 |
492,010 |
610,486 |
541,256 |
Non-Current Trade and Other Payables |
11 |
138,875 |
138,048 |
140,662 |
Non-Current Provisions |
14 |
1,946,528 |
- |
2,190,543 |
TOTAL NON-CURRENT LIABILITIES |
|
2,577,413 |
748,534 |
2,872,461 |
CURRENT LIABILITIES |
|
|
|
|
Lease Liabilities |
12 |
174,849 |
148,991 |
162,908 |
Trade and Other Payables |
11 |
1,852,740 |
2,118,379 |
2,251,808 |
Income Tax (CGT) Provisions |
14 |
509,810 |
460,953 |
501,747 |
Provisions |
14 |
485,393 |
- |
272,654 |
Other Current Liabilities |
|
- |
336,772 |
- |
TOTAL CURRENT LIABILITIES |
|
3,022,792 |
3,065,095 |
3,189,117 |
TOTAL LIABILITIES |
|
5,600,205 |
3,813,629 |
6,061,578 |
TOTAL EQUITY AND LIABILITIES |
|
54,439,255 |
42,222,831 |
56,971,773 |
The Interim Financial Report was approved by the Board of Directors on 17 September 2026 and was signed on its behalf by:
Emanuel Proença
CEO and Director
Company number: 07307107
The notes form part of this Interim Financial Report.
CONSOLIDATED STATEMENT OF CHANGES IN EQUITY FOR THE SIX MONTHS ENDED 30 JUNE 2026
|
Share Capital £
|
Share Premium £
|
Merger Reserve £ |
Foreign Currency Reserve £
|
Share Based Payment Reserve £
|
FVTOCI Reserve £
|
Retained Earnings £
|
Total Equity £
|
21,727,742 |
59,215,369 |
6,683,000 |
(339,480) |
673,738 |
(48,681) |
(48,720,156) |
39,191,532 | |
Loss for the period |
- |
- |
- |
- |
- |
- |
(1,510,895) |
(1,510,895) |
Other Comprehensive Income |
- |
- |
- |
674,813 |
- |
(748) |
- |
674,065 |
Total Comprehensive Income for the period |
- |
- |
- |
674,813 |
- |
(748) |
(1,510,895) |
(836,830) |
Share Based Payment charges |
- |
- |
- |
- |
54,500 |
- |
- |
54,500 |
Lapse of Options |
- |
- |
- |
- |
(64,890) |
- |
64,890 |
- |
At 30 June 2025 |
21,727,742 |
59,215,369 |
6,683,000 |
335,333 |
663,348 |
(49,429) |
(50,166,161) |
38,409,202 |
Loss for the period |
- |
- |
- |
- |
- |
- |
(2,551,592) |
(2,551,592) |
Other Comprehensive Income |
- |
- |
- |
475,954 |
- |
365 |
- |
476,319 |
Total Comprehensive Income for the period |
- |
- |
- |
475,954 |
- |
365 |
(2,551,592) |
(2,075,273) |
Issue of Share Capital (net of expenses) |
4,013,755 |
9,983,534 |
- |
- |
- |
- |
- |
13,997,289 |
Shares based payment issued in lieu |
- |
- |
- |
- |
116,854 |
- |
- |
116,854 |
Share Based Payment charges |
- |
- |
- |
- |
462,123 |
- |
- |
462,123 |
At 31 December 2025 |
25,741,497 |
69,198,903 |
6,683,000 |
811,287 |
1,242,325 |
(49,064) |
(52,717,753) |
50,910,195 |
Loss for the period |
- |
- |
- |
- |
- |
- |
(2,001,814) |
(2,001,814) |
Other Comprehensive Income |
- |
- |
- |
(437,432) |
- |
25,709 |
(23,378) |
(435,101) |
Total Comprehensive Income for the period |
- |
- |
- |
(437,432) |
- |
25,709 |
(2,025,192) |
(2,436,915) |
Issue of Share Capital (net of expenses) |
13,000 |
- |
- |
- |
- |
- |
- |
13,000 |
Share Based Payment charges |
- |
- |
- |
- |
352,770 |
- |
- |
352,770 |
Exercise Share Based Payments |
- |
- |
- |
- |
(37,727) |
- |
37,727 |
- |
At 30 June 2026 |
25,754,497 |
69,198,903 |
6,683,000 |
373,855 |
1,557,368 |
(23,355) |
(54,705,218) |
48,839,050 |
The notes form part of this Interim Financial Report.
CONSOLIDATED CASH FLOW STATEMENT FOR THE SIX MONTHS ENDED 30 JUNE 2026
Notes |
Unaudited Six months to June 2026 £ |
Unaudited Six months to June 2025 £ |
Audited Year ended December 2025 £ | |
Cash Flows used in Operating Activities |
|
|
|
|
Loss for the period |
|
(2,001,814) |
(1,510,895) |
(4,062,487) |
Depreciation and Amortisation charges |
5,6 |
112,491 |
79,773 |
197,930 |
Share based payment charge – Share Options |
|
352,770 |
54,500 |
516,623 |
Shares based payment charge – Shares to be issue in lieu of bonus |
|
- |
- |
116,854 |
Finance Income |
|
(148,900) |
(144,530) |
(230,050) |
Finance Expense |
|
5,995 |
2,320 |
9,453 |
Decrease tax provision |
|
- |
- |
31,953 |
Exchange Losses |
|
(31,152) |
(174,467) |
(239,629) |
Cash Flow used in Operating Activities before changes in Working Capital |
|
(1,710,610) |
(1,693,299) |
(3,659,353) |
(Increase) / Decrease in Trade and Other Receivables |
|
(268,953) |
(71,810) |
1,442 |
Decrease in Trade and Other Payables |
|
(269,287) |
(339,031) |
(269,594) |
Net Cash used in Operating Activities |
|
(2,248,850) |
(2,104,140) |
(3,927,505) |
Cash flow used in Investing Activities |
|
|
|
|
Purchase of Intangible Exploration Assets |
4 |
(2,143,088) |
(3,178,863) |
(5,448,207) |
Purchase of Tangible Fixed Assets |
6 |
(30,430) |
(235,886) |
(316,933) |
Purchase of Equity instruments at FVTOCI |
10 |
(732,203) |
- |
(174,499) |
Disposal of Equity instruments at FVTOCI |
10 |
47,284 |
- |
- |
Set up of Bank Deposits |
|
(2,541,176) |
(20,049) |
(5,250,552) |
Receipt of Bank Deposits |
|
2,541,176 |
- |
3,099,769 |
Interest received |
|
155,617 |
121,744 |
247,616 |
Net Cash used in Investing Activities |
|
(2,702,820) |
(3,313,054) |
(7,842,806) |
Cash Flow (used in) / from Financing Activities |
|
|
|
|
Proceeds from issues of ordinary shares (net of expenses) |
|
13,000 |
- |
13,997,289 |
Principal paid on Lease Liabilities |
|
(52,968) |
(45,494) |
(116,047) |
Interest paid |
|
(5,995) |
(2,320) |
(9,453) |
Net Cash (used in) / from Financing Activities |
|
(45,963) |
(47,814) |
13,871,789 |
(Decrease) / Increase in Cash and Cash Equivalents |
|
(4,997,633) |
(5,465,008) |
2,101,478 |
Cash and Cash Equivalents at beginning of period |
|
17,170,029 |
14,847,387 |
14,847,386 |
Exchange Gain on Cash and Cash Equivalents |
|
38,955 |
148,456 |
221,165 |
Cash and Cash Equivalents at end of period |
|
12,211,351 |
9,530,835 |
17,170,029 |
The notes form part of this Interim Financial Report.
NOTES TO THE CONSOLIDATED INTERIM FINANCIAL REPORT FOR THE SIX MONTHS ENDED 30 JUNE 2026
- BASIS OF PREPARATION
The financial information set out in this report is based on the Consolidated Financial Statements of Savannah Resources Plc (the ‘Company’) and its subsidiary companies (together referred to as the ‘Group’). The Interim Financial Report of the Group for the six months ended 30 June 2026, which is unaudited, was approved by the Board on 17 September 2026. The financial information contained in this interim report does not constitute statutory accounts as defined by s434 of the Companies Act 2006. The statutory accounts for the year ended 31 December 2025 have been filed with the Registrar of Companies. The Auditors’ Report on those accounts was unqualified and did not contain a statement under section 498 (2) or 498 (3) of the Companies Act 2006.
This condensed consolidated interim financial report has been prepared in accordance with IAS 34 Interim Financial Reporting. The financial information set out in this report has been prepared in accordance with the accounting policies set out in the Annual Report and Financial Statements of Savannah Resources Plc for the year ended 31 December 2025. New standards and amendments to IFRS effective as of 1 January 2026 have been reviewed by the Group and there has been no material impact on the financial information set out in this report as a result of these standards and amendments.
The Group Interim Financial Report is presented in Pound Sterling.
Going Concern
In common with many mineral exploration companies, the Group have, in the past raised equity to fund their exploration activities and to date has not earned any revenues from their exploration projects.
The Directors have prepared a cash flow forecast for the period to August 2027. This indicates that the Group can complete the RECAPE work, mine plan, start detailed engineering work and complete Project Finance preparing the Group for Final Investment Decision by Q1 2027 with its current cash balance. To fund the Group’s remaining activities through to August 2027, additional funding would be required during Q1 2027. Additional funding would be required before the end of 2026 to facilitate the Group to proceed with all activities to maintain the Project’s critical path to production.
Additionally, the Directors have evaluated the impact of current geopolitical events, particularly the conflict in Iran, which highlight the urgency with which society needs to accelerate the energy transition based on greater electrification, and it is not expected to have a materially negative impact in the lithium market.
The Directors believe that following the grant of the DIA, the classification of the Project as a ‘Strategic Project’ under the EU Critical Raw Materials Act, the completion of the DFS, and the award of a non-reimbursable grant of up to EUR110m from the Portuguese State (subject to the fulfilment of certain conditions), the Group’s Barroso Lithium Project will be attractive to investors and other offtake partners. Furthermore, AMG is incentivised to deliver a full funding solution for the Project, the Group received a non-binding Letter of Intent in December 2024 from Euler Hermes on behalf of the German Federal Ministry of Economic Affairs for a project finance loan guarantee (up to USD270m), and the Barroso Lithium Project is classified as ‘Strategic Project’ which should benefit it from coordinated support by the Commission, Member States and financial institutions to become operational. The Directors are therefore confident, under suitable market conditions, that funding required to move the Project forwards will be available through options which may include equity, strategic partnership investment, offtake-related finance, loans or grants.
While the Group have been successful in raising equity finance in the past, and while the Directors are confident of raising additional funding when required, their ability to do this is not completely within their control and the lack of a binding agreement means there can be no certainty that the additional funding required by the Group will be secured within the necessary timescale and requires suitable market conditions. These conditions indicate the existence of a material uncertainty which may cast significant doubt about the Group’s ability to continue as a Going Concern and therefore they may be unable to realise their assets and discharge their liabilities in the normal course of business.
The Directors expect that the funding will be forthcoming and therefore the Going Concern basis of preparation is deemed appropriate. The Financial Statements do not include any adjustments that would result if the Group were unable to continue as a Going Concern.
- SEGMENTAL REPORTING
The Group complies with IFRS 8 Operating Segments, which requires operating segments to be identified on the basis of internal reports about components of the Group that are regularly reviewed by the chief operating decision maker, which the Group considers to be the Board of Directors. In the opinion of the Directors, the operations of the Group are comprised of exploration and development in Portugal, and headquarter, corporate and other costs.
Based on the Group’s current stage of development there are no external revenues associated to the segments detailed below. For exploration and development in Portugal the segments are calculated by the summation of the balances in the legal entities which are readily identifiable to each of the segmental activities. Recharges between segments are at cost (although tax related transfer pricing markup is required) and included in each segment below. Intercompany loans are eliminated to zero and not included in each segment below.
|
Portugal Lithium |
HQ, corporate and other |
Elimination |
Total |
|
£ |
£ |
£ |
£ |
Period 1 January 2026 to 30 June 2026 | ||||
Revenue 1 |
690,9252 |
267,798 |
(958,723) |
- |
Administrative Expenses |
(1,146,373) |
(1,019,674) |
- |
(2,166,047) |
Finance Costs |
(5,995) |
- |
- |
(5,995) |
Interest Income |
31,823 |
117,077 |
- |
148,900 |
Share Based Payments |
- |
(352,770) |
- |
(352,770) |
Loss for the period |
(1,149,043) |
(852,771) |
- |
(2,001,814) |
Total Assets |
43,997,501 |
10,441,754 |
- |
54,439,255 |
Total Non-Current Assets |
40,413,554 |
415,308 |
- |
40,828,862 |
Additions to Non-Current Assets |
2,211,248 |
- |
- |
2,211,248 |
Total Current Assets |
3,583,947 |
10,026,446 |
- |
13,610,393 |
Total Liabilities |
(4,631,390) |
(968,815) |
- |
(5,600,205) |
|
Portugal Lithium |
HQ, corporate and other |
Elimination |
Total |
|
£ |
£ |
£ |
£ |
Period 1 July 2025 to 31 December 2025 | ||||
Revenue 1 |
965,2252 |
857,693 |
(1,822,918) |
- |
Administrative Expenses |
(1,725,653) |
(893,596) |
- |
(2,619,249) |
Finance Costs |
(7,133) |
- |
- |
(7,133) |
Interest Income |
11,588 |
73,932 |
- |
85,520 |
Share Based Payments |
- |
(578,977) |
- |
(578,977) |
Loss for the period |
(1,676,621) |
(874,971) |
- |
(2,551,592) |
Total Assets |
41,605,522 |
15,366,251 |
- |
56,971,773 |
Total Non-Current Assets |
38,704,511 |
408,740 |
- |
39,113,251 |
Additions to Non-Current Assets |
7,202,612 |
- |
- |
7,202,612 |
Total Current Assets |
2,901,011 |
14,957,511 |
- |
17,858,522 |
Total Liabilities |
(4,937,442) |
(1,124,136) |
- |
(6,061,578) |
|
Portugal Lithium |
HQ, corporate and other |
Elimination |
Total |
|
|
£ |
£ |
£ |
£ |
|
Period 1 January 2025 to 30 June 2025 | |||||
Revenue 1 |
761,6722 |
291,355 |
(1,053,027) |
- |
|
Administrative Expenses |
(961,059) |
(832,731) |
- |
(1,793,790) |
|
Finance Costs |
(2,320) |
- |
|
(2,320) |
|
Interest Income |
2,283 |
142,247 |
- |
144,530 |
|
Share Based Payments |
- |
(54,500) |
- |
(54,500) |
|
Loss for the period |
(997,846) |
(513,049) |
- |
(1,510,895) |
|
Total Assets |
32,840,586 |
9,382,245 |
- |
42,222,831 |
|
Total Non-Current Assets |
31,114,059 |
401,047 |
- |
31,515,106 |
|
Additions to Non-Current Assets |
6,490,333 |
- |
- |
6,490,333 |
|
Total Current Assets |
1,726,527 |
8,981,198 |
- |
10,707,725 |
|
Total Liabilities |
(2,532,459) |
(1,281,170) |
- |
(3,813,629) |
|
1 Revenues included the intercompany recharges within the Group which are eliminated.
2 Included in the Portugal Lithium segment is GBP 690,925 (31 December 2025: GBP 965,225; 30 June 2025: GBP 761,672) relating to intercompany recharges within this segment and therefore eliminated in Elimination column.
- EARNINGS PER SHARE
Basic earnings per share is calculated by dividing the earnings attributable to the ordinary shareholders by the weighted average number of ordinary shares outstanding during the period.
In accordance with IAS 33 as the Group is reporting a loss for both this and the preceding period the share options are not considered dilutive because the exercise of share options and warrants would have the effect of reducing the loss per share.
Reconciliations are set out below:
|
Unaudited Six months to 30 June 2026 |
Unaudited Six months to 30 June 2025 |
Audited Year ended 31 December 2025 |
Basic and Diluted Loss per Share: |
|
|
|
Losses attributable to Ordinary Shareholders (£): |
|
|
|
Total Loss for the period (£) |
(2,001,814) |
(1,510,895) |
(4,062,487) |
Total Loss for the period from Continuing Operations (£) |
(1,990,714) |
(1,486,167) |
(3,960,890) |
Total Loss for the period from Discontinued Operations (£) 1 |
(11,100) |
(24,728) |
(101,597) |
Weighted average number of shares (number) |
2,574,377,644 |
2,172,774,204 |
2,280,058,258 |
Loss per Share – Total Loss for the period from Operations (£) |
(0.00078) |
(0.00070) |
(0.00178) |
Loss per Share – Total Loss for the period from Continuing Operations (£) |
(0.00077) |
(0.00069) |
(0.00174) |
Loss per Share – Total Loss for the period from Discontinued Operations (£) |
(0.00001) |
(0.00001) |
(0.00004) |
1 Savannah is in the process of exiting its residual interest in Mozambique and finalising administrative work related to the termination of the Consortium Agreement as required by the Mozambique laws. The costs incurred during 2026 and 2025 are related to these activities and are registered under Discontinued Operations.
- INTANGIBLE ASSETS
|
|
|
Exploration and Evaluation Assets £ |
Cost |
|
|
|
At 1 January 2025 |
|
|
21,621,293 |
Additions |
|
|
3,542,638 |
Exchange differences |
|
|
593,449 |
At 30 June 2025 |
|
|
25,757,380 |
Additions |
|
|
4,524,412 |
Exchange difference |
|
|
458,367 |
At 31 December 2025 |
|
|
30,740,159 |
Additions |
|
|
1,948,179 |
Exchange differences |
|
|
(354,123) |
At 30 June 2026 |
|
|
32,334,215 |
Amortisation and Impairment |
|
At 1 January 2025 |
- |
At 30 June 2025 |
- |
At 31 December 2025 |
- |
At 30 June 2026 |
- |
|
|
Net Book Value |
|
At 1 January 2025 |
21,621,293 |
At 30 June 2025 |
25,757,380 |
At 31 December 2025 |
30,740,159 |
At 30 June 2026 |
32,334,215 |
The Exploration and Evaluation Assets referred to in the table above comprise expenditure in relation to exploration licences in Portugal. The Directors consider that for the purposes of assessing impairment, the above exploration and evaluation expenditure is allocated to the Portugal Lithium licences area, representing the Group’s Cash Generating Units (‘CGUs’).
The Directors have reviewed the carrying value of the CGU and have not identified any indicators of impairment for the assets allocated to the licences in Portugal, and therefore there is no impairment charge in 2026 or 2025 for Portugal operations.
The value included in Purchase of Intangible Exploration Assets in the Statement of Cash Flows is affected by the net movements between the Exploration and Evaluation Assets creditors at 31 December 2025 and the value of these at 30 June 2026, hence it does not match with the Additions to Intangible Assets.
- RIGHT-OF-USE ASSETS
|
Motor Vehicles £ |
Buildings £ |
Total £ |
Cost |
|
|
|
At 1 January 2025 |
291,723 |
193,692 |
485,415 |
Additions |
76,299 |
333,855 |
410,154 |
Exchange differences |
10,319 |
8,988 |
19,307 |
At 30 June 2025 |
378,341 |
536,535 |
914,876 |
Additions |
2,036 |
2,643 |
4,679 |
Disposals |
(9,370) |
- |
(9,370) |
Exchange difference |
6,089 |
7,516 |
13,605 |
At 31 December 2025 |
377,096 |
546,694 |
923,790 |
Additions |
49,468 |
9,613 |
59,081 |
Disposals |
(22,477) |
- |
(22,477) |
Exchange differences |
(4,975) |
(7,008) |
(11,983) |
At 30 June 2026 |
399,112 |
549,299 |
948,411 |
Depreciation |
|
|
|
At 1 January 2025 |
103,256 |
4,901 |
108,157 |
Charge for the period |
35,958 |
17,841 |
53,799 |
Exchange differences |
3,720 |
298 |
4,018 |
At 30 June 2025 |
142,934 |
23,040 |
165,974 |
Charge for the period |
38,637 |
46,165 |
84,802 |
Disposals |
(9,370) |
- |
(9,370) |
Exchange difference |
2,637 |
1,150 |
3,787 |
At 31 December 2025 |
174,838 |
70,355 |
245,193 |
Charge for the period |
42,194 |
48,627 |
90,821 |
Disposals |
(22,477) |
- |
(22,477) |
Exchange differences |
(2,357) |
(1,229) |
(3,586) |
At 30 June 2026 |
192,198 |
117,753 |
309,951 |
Net Book Value |
|
|
|
At 1 January 2025 |
188,467 |
188,791 |
377,258 |
At 30 June 2025 |
235,407 |
513,495 |
748,902 |
At 31 December 2025 |
202,258 |
476,339 |
678,597 |
At 30 June 2026 |
206,914 |
431,546 |
638,460 |
The Right-of-Use Assets referred to in the table above comprise agreements signed in relation to the Barroso Lithium Project in Portugal. The additions during the period are related to vehicle lease agreements and long-term property rental agreements signed for Group premises in Portugal.
Details of the Lease Liabilities related to these Right-of-Use Assets are included in Note 11.
- PROPERTY, PLANT AND EQUIPMENT
|
Motor Vehicles £ |
Office Equipment £ |
Fixtures and Fittings £ |
Buildings and Land £ |
Total £ |
Cost |
|
|
|
|
|
At 1 January 2025 |
53,695 |
98,550 |
- |
1,826,166 |
1,978,411 |
Additions |
- |
38,017 |
13,736 |
137,498 |
189,251 |
Exchange differences |
1,793 |
3,579 |
100 |
62,026 |
67,498 |
At 30 June 2025 |
55,488 |
140,146 |
13,836 |
2,025,690 |
2,235,160 |
Additions |
- |
10,433 |
67,256 |
(52,300) |
25,389 |
Exchange difference |
1,051 |
2,540 |
1,403 |
36,270 |
41,264 |
At 31 December 2025 |
56,539 |
153,119 |
82,495 |
2,009,660 |
2,301,813 |
Additions |
- |
14,232 |
- |
16,198 |
30,430 |
Exchange differences |
(718) |
(2,043) |
(1,047) |
(25,629) |
(29,437) |
At 30 June 2026 |
55,821 |
165,308 |
81,448 |
2,000,229 |
2,302,806 |
Depreciation |
|
|
|
|
|
At 1 January 2025 |
53,695 |
45,379 |
- |
- |
99,074 |
Charge for the period |
- |
19,108 |
6,866 |
- |
25,974 |
Exchange differences |
1,793 |
1,660 |
52 |
- |
3,505 |
At 30 June 2025 |
55,488 |
66,147 |
6,918 |
- |
128,553 |
Charge for the period |
- |
25,418 |
7,937 |
- |
33,355 |
Exchange difference |
1,051 |
1,570 |
223 |
- |
2,844 |
At 31 December 2025 |
56,539 |
93,135 |
15,078 |
- |
164,752 |
Charge for the period |
- |
13,939 |
7,731 |
- |
21,670 |
Exchange differences |
(718) |
(1,279) |
(245) |
- |
(2,242) |
At 30 June 2026 |
55,821 |
105,795 |
22,564 |
- |
184,180 |
Net Book Value |
|
|
|
|
|
At 1 January 2025 |
- |
53,171 |
- |
1,826,166 |
1,879,337 |
At 30 June 2025 |
- |
73,999 |
6,918 |
2,025,690 |
2,106,607 |
At 31 December 2025 |
- |
59,984 |
67,417 |
2,009,660 |
2,137,061 |
At 30 June 2026 |
- |
59,513 |
58,884 |
2,000,229 |
2,118,626 |
The additions in land reflect the land acquisition program that Savannah has in place in Portugal to acquire the land required for the future development of the Barroso Lithium project.
The above Property, Plant and Equipment is allocated to the Portugal Lithium operations, representing the Group’s CGUs.
Management has evaluated the existence of impairment indicators of the Property, Plant and Equipment allocated to the licences area together with the impairment review performed for the Exploration and Evaluation Assets, and it has concluded that there are no indicators of impairment, and therefore there is no impairment charge in 2026 or 2025.
The value included in Purchase of Tangible Assets in the Statement of Cash Flows is affected by the net movement between the Tangible Assets creditors at 31 December 2025 and the value of these at 30 June 2026, hence it may not match with the Additions to Tangible Assets.
- TRADE AND OTHER RECEIVABLES
|
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
Non-Current |
|
|
|
|
Other Receivables |
|
460,471 |
436,120 |
465,920 |
Total Non-Current Trade and Other Receivables |
|
460,471 |
436,120 |
465,920 |
|
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
Current |
|
|
|
|
VAT Recoverable |
|
219,217 |
411,965 |
229,356 |
Other Receivables |
|
309,410 |
253,538 |
273,878 |
Total Current Trade and Other Receivables |
|
528,627 |
665,503 |
503,234 |
The amount registered in Non-current Other Receivable is including GBP415,307 (31 December 2025: GBP408,740; 30 June 2025: GBP401,047) related to the Deed of Termination entered into with Rio Tinto in December 2021.
- OTHER NON-CURRENT ASSETS
|
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
Non-Current |
|
|
|
|
Guarantees |
|
316,631 |
62,509 |
96,086 |
Other |
|
48,692 |
47,124 |
20,493 |
Total Other Non-Current Assets |
|
365,323 |
109,633 |
116,579 |
The Non-Current Assets - Guarantees are deposits required by the local mining / environmental authorities in relation to exploration / mining licences and applications thereof (GBP62,883), and deposits required by the Tribunal Judicial da Comarca de Vila Rea (GBP253,748) as collateral, to secure the execution of payments related to the compulsory acquisition of land (see Note 15).
- CASH AND CASH EQUIVALENTS
Cash and Cash Equivalent |
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
|
|
|
|
|
Cash at Bank and in Hand |
|
4,544,384 |
6,072,996 |
2,543,592 |
Short-term Deposits |
|
7,089,141 |
2,847,094 |
14,040,136 |
Restricted Cash |
|
577,826 |
610,745 |
586,301 |
Total Cash and Cash Equivalents |
|
12,211,351 |
9,530,835 |
17,170,029 |
The balance of Cash and Cash Equivalents approximates fair value.
Short-term Deposits include bank deposits and treasury deposits with maturity between 1 and 3 months and are interest bearing.
Restricted Cash includes the Group’s cash balance in Mozambique amounting to GBP577,826 (31 December 2025: GBP586,301; 30 June 2025: GBP610,745) which is restricted for use in Mozambique until the Group and the Mozambican Tax Authority resolve the potential tax treatment or otherwise of the Deed of Termination from 2021. These funds are being used to settle the necessary costs to maintain the Mozambique subsidiary in good order.
Bank Deposits |
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
Non-Current |
|
|
|
|
Bank Deposits |
|
4,911,767 |
2,356,464 |
4,974,935 |
Total Bank Deposits |
|
4,911,767 |
2,356,464 |
4,974,935 |
|
|
|
|
|
Current |
|
|
|
|
Bank Deposits |
|
7,039 |
507,804 |
6,813 |
Total Bank Deposits |
|
7,039 |
507,804 |
6,813 |
Non-Current Bank Deposits includes three Bank deposits amounting to GBP4,911,767 (31 December 2025: GBP4,974,935 and 30 June 2025: GBP2,356,464). Two deposits amounting to GBP2,370,592 are pledged against bank guarantees related to the compulsory acquisition process for relevant land for the Project that the Group does not own (see Note 15). One deposit amounting to GBP2,541,176 is pledged against bank guarantee related to the acquisition of the Aldeia licence (see Note 14). These bank guarantees are expected to be reduced more than 12 months after the reporting date and therefore the bank deposits are classified as Non-Current Bank Deposits. These deposits are interest bearing.
Current Bank Deposits include bank and treasury deposits with maturity between 3 and 12 months in duration and are interest bearing.
- EQUITY INSTRUMENTS AT FVTOCI
Current |
Shares in Equity Investments at FVTOCI £ |
At 1 January 2025 |
4,331 |
Change in market value of investment |
(748) |
At 30 June 2025 |
3,583 |
Additions |
174,324 |
Change in market value of investment |
539 |
At 31 December 2025 |
178,446 |
Additions |
732,203 |
Disposals |
(47,284) |
Change in market value of investment |
2,233 |
Foreign exchange movements |
(2,222) |
At 30 June 2026 |
863,376 |
Equity Investments are designated as Fair Value Through Other Comprehensive Income (FVTOCI).
Additions during the period relate to the acquisition of shares in a market fund, which is held as a liquid investment and classified as a financial asset at fair value through other comprehensive income (FVTOCI).
The fair value of the shares held by the Company is the quoted value at the reporting date. The fair value hierarchy in 2026 and 2025 for these shares is Level 1 as the valuation is based wholly on quoted prices.
- TRADE AND OTHER PAYABLES
|
|
Unaudited 30 June 2026 |
Unaudited 30 June 2025 |
Audited 31 December 2025 |
|
|
£ |
£ |
£ |
Non-Current |
|
|
|
|
Trade Payables |
|
138,875 |
138,048 |
140,662 |
Total Non-Current Trade and Other Payables |
|
138,875 |
138,048 |
140,662 |
Current |
|
|
|
|
Trade Payables |
|
602,015 |
988,906 |
560,022 |
Accruals |
|
1,076,297 |
892,744 |
1,132,938 |
Other Payables |
|
174,428 |
236,729 |
558,848 |
Total Current Trade and Other Payables |
|
1,852,740 |
2,118,379 |
2,251,808 |
- LEASE LIABILITIES
|
Lease liabilities £ |
At 1 January 2025 |
379,061 |
Additions |
413,251 |
Lease payments |
(45,494) |
Foreign exchange movements |
12,659 |
At 30 June 2025 |
759,477 |
Additions |
7,824 |
Lease payments |
(70,553) |
Foreign exchange movements |
7,416 |
At 31 December 2025 |
704,164 |
Additions |
24,604 |
Lease payments |
(52,968) |
Foreign exchange movements |
(8,941) |
At 30 June 2026 |
666,859 |
The additions during the year are related to vehicle lease agreements and long-term property rental agreements signed for Group premises in Portugal.
Details of the Right-of-Use Assets related to these lease liabilities are included in Note 5.
The maturity of the leases is as follows:
|
|
Unaudited 30 June 2026 £ |
Unaudited 30 June 2025 £ |
Audited 31 December 2025 £ |
Less than 1 year |
|
174,849 |
148,991 |
162,908 |
Between 1 year and 2 years |
|
169,117 |
161,420 |
160,653 |
Between 2 years and 3 years |
|
143,701 |
152,464 |
146,683 |
Between 3 years and 4 years |
|
98,001 |
128,731 |
113,083 |
Between 4 years and 5 years |
|
14,938 |
87,316 |
47,616 |
More than 5 years |
|
66,253 |
80,555 |
73,221 |
Total Lease Liabilities |
|
666,859 |
759,477 |
704,164 |
The Right-of-Use Assets and related Lease Liabilities are for the lease of motor vehicles and business premises in Portugal.
- SHARE CAPITAL
|
Six months to 30 June 2026
|
Six months to 30 June 2025
|
Six months to 31 December 2025 | |||
|
£0.01 ordinary shares number |
£ |
£0.01 ordinary shares number |
£ |
£0.01 ordinary shares number |
£ |
Allotted, issued and fully paid |
|
|
|
|
|
|
At beginning of period |
2,574,149,699 |
25,741,497 |
2,172,774,204 |
21,727,742 |
2,172,774,204 |
21,727,742 |
Issued during the period: |
|
|
|
|
|
|
Share placement |
- |
- |
- |
- |
401,375,4952 |
4,013,755 |
Exercise of Share Options |
1,300,0001 |
13,000 |
- |
- |
- |
- |
At end of period |
2,575,449,699 |
25,754,497 |
2,172,774,204 |
21,727,742 |
2,574,149,699 |
25,741,497 |
1 In respect of the exercise of 1,300,000 share options by employees the proceeds were GBP13,000 all recorded in Share capital.
2 In respect of the Share placements in 2025 the net proceeds were GBP13,997,289 of which GBP9,983,534 has been recorded in Share Premium. The gross proceeds were GBP14,577,699 and the costs of the Share placements GBP580,410.
The par value of the Company’s shares is GBP 0.01.
- GROUP PROVISIONS
|
Unaudited 30 June 2026 £ |
Unaudited 30 June 2025 £ |
Audited 31 December 2025 £ |
|
Non-Current: |
|
|
|
|
Provision Aldeia Mining Lease |
1,946,528 |
- |
2,190,543 |
|
Total Non-Current Provisions |
1,946,528 |
- |
2,190,543 |
|
|
|
|
|
|
Current: |
|
|
|
|
Provision Aldeia Mining Lease |
485,393 |
- |
272,654 |
|
Tax provision |
509,810 |
460,953 |
501,747 |
|
Total Current provisions |
995,203 |
460,953 |
774,401 |
|
The movement of the provisions during the period is as follows:
|
|
Provision Aldeia Mining Lease |
|
Tax provision | |
|
|
Non-Current £ |
Current £ |
|
Current £ |
|
|
|
|
|
|
At 1 January 2025 |
|
- |
- |
|
504,272 |
Increase provision |
|
|
|
|
- |
Decrease provision |
|
- |
- |
|
- |
Foreign exchange movements |
|
- |
- |
|
(43,319) |
At 30 June 2025 |
|
- |
- |
|
460,953 |
Increase provision |
|
2,190,543 |
272,654 |
|
31,953 |
Decrease provision |
|
- |
- |
|
- |
Foreign exchange movements |
|
- |
- |
|
8,841 |
At 31 December 2025 |
|
2,190,543 |
272,654 |
|
501,747 |
Increase provision |
|
- |
- |
|
- |
Reclassification to current provision |
|
(216,202) |
216,202 |
|
- |
Foreign exchange movements |
|
(27,813) |
(3,463) |
|
8,063 |
At 30 June 2026 |
|
1,946,528 |
485,393 |
|
509,810 |
Provision acquisition Aldeia Mining Lease:
In June 2019 the Company purchased the right to acquire a Mining Lease Application for lithium, feldspar and quartz from private Portuguese company, Aldeia & Irmão, S.A. (“Aldeia”), once the Mining Lease had been granted. The terms of the agreement were modified in June 2024, primarily to extend the date, by which the Mining Licence could be issued and transferred, to September 2026 to ensure that the Company’s right to acquire was continued. That right will remain in place unless Aldeia decides to seek a termination of the longstanding agreement and the Group is further protected because Aldeia submitted an irrevocable transfer request to DGEG in December 2025. Based on the terms of the agreement and its modification the Group reported a contingency amounting to Eur3,100,000 (~GBP2,568,000) as at 31 December 2024.
In December 2024, Aldeia notified the Company that the Mining Lease Application had been granted by the DGEG. The Company exercised its option to defer the transfer of the Mining Lease to an entity within the Group for 12 months by paying EUR 150,000 in December 2024 and EUR 150,000 in May 2025. These amounts are deducted from the acquisition price.
In December 2025, the Company requested that Aldeia instruct the DGEG to transfer the Mining Lease to Savannah Lithium Unipessoal Limitada. The transfer process is currently underway and is expected to be completed during 2026.
Pursuant to the terms of the Acquisition, the purchase price for the Lease, after adjustment for the deferral option payments, is EUR2,950,000 (~GBP2,540,000). A bank guarantee has been established to secure this liability.
The agreed payment schedule comprises an initial payment of EUR55,000 (~GBP47,000) upon completion of the transfer of the Lease to Savannah, with the remaining balance payable in 71 monthly instalments.
As the exact date of transfer remains uncertain, management has assumed completion in H2 2026 for the purpose of measuring the liability. Accordingly, EUR563,484 (GBP485,393) (31 December 2025: GBP272,654; 30 June 2025 nil) has been recognised within current liabilities, and the present value of the remaining balance of EUR2,259,685 (GBP1,946,528) (31 December 2025: GBP2,190,543; 30 June 2025 nil) has been recognised as non-current liabilities.
Reductions in the bank guarantee are expected to be made in six-monthly tranches, reflecting cumulative payments made under the agreed instalment schedule.
Tax Provision:
During H1 2025 Savannah initiated the process for the compulsory acquisition of relevant land for the Project area that it does not own. In February 2025, Savannah provided two bank guarantees in favour of the Tribunal Judicial da Comarca de Vila Real, amounting to EUR2,052,668 (~GBP1,768,000) and EUR699,304 (~GBP602,000), to secure the execution of payments related to the compulsory acquisition process (see Note 9). In April 2026, Savannah provided a bank guarantee in favour of the Tribunal Judicial da Comarca de Vila Real, amounting to EUR294,571 (~GBP254,000), to secure the execution of payments related to the compulsory acquisition process (see Note 8). These bank guarantees will remain valid until the commitments arising from the compulsory acquisition process are extinguished, and will be reduced as commitments are fulfilled.
- EVENTS AFTER THE REPORTING DATE
In July 2026 the Group announced the key findings from the Barroso Lithium Project's Phase 1 DFS. The study established an initial 14-year operation based on a maiden JORC-compliant Probable Ore Reserve of 20.0Mt at an average grade of 0.99% Li₂O. The 1.5Mtpa processing plant is expected to produce an average of approximately 183ktpa of 5.5% Li₂O spodumene concentrate. Based on the DFS assumptions, the Project generates total post-tax free cash flow of US$1.9bn, post-tax Net Present Value at an 8% discount rate of US$913m, post-tax IRR of 43.2% and a payback period of 1.9 years.
Savannah – Enabling Europe’s energy transition.
**ENDS**

Follow Savannah Resources on LinkedIn
For further information please visit www.savannahresources.com or contact:
Savannah Resources PLC Emanuel Proença, CEO Asa Bridle, Investor Relations António Neves Costa, Media Relations
|
Tel: +351 963 850 959 Tel: +44 207 117 2489 Tel: +351 962 678 912 |
SP Angel Corporate Finance LLP (Nominated Advisor & Joint Broker) David Hignell / Charlie Bouverat (Corporate Finance) Grant Barker /Abigail Wayne (Sales & Broking)
|
Tel: +44 20 3470 0470
|
Canaccord Genuity Limited (Joint Broker) James Asensio / Rory Blundell / Charlie Hammond (Corporate Broking) Ben Knott (Sales)
|
Tel: +44 20 7523 8000
|
About Savannah
Savannah Resources is a mineral resource development company and the sole owner of the Barroso Lithium Project (the 'Project') in northern Portugal. The Project is the largest battery grade spodumene lithium resource outlined to date in Europe and was classified as a 'Strategic Project' by the European Commission under the Critical Raw Materials Act in March 2025 and was approved for a Portuguese State development Grant of up to €110m in January 2026.
Through the Project, Savannah will help Portugal to play an important role in providing a long-term, locally sourced, lithium raw material supply for Europe's lithium battery value chain. Once in operation the Project will produce enough lithium (contained in c.183,000tpa of spodumene concentrate) for approximately half a million vehicle battery packs per year and hence make a significant contribution towards the European Commission's Critical Raw Material Act goal of a minimum 10% of European endogenous lithium production from 2030.
Savannah is focused on the responsible development and operation of the Barroso Lithium Project so that its impact on the environment is minimised and the socio-economic benefits that it can bring to all its stakeholders are maximised.
The Company is listed and regulated on the AIM Market of the London Stock Exchange and trades under the ticker "SAV".
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 1 hour ago Triad Group
- 1 hour ago Trustpilot Group
- 1 hour ago Oxford Biodynamics
- 1 hour ago TMT Investments
- 15 hours ago Cerillion