
P2634 interest to double and Finn resource update
Summary by AI BETAClose X

THE INFORMATION CONTAINED WITHIN THIS ANNOUNCEMENT IS DEEMED BY THE COMPANY TO CONSTITUTE INSIDE INFORMATION AS STIPULATED UNDER THE MARKET ABUSE REGULATION (EU) NO. 596/2014 AS IT FORMS PART OF UK DOMESTIC LAW PURSUANT TO THE EUROPEAN UNION (WITHDRAWAL) ACT 2018, AS AMENDED. UPON THE PUBLICATION OF THIS ANNOUNCEMENT VIA A REGULATORY INFORMATION SERVICE, THIS INFORMATION IS CONSIDERED TO BE IN THE PUBLIC DOMAIN.
16 November 2026
Orcadian Energy plc
(“Orcadian” or the “Company”)
P2634 interest to double and Finn resource update
Orcadian is pleased to announce that its interest in the P2634 (Finn) licence is expected to double from 50% to 100% on the withdrawal of Serica Energy Norte Ltd, a wholly owned subsidiary of Serica Energy plc (together, “Serica”), from the licence, subject to the consent of the North Sea Transition Authority (“NSTA”).
Following final completion of the Phase A work programme, Serica has informed Orcadian and the NSTA that it wishes to withdraw from the licence. Orcadian has indicated to the NSTA that it wishes to remain on the licence and intends to seek an extension to the term of Phase A which currently expires at the end of February 2027.
The Finn discovery in the Outer Moray Firth of the UKCS has remained undeveloped for over 50 years despite consistently being mapped as having in the order of a billion barrels of oil in place. The discovery lies close to the Claymore and Piper fields, but at a much shallower horizon.
Orcadian has recently completed, on behalf of the P2634 Joint Venture (“JV”), a detailed reservoir engineering evaluation of alternative development schemes which could work on Finn. This work identified that the best development strategy was a warm (140ºF), low salinity, polymer flood with inflow control valves using the produced fluid temperature as a trigger to shut off swept zones between the alternating producer and injector pairs. Orcadian estimates that such an approach can achieve a field wide recovery factor of 42.1%.
This work also included an evaluation of a discovery made by well 15/16d-27 in the same Beauly Member reservoir. Drawing from Irish mythology, Orcadian has renamed the former Fynn Beauly discovery “Finn”, the Fynn-T82 discovery as “Benandonner”, and the 15/16d-27 discovery as “Oonagh”. The latter lies outside the P2634 licence.
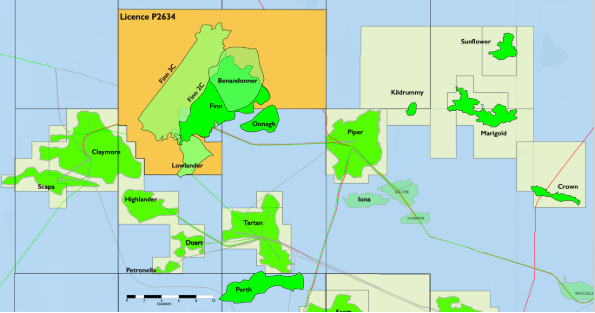
As part of the work programme just completed, the JV revised its P50 oil-in-place estimate for the Finn discovery to 1,029 MMbbl, 75% of which is estimated to lie within the confines of P2634. Orcadian’s central estimate of the field-wide recovery factor is 42.1%. This implies that the gross 2C contingent resources associated with the Finn field are 433 MMbbl; resources on the licence, are 325 MMbbl, which is a 26% uplift on the previous on-licence estimate of 257 MMbbl. The Lowlander discovery contains a further 23.4[1] MMbbl of 2C resources. On Serica’s withdrawal, Orcadian’s interest in Lowlander has also doubled, for a total resource on licence P2634 of 348 MMbbl attributable to Orcadian’s expected 100% interest in P2634.
These resource estimates are gross unrisked best estimate (2C) contingent resources (SPE-PRMS, effective 1 January 2026).
Back in 1977, when BP was evaluating the crude produced from Finn, the laboratory report stated that the atmospheric residue left after heating the oil to greater than 371ºC accounted for some 88.5% by weight of the crude but was too aromatic to be of much commercial use. At the time, this conclusion would have damned any development project.
However, as technology advances, market demands change and there is now a significant demand for premium-quality needle coke to produce synthetic graphite for lithium-ion battery anodes. Quoting Digital Refining[2] from 2022: a highly aromatic feedstock must be used to produce premium-quality, readily graphitisable needle coke and that recent uses of needle coke include the production of synthetic graphite for lithium-ion battery anode material in electric vehicles.
Orcadian believes that confirmation of the suitability of Finn oil as a feedstock for needle cokers is the key to unlocking a Finn development project; and intends to seek a partner to fund the drilling of an appraisal well on Finn to get sufficient oil so that multiple pilot test programmes can be undertaken with a range of refiners to secure the best offtake partner for a development project.
The Company will provide further updates in due course.
Steve Brown, Orcadian CEO, said:
“We have worked diligently with Serica to complete the Phase A work programme and found Serica to be a great partner to work with. Serica has a wide range of development opportunities and while we are genuinely sad to see them go, we are also delighted to have the opportunity to double our equity interest in the licence and to have lost the commercial friction that an obligation to make a substantial contingent consideration payment to a third-party entails (Serica had agreed to pay Parkmead Group £0.8/bbl for the 2P reserves contained within a Fynn Beauly FDP, capped at £90m[3], Orcadian has no contingent liability to Parkmead).
“In addition, once Orcadian holds a 100% interest in the licence it ought to be possible to secure a farm-out on more favourable terms than before.
“We believe that Finn is much more than a half century old petroleum curiosity. Finn is a discovery whose time has come, polymer flooding technology has advanced to the point where a polymer flood is now a routine scheme for oils far more viscous than Finn, and the implementation of polymer flooding offshore has been proven by Chevron, and subsequently Ithaca, on Captain.
“By warming the fluid, we can dramatically improve recovery and by adopting a low salinity injectant we can significantly reduce polymer cost and improve polymer effectiveness; the combination of this approach with the potential to improve production performance using temperature-controlled inflow control valves, or outflow control valves on the injectors, sets the foundation for a viable development scheme for Finn. We believe the key to underwriting a development project will be securing the right offtake partner.”
For further information on the Company please visit the Company’s website: https://orcadian.energy
Contact:
|
Orcadian Energy plc |
+ 44 20 7920 3150 |
|
Steve Brown, CEO Alan Hume, CFO |
|
|
Zeus (Nomad and Joint Broker) |
+44 20 3829 5000 |
|
Darshan Patel / Alex Slater (Investment Banking) Simon Johnson (Corporate Broking) |
|
|
Albr (Joint Broker) |
+44 207 399 9425 |
|
Colin Rowbury / Jon Belliss |
|
Qualified Person's Statement
Pursuant to the requirements of the AIM Rules and in particular, the AIM Note for Mining and Oil and Gas Companies, Maurice Bamford has reviewed and approved the technical information and resource reporting contained in this announcement. The resource estimates in this announcement have been prepared in accordance with the 2018 Petroleum Resources Management System (“PRMS”) and are stated as at 1 January 2026. They are the Company’s own estimates and have not been independently verified.
Maurice has 37 years' experience in the oil & gas industry and 3 years in academia. He holds a BSc in Geology from Queens University Belfast and a PhD in Geology from the National University of Ireland. Maurice is a Fellow of the Geological Society, London, and a member of the Geoscience Energy Society of Great Britain. He is Exploration and Geoscience Manager at Orcadian Energy.
Forward-Looking Statements
This announcement contains forward-looking statements that are based on current expectations or beliefs, as well as assumptions about future events. These forward-looking statements can be identified by the use of forward-looking terminology, including the terms “believes”, “intends”, “may”, “will”, “plans”, “expects” or, in each case, their negative or other variations or comparable terminology. These forward-looking statements include all matters that are not historical facts and reflect the Directors’ current view with respect to future events. They are subject to risks, uncertainties and assumptions, including in relation to regulatory and governmental approvals,the identification of suitable counterparties, and prevailing economic and market conditions, that could cause actual results to differ materially from those expressed or implied. No statement in this announcement is intended to be, or should be construed as, a profit forecast or estimate, or a valuation of the Company or any of its assets. The forward-looking statements speak only as at the date of this announcement and, save as required by the AIM Rules for Companies, the Market Abuse Regulation or other applicable law, the Company undertakes no obligation to update or revise them.
About Orcadian Energy
Orcadian is a North Sea focused, low-emissions, oil and gas exploration and development company. Orcadian may be a small operator, but it is also nimble, and the Directors believe it has grasped opportunities that have eluded some of the much bigger companies. As we strike a balance between Net Zero and a sustainable energy supply, Orcadian intends to play its part to minimise the cost of Net Zero and to deliver reliable energy to the UK.
Viscous oil
As part of its viscous oil strategy Orcadian has an 18.75% carried interest in the Pilot development project, Pilot was discovered by PetroFina in 1989 and has been well appraised. The field has excellent quality reservoir and has contingent resources of 79 MMbbl of a viscous oil ranging in gravity from 17º API in the South of the reservoir to 12º API in the North. In planning the Pilot development, Orcadian has selected polymer flooding and wind power to transform the production of viscous oil into a cleaner and greener process. Polymer significantly reduces fluid handling requirements and hence energy consumption as well as boosting recovery. Ithaca Energy, operator of the Captain field in the Inner Moray Firth, has enjoyed consistent success in applying polymer flood to the highly analogous Captain field. Following the recent farm-down of Pilot, the project is now under the stewardship of Ping Petroleum UK PLC (“Ping”) and is intended to be amongst the lowest carbon emitting oil production facilities in the world.
Ping is progressing a low-emissions, phased, field development plan for Pilot based upon a polymer flood of the reservoir, a Floating Production Storage and Offloading vessel (FPSO) and provision of power from a floating wind turbine or a local wind farm.
Orcadian has an 18.75% fully carried interest in licence P2244 (block 21/27a) and a 100% interest in licence P2482 (blocks 28/2a and 28/3a). Ping is operator of P2244 and the Pilot development project. P2482 covers the Elke and Narwhal discoveries which contain 54 MMbbl of contingent resources.
The Finn licence was awarded in the 33rd round, P2634 contains a very substantial heavy oil discovery. About 75% of the resource on a best technical case is estimated to lie within the area of the P2634 licence. Once Serica completes its withdrawal, and subject to NSTA consent, Orcadian will have a 100% working interest in the Finn licence which covers blocks 14/15a, 14/20d and 15/11a. Gross 2C contingent resources of 325 MMbbl are associated with Finn, the Lowlander discovery contains a further 23.4 MMbbl, for a total resource of 348 MMbbl.
Gas
Orcadian was awarded two gas licences in the 33rd Round. The Mid-North Sea High licence, P2650, contains shallow gas prospects and leads. Orcadian applied in partnership with Triangle Energy, then an Australian listed energy company. Orcadian is licence administrator and holds 50% of the licence, and will hold 100% on completion of the proposed withdrawal of Triangle Energy (UK) Pty Ltd from the licence. The Mid-North Sea High licence covers blocks 29/16, 29/17, 29/18, 29/19, 29/21, 29/22, 29/23, 29/27 and 29/28.
The SNS licence, P2680 100% Orcadian, contains the Earlham discovery, a low-calorie gas discovery with 114 bcf of methane resources on a P50 basis, the Clover prospect which has P50 prospective resources of 153 bcf, and the decommissioned Orwell field which has redevelopment potential with 31 bcf resources on a P50 basis, alongside a number of smaller prospects. Orcadian has established Earlham Gigagrid to provide a vehicle for investment in the Earlham development, power station and datacentre potential, without diluting Orcadian’s shareholders’ interests in its viscous oil and Central North Sea projects.
Resource Estimates
These resource estimates below are gross unrisked best estimate (2U) prospective and (2C) contingent resources (SPE-PRMS, effective 1 January 2026). Below is a table which summarises Orcadian’s view on its resource position on the assumption that NSTA approves the withdrawal of Serica on the P2634 licence and the withdrawal of Triangle Energy (UK) Pty Ltd from P2650.
|
Licence and block numbers |
Operator or Licence admin. |
Equity |
Status |
Phase Expiry |
Term Expiry |
Licence Area |
Key Discoveries or Prospects |
Net 2U Prospective Resources (Unrisked) |
Net 2C Contingent Resources (Unclarified) |
Net 2C Contingent Resources (On hold) |
Net 2C Contingent Resources (Dev. Pending) |
Phase |
|
|
|
% |
|
|
|
km2 |
MMboe |
MMboe |
MMboe |
MMboe |
|
|
|
P2244 |
Ping Petroleum UK Limited |
18.75% |
Second Term |
n/a |
30-Nov-28 |
43.2 |
Pilot Main and Pilot South |
|
1.8 |
|
13.6 |
Oil |
|
P2482 |
Orcadian |
100% |
Initial Term Phase B |
14-Jul-27 |
14-Jul-29 |
361.6 |
Narwhal |
|
|
9.1 |
|
Oil |
|
Elke |
|
|
45.0 |
|
Oil |
|||||||
|
Elke satellites |
52.0 |
|
|
|
Oil |
|||||||
|
P2680 |
Orcadian |
100% |
Initial Term Phase A |
30-May-28 |
30-May-30 |
388 |
Earlham |
|
|
19.0 |
|
Gas |
|
Clover |
25.5 |
|
|
|
Gas |
|||||||
|
Orwell |
|
|
5.2 |
|
Gas |
|||||||
|
P2650* |
Orcadian |
100% |
Initial Term Phase A |
28-Feb-27 |
28-Feb-30 |
2068.9 |
Glenlough |
21.8 |
|
|
|
Gas |
|
Breckagh |
23.0 |
|
|
|
Gas |
|||||||
|
P2634* |
Orcadian |
100% |
Initial Term Phase A |
28-Feb-27 |
28-Feb-30 |
322.6 |
Finn |
|
324.8 |
|
|
Oil |
|
Lowlander |
|
23.4 |
|
|
Oil |
|||||||
|
* Table assumes completion of the withdrawal of Triangle and Serica from their respective licence interests |
Total (Net) |
122.4 |
350.0 |
78.4 |
13.6 |
|
||||||
[1] Lowlander gross resources are now estimated by Orcadian at 23.4 MMbbl in line with the Parkmead licence application document.
[2] https://ptqmagazines.digitalrefining.com/view/1071976417/81/
[3] https://www.londonstockexchange.com/en/news/article/PMG/sale-of-parkmead-e-p-ltd/5562-50-9b-37-4e-41239b
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 29 seconds ago Ariana Resources
- 2 hours ago MING YANG SMART ENERGY GROUP LIMITED
- 2 hours ago Unite Group
- 4 hours ago Frasers Group
- 4 hours ago Staffline Group