
CIB - Earnings Release - 9M26
Summary by AI BETAClose X

http://www.rns-pdf.londonstockexchange.com/rns/4306C_1-2026-11-9.pdf
|
#1 Private-Sector Bank in Egypt in terms of Revenues, Net Income, Deposits, Loans, and Total Assets
|
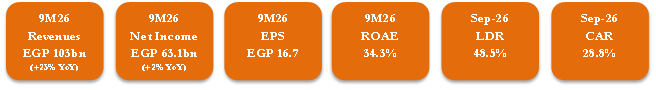
CIB Reports NINE-MONTH 2026 CONSOLIDATED REVENUE OF EGP 103 BILLION AND NET INCOME OF EGP 63.1 BILLION |
|
CAIRO - Commercial International Bank (EGX: COMI) today reported nine-month 2026 financial results, which further solidify the Bank's leadership position within the Egyptian banking sector, and underscore the strength of the Institution's core growth engine which was able to deliver, despite the looming global uncertainties. We demonstrated -once again- how we are built, our strong balance sheet, sound asset quality, and earnings capacity, which will enable us to generate sustainable returns for our shareholders, even in challenging operating conditions. Additionally, the Egyptian economy showed true resilience against the regional and global uncertainties and their inherent implications. This was mainly driven by the durable flexible exchange rate regime, and was echoed by the recent upgrade for the Country's credit rating by Moody's Ratings, maintaining the "positive" outlook. Consolidated net income recorded EGP 63.1 billion, or EGP 16.7 per share, up by 2% from nine-month 2025, despite last year's exceptional EGP 13.1 billion of provision released in third-quarter 2025 pertaining to the recalibration of the Bank's Expected Credit Loss (ECL). Third-quarter 2026 encompassed a couple of non-recurring items as well; a regulatory expense reversal of EGP 2.0 billion, and a provision release of EGP 2.1 billion related to a single-corporate-client-repayment, together adding a net of EGP 3.4 billion after-tax to nine-month 2026 bottom line. Accordingly, the actual growth recorded 18% for nine-month 2026 compared to the same period of last year, and 9% in USD terms. Earnings growth was primarily supported by robust top line performance in sustainable revenue streams, with top line growing by 20% from last year, on a normalized basis, backed by sustained business expansion and proactive liquidity management. This, along with disciplined expense controls, fed into a healthy Return on Average Equity (ROAE) of 34.3%, while simultaneously upholding a comfortable Capital Adequacy Ratio (CAR) of 28.8%, inclusive of a Common Equity Tier I (CET1) Capital Ratio of 25.3%. Balance sheet growth upheld momentum, with local currency deposits adding EGP 110 billion in the third quarter of 2026, representing around 40% of the nine-month-period net sales of EGP 284 billion, of which 70% or EGP 198 billion came in Current Accounts and Saving Accounts (CASA). With that, the CASA share to total deposits has been maintained at 63% from last quarter and up from 60% last year, which came to the aid of preserving margins, that slowed-down by a confined 53 basis-points (bps) against the effective year-round policy-rate-cuts of 600bps. This, altogether, fueled healthy growth in the Bank's net interest income by 19% from last year, despite the persistent and intense competition over local currency funding within and beyond the Egyptian Banking Sector. Similarly, momentum in lending activity continued, with the Bank's loan and securitization portfolio adding EGP 111 billion in the nine-month-period of 2026, in real terms excluding the EGP Devaluation impact. This, coupled with decent growth in contingent business, by 19% or EGP 58 billion, reflected clearly into strong growth in the Bank's non-interest income, by 46% from last year, on a normalized basis, backed by 43% growth in the sustainable stream therein, namely fees and commissions. With that, net fee and commission income represented 9% of top line in the nine-month-period of 2026, up from 8% last year, going apace with Management aspirations to gradually increase the contribution of sustainable non-interest income to the Bank's revenues, in light of the yet-expected-though-delayed easing monetary cycle ahead. In parallel, expense management acted as another key pillar in driving profitability, with the Bank's Cost-to-Income remaining at a healthy level of 15.6%. This transpired despite global inflationary pressures posed on the Bank's expense base, with special regard to the renewal of contracts pertaining to the Bank's technological infrastructure and to its digital transformation initiatives. |
MANAGEMENT COMMENTED: "This solid financial performance echoes the efficiency of the Bank's operating engine within. Notably, the increased technology spend is gradually reflecting into enhanced digital banking capabilities, through the introduction of new customer-centric features, including enhanced credit card controls, a redesigned funds transfer journey and self-service functionalities, that deliver a more seamless and intuitive banking experience for customers. Evidently, CIB managed to attract 380 thousand New-to-Bank (NTB) customers during the nine-month-period of 2026, of which 40% were added in the third quarter, compared to 280 thousand NTB customers last year. Such expansion in the Bank's customer base was largely supported by a sound and evolving digital infrastructure, which reflected into an increase in the volume and value of digital transactions by 17% and 54%, respectively, from last year. With that, CIB has served over 2.3 million users of Online Banking Digital Platforms by end of September 2026. This came along with a 20% increase in the NTB Digital Registration Rate to record 80% of NTB customers for the nine-month-period of 2026, and with over 90% of Consumer Banking financial transactions being conducted through the Bank's Mobile Application by end of September 2026. In tandem, the Bank's card business continued to grow, with over 169 thousand credit cards issued since the beginning of 2026, largely led by CIB EXPLORE which surpassed 150 thousand cards, alongside co-branded cards which extended CIB's reach into everyday digital spending. This inherently reflected into 24% growth in the Bank's credit card portfolio through the nine-month-period of 2026. Meanwhile, third-quarter 2026 witnessed the receipt of the preliminary regulatory approval to establish yomo Digital Bank, through yomo Holding Limited, where CIB plans to invest which USD 162 million already got recognized as a Subsidiary Investment in the Bank's Financial Position as of September 2026. This comes as a foundational milestone to enter the next phase of operational, technological and customer readiness ahead of the launch of yomo services, subject to the final regulatory approval. Moving forward, Management remains positive about the ability of CIB to navigate through market variations and new realities, with special regard to the ongoing geopolitical uncertainty worldwide, while remaining committed to safeguard and create value to its shareholders." |
key highlights
Profitability and Efficiency
|
Third-Quarter 2026 Consolidated Financial Results · Net Income of EGP 23.8 billion · Revenues of EGP 37.0 billion · Return on Average Equity (ROAE) of 38.3% · Return on Average Assets (ROAA) of 5.41% · Efficiency Ratio of 15.2% · Net Interest Margin (NIM)[1] of 8.02% |
Nine-Month 2026 Consolidated Financial Results · Net Income of EGP 63.1 billion · Revenues of EGP 103 billion · ROAE of 34.3% · ROAA of 5.15% · Efficiency Ratio of 15.6% · NIM1 of 8.40% |
Balance Sheet Performance
· Gross Loans recorded EGP 705 billion, with a Loan Market Share of 5.76%[2].
· Deposits recorded EGP 1.45 trillion, with a Deposit Market Share of 7.62%2.
· High quality of funding, with Customer Deposits comprising 93% of Total Liabilities
· Loan-to-Deposit Ratio recorded 48.5% by end of September 2026.
· Total Tier Capital recorded EGP 275 billion, or 28.8% of Risk-Weighted Assets.
· Common Equity Tier I Capital recorded EGP 241 billion, or 88% of Total Tier Capital.
Liquidity and Funding
· Liquidity Ratio of 55.4% in local currency and 54.2% in foreign currency, compared to CBE requirements of 20% and 25%, respectively
· Liquidity Coverage Ratio (LCR) of 940% in local currency and 534% in foreign currency, compared to Basel III requirement of 100%
· Net Stable Funding Ratio (NSFR) of 197% in local currency and 168% in foreign currency, compared to Basel III requirement of 100%
Asset Quality
· Loan Loss Provision Balance of EGP 35.5 billion
· Non-Performing Loans (NPLs)-to-Gross Loans of 1.47%
· NPL Coverage Ratio of 343%
· Total Gross Loan Coverage Ratio of 5.04%
· Unsecured Gross Loan Coverage Ratio of 7.30%
Committed to our Community
· CIB Foundation funded the establishment of a fully-equipped Pediatric Digital Dentistry Center at Galala University, expanding children's access to advanced dental care.
· CIB Foundation funded the establishment of a cardiac catheterization laboratory at the Coptic Hospital, linked to a 10-bed Pediatric Intensive Care Unit, in addition to funding 200 procedures to strengthen specialized cardiac care for children.
· CIB Foundation, in partnership with Tahya Misr Fund, financed 11 pulmonary valve interventions, enabling underserved children to access advanced cardiac treatment.
Awards & Recognitions
|
· Global Finance: · Best Private Bank in Egypt · Best Bank in Egypt · Best SME Bank in Egypt 2026 and 2027 · Top Financial Innovations in Africa · Egypt's Best Trade Finance Provider · Best Bank for Sustainable Finance in Egypt · Best Cash Management Bank in Egypt · Best Bank for Collections in Africa · Best Sub-Custodian Bank in Egypt · Best Consumer Digital Bank in Egypt · Best-in-Transformation in Egypt · Best Online Payment Solution in Egypt and in Africa · Most Innovative Digital Bank in Egypt and in Africa · The Egyptian Exchange: · Best Bank in Sustainable Finance - Africa 2025 · Athar Award: · Best Practices in Sustainability and CSR |
· MEED: · Best Payment Ecosystem Integration · Best SME Bank in Egypt · MENA Transaction Bank of the Year 2026 · Best Bank in Egypt · Euromoney: · Egypt's Best Bank · Egypt's Best Digital Bank · Egypt's Best for ESG · Egypt's Best FX Bank · Egypt's Best Cash Management Bank · Recognitions · Ranked 1st among Egypt's 50 Most Valuable Companies 2026 by Forbes Middle East · Ranked 53rd among Middle East's 100 Most Valuable Companies 2026 by Forbes Middle East · Selected for "Change the World 2026 List" by Fortune · Ranked 7th among World's Top Performing Banks 2026 by Euromoney Cash Management Survey |
P&L and KPIs
|
CONSOLIDATED P&L AND KPIs |
|
|
|
||||||
|
Income Statement |
3Q26 |
2Q26 |
QoQ Change |
3Q25 |
YoY Change |
9M26 |
9M25 |
YoY Change |
|
|
EGP million |
EGP million |
(3Q26 vs. 2Q26) |
EGP million |
(3Q26 vs. 3Q25) |
EGP million |
EGP million |
(9M26 vs. 9M25) |
||
|
Net Interest Income |
32,429 |
31,127 |
4% |
27,318 |
19% |
93,255 |
78,654 |
19% |
|
|
Non-Interest Income |
4,589 |
3,233 |
42% |
1,495 |
207% |
9,350 |
5,030 |
86% |
|
|
Net Operating Income |
37,019 |
34,360 |
8% |
28,813 |
28% |
102,606 |
83,683 |
23% |
|
|
Non-Interest Expense |
(5,618) |
(5,201) |
8% |
(4,517) |
24% |
(15,974) |
(12,433) |
28% |
|
|
Total Provisions[3] |
1,503 |
(562) |
NM |
12,735 |
-88% |
431 |
12,040 |
-96% |
|
|
Net Profit before Tax |
32,904 |
28,596 |
15% |
37,031 |
-11% |
87,063 |
83,291 |
5% |
|
|
Income Tax |
(8,597) |
(8,128) |
6% |
(8,380) |
3% |
(23,092) |
(21,842) |
6% |
|
|
Deferred Tax |
(542) |
1,024 |
NM |
103 |
NM |
(892) |
652 |
NM |
|
|
Net Profit |
23,766 |
21,492 |
11% |
28,754 |
-17% |
63,079 |
62,100 |
2% |
|
|
Non-Controlling Interest |
2.03 |
0.31 |
555% |
(0.38) |
NM |
2.30 |
0.57 |
304% |
|
|
Bank's Shareholders |
23,764 |
21,491 |
11% |
28,754 |
-17% |
63,077 |
62,100 |
2% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Financial Indicators |
3Q26 |
2Q26 |
QoQ Change |
3Q25 |
YoY Change |
9M26 |
9M25 |
YoY Change |
|
|
|
|
(3Q26 vs. 2Q26) |
|
(3Q26 vs. 3Q25) |
|
|
(9M26 vs. 9M25) |
||
|
ROAE |
38.3% |
37.8% |
1% |
59.8% |
-36% |
34.3% |
45.9% |
-25% |
|
|
ROAA |
5.41% |
5.28% |
2% |
8.59% |
-37% |
5.15% |
6.44% |
-20% |
|
|
Cost-to-Income |
15.2% |
15.1% |
0% |
15.7% |
-3% |
15.6% |
14.9% |
5% |
|
|
Gross Loans-to-Deposits |
49.3% |
52.5% |
-6% |
49.9% |
-1% |
49.3% |
49.9% |
-1% |
|
|
NPLs-to-Gross Loans |
1.56% |
1.59% |
-2% |
2.52% |
-38% |
1.56% |
2.52% |
-38% |
|
|
Capital Adequacy Ratio |
28.8% |
28.4% |
2% |
30.2% |
-5% |
28.8% |
30.2% |
-5% |
|
|
STANDALONE P&L AND KPIs
|
|
|
|
||||||
|
Income Statement |
3Q26 |
2Q26 |
QoQ Change |
3Q25 |
YoY Change |
9M26 |
9M25 |
YoY Change |
|
|
EGP million |
EGP million |
(3Q26 vs. 2Q26) |
EGP million |
(3Q26 vs. 3Q25) |
EGP million |
EGP million |
(9M26 vs. 9M25) |
||
|
Net Interest Income |
32,245 |
30,947 |
4% |
27,207 |
19% |
92,721 |
78,358 |
18% |
|
|
Non-Interest Income |
4,434 |
3,084 |
44% |
1,478 |
200% |
8,878 |
4,948 |
79% |
|
|
Net Operating Income |
36,679 |
34,031 |
8% |
28,685 |
28% |
101,600 |
83,306 |
22% |
|
|
Non-Interest Expense |
(5,402) |
(5,010) |
8% |
(4,336) |
25% |
(15,383) |
(11,880) |
29% |
|
|
Total Provisions3 |
1,594 |
(401) |
NM |
12,736 |
-87% |
736 |
12,057 |
-94% |
|
|
Net Profit before Tax |
32,872 |
28,620 |
15% |
37,085 |
-11% |
86,952 |
83,483 |
4% |
|
|
Income Tax |
(8,567) |
(8,159) |
5% |
(8,390) |
2% |
(23,030) |
(21,868) |
5% |
|
|
Deferred Tax |
(566) |
1,036 |
NM |
103 |
NM |
(948) |
592 |
NM |
|
|
Net Profit |
23,738 |
21,497 |
10% |
28,798 |
-18% |
62,974 |
62,208 |
1% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Financial Indicators |
3Q26 |
2Q26 |
QoQ Change |
3Q25 |
YoY Change |
9M26 |
9M25 |
YoY Change |
|
|
|
|
(3Q26 vs. 2Q26) |
|
(3Q26 vs. 3Q25) |
|
|
(9M26 vs. 9M25) |
||
|
ROAE |
38.5% |
38.1% |
1% |
60.2% |
-36% |
34.5% |
46.3% |
-25% |
|
|
ROAA |
5.41% |
5.30% |
2% |
8.65% |
-37% |
5.15% |
6.48% |
-21% |
|
|
NIM[4] |
8.02% |
8.36% |
-4% |
8.86% |
-9% |
8.40% |
8.93% |
-6% |
|
|
Cost-to-Income |
14.7% |
14.7% |
0% |
15.1% |
-3% |
15.1% |
14.3% |
6% |
|
|
Gross Loans-to-Deposits |
48.5% |
52.2% |
-7% |
49.7% |
-2% |
48.5% |
49.7% |
-2% |
|
|
NPLs-to-Gross Loans |
1.47% |
1.49% |
-2% |
2.48% |
-41% |
1.47% |
2.48% |
-41% |
|
|
Direct Coverage Ratio |
343% |
358% |
-4% |
281% |
22% |
343% |
281% |
22% |
|
NINE-MONTH 2026 KEY P&L HIGHLIGHTS
· REVENUES
Nine-Month 2026 Standalone Revenues were EGP 102 billion, up 22% from nine-month 2025, on the back of 18% increase in Net Interest Income, coupled with 79% increase in Non-Interest Income.
· NET INTEREST INCOME
Nine-Month 2026 Standalone Net Interest Income recorded EGP 92.7 billion, increasing by 18% Year-on-Year (YoY), generated at 8.40% Total NIM4, with Local Currency NIM4 recording 11.8%, coming 120bps lower YoY, and Foreign Currency NIM4 recording 2.17%, decreasing by 42bps YoY.
· NON-INTEREST INCOME
Nine-Month 2026 Standalone Non-Interest Income recorded EGP 8.88 billion, coming 79% higher YoY. Trade Service Fees recorded EGP 2.87 billion, higher by 8% YoY, with outstanding balance of EGP 355 billion[5].
· OPERATING EXPENSE
Nine-Month 2026 Standalone Operating Expense recorded EGP 15.4 billion, up 29% YoY, largely on technology-related expenses and contract renewals, impacted by global inflationary pressures. Cost-to-Income reported 15.1%, coming 88bps higher YoY, yet remaining comfortably below the desirable level of 30%.
BALANCE SHEEt
|
|
CONSOLIDATED BALANCE SHEET |
STANDALONE BALANCE SHEET |
||||
|
|
Sep-26 |
Dec-25 |
YtD Change |
Sep-26 |
Dec-25 |
YtD Change |
|
EGP million |
EGP million |
(Sep-26 vs. Dec-25) |
EGP million |
EGP million |
(Sep-26 vs. Dec-25) |
|
|
Cash and Balances at The Central Bank |
100,683 |
88,876 |
13% |
100,321 |
88,095 |
14% |
|
Due from Banks |
276,033 |
135,237 |
104% |
277,076 |
136,582 |
103% |
|
Net Loans and Advances |
673,066 |
542,395 |
24% |
665,229 |
537,802 |
24% |
|
Derivative Financial Instruments |
37 |
620 |
-94% |
37 |
620 |
-94% |
|
Financial Investments |
710,533 |
613,070 |
16% |
707,965 |
609,866 |
16% |
|
Investments in Associates and Subsidiaries |
40 |
45 |
-11% |
9,617 |
1,157 |
731% |
|
Other Assets |
65,786 |
62,251 |
6% |
65,497 |
62,031 |
6% |
|
Total Assets |
1,826,177 |
1,442,494 |
27% |
1,825,741 |
1,436,153 |
27% |
|
Due to Banks |
23,411 |
3,354 |
598% |
21,826 |
3,797 |
475% |
|
Customer Deposits |
1,448,932 |
1,110,396 |
30% |
1,452,466 |
1,105,356 |
31% |
|
Other Liabilities |
95,386 |
97,230 |
-2% |
94,844 |
96,986 |
-2% |
|
Total Liabilities |
1,567,729 |
1,210,980 |
29% |
1,569,137 |
1,206,138 |
30% |
|
Shareholders' Equity & Net Profit |
258,408 |
231,486 |
12% |
256,604 |
230,015 |
12% |
|
Non-Controlling Interest |
41 |
28 |
46% |
0 |
0 |
NM |
|
Total Liabilities & Shareholders' Equity |
1,826,177 |
1,442,494 |
27% |
1,825,741 |
1,436,153 |
27% |
NINE-MONTH 2026 KEY BALANCE SHEET HIGHLIGHTS
· LOANS
Gross Loan Portfolio recorded EGP 705 billion, growing by 22% throughout nine-month 2026, with real growth of 20% or EGP 116 billion net of the EGP Devaluation impact, with Local Currency Loans increasing by 21% or EGP 93.7 billion, together with Foreign Currency Loans increasing by 15% or USD 439 million. CIB's Loan Market Share recorded 5.76% as of June 2026.
· DEPOSITS
Deposits recorded EGP 1.45 trillion, growing by 31% throughout nine-month 2026, with real growth of 27% or EGP 308 billion net of the EGP Devaluation impact, with Local Currency Deposits increasing by 42% or EGP 284 billion, together with Foreign Currency Deposits adding 5% or USD 461 million. CIB's Deposit Market Share recorded 7.62% as of June 2026.
key BUSINESS UPDATES
· INSTITUTIONAL BANKING
· Gross Loans recorded EGP 573 billion, with Year-to-Date (YtD) real growth of 19% or EGP 93 billion net of the EGP Devaluation impact.
· Lending growth was primarily driven by Transportation and Natural Gas Sectors.
· CIB Corporate Loan Market Share stood at 5.21% as of May 2026, with Private Corporate Loan Market Share recording 11.0%.
· Deposits recorded EGP 487 billion, with YtD real growth of 36% or EGP 129 billion net of the EGP Devaluation impact.
· CIB Corporate Deposit Market Share stood at 7.39% as of May 2026.
· Gross Outstanding Contingent Business recorded EGP 368 billion.
· BUSINESS BANKING
· Gross Loans recorded EGP 21 billion, with YtD real growth of 30% or EGP 4.9 billion net of the EGP Devaluation impact.
· Deposits recorded EGP 150 billion, with YtD real growth of 26% or EGP 31 billion net of the EGP Devaluation impact.
· Clients upgraded through nine-month 2026 from Business Banking to Institutional Banking recorded a net of 156 Clients, with EGP 7.0 billion worth of Deposits.
· Gross Outstanding Contingent Business recorded EGP 7.33 billion.
· Third-Quarter 2026 Major Milestones:
o CIB launched its first export readiness workshop, reinforcing its commitment to empowering customers, supporting their export ambitions, and expanding their opportunities in international markets.
o CIB introduced tailored credit solutions designed after addressing unique characteristics of specific sectors and industries, offering flexible financing options that meet customers' evolving needs and support sustainable business growth for different company sizes.
· RETAIL INDIVIDUALS BANKING
· Gross Loans recorded EGP 111 billion, with YtD real growth of 20% or EGP 18.5 billion net of the EGP Devaluation impact, primarily driven by Personal Loans and Credit Cards.
· CIB Household Loan Market Share stood at 6.48% as of May 2026.
· Deposits recorded EGP 815 billion, with YtD real growth of 23% or EGP 151 billion net of the EGP Devaluation impact, driven mainly by CASA and CDs with strong contribution from the Private and Wealth Segments.
· CIB Household Deposit Market Share stood at 7.47% as of May 2026.
· CIB continued to expand and strengthen its nationwide presence, reaching 215 branches and 11 units across Egypt, supported by a network of 1,513 ATMs, reinforcing the Bank's commitment to scalable growth, accessibility, and customer experience excellence.
· Active Digital Users among CIB Consumer Banking Customers have grown by 21% YtD, with over 90% of the Consumer Banking financial transactions being conducted through CIB Mobile Application as of September 2026.
· Third-Quarter 2026 Major Milestones:
o CIB inaugurated Royal Park, the first branch featuring its new branch image, introducing a modern, innovative, and physical banking environment that integrates both physical and digital experiences to enhance customer experience and engagement.
o CIB EXPLORE surpassed 150 thousand cards, supported by digital and social media campaigns with the leading travellers' community group in Egypt.
o CIB's partnerships and alliances ecosystem extended the Bank's value proposition beyond banking through seasonal campaigns across all consumer segments driving EGP 6 billion in instalments. It also became a growth engine for consumer lending with end-use car finance acquisitions reaching EGP 1.3 billion by end of September 2026.
o CIB's loyalty program, covering Bonus, Cashback and EXPLORE, became a key driver of engagement and spend where the total engaged customers grew almost 2.1 times, the redemption rate reached 60% and redeeming customers spent approximately 2.7 times more than others supported by a network of more than 170 merchants.
o MyCIB Minor Account was launched, allowing children from the age of 7 to enjoy a myCIB debit card with their own name, cashback, exclusive offers, and more, while parents remain in full control of the account.
o CIB continued to expand its payroll customer base, reaching a new record of breaking the One-Million-Payroll-Employees.
o CIB participated in the "Financial-Inclusion-for-Farmers" Initiative, under the auspices of the Central Bank of Egypt, in efforts to introduce farmers to the banking products and services.
· DIGITAL BANKING
· Online Digital Banking Platforms served more than 2.3 million users by end of September 2026, up by 17% YoY.
· Online Digital Banking Transaction Value recorded c. EGP 5.7 trillion across all of the Bank's Digital Platforms, up by 54% YoY.
· Digital Acquisition Rate for CDs through the Bank's Online Channels recorded 91.6%.
· Number of NTB Customers recorded c. 380 thousand during nine-month 2026, up by 36% YoY, supported by the Bank's Digital Infrastructure, with an increase in NTB Digital Registration Rate by 20% YoY.
[1] Based on standalone managerial accounts
[2] As of June 2026; latest available CBE data at time of publishing
[3] Total Provisions include "Release (charges) for ECL" and "Release (charges) of other provisions", reported under "Other operating income (expenses)".
[4] NIM based on managerial accounts
[5] Net of Collateral, Gross of Provisions
[6] 1) Loan, Deposit, and Outstanding Contingent Balances are based on managerial accounts. 2) Outstanding Contingent Balances are gross of collateral and provisions.
3) Market Share Data for Business Lines is as of May 2026, the latest published CBE Monthly Statistical Bulletin at time of publishing.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 1 minute ago CLS Holdings
- 9 minutes ago British American Tobacco
- 14 minutes ago British American Tobacco
- 18 minutes ago B.P. Marsh & Partners
- 19 minutes ago British American Tobacco