
Annual Results
Summary by AI BETAClose X

30 September 2026
|
Annual Results |
Celsius Resources Limited (“Celsius” or the ”Company”) (ASX, AIM: CLA) announces its annual results for the year ended 30 June 2026.
The full annual report inclusive of the audit report is available on the Company's website: https://celsiusresources.com
This announcement has been authorised by the Board of Directors of Celsius Resources Limited.
|
Celsius Resources Limited |
|
|
Bardin Davis – Managing Director |
|
|
Purple Communications Pty Ltd Andrew Edge
|
P: +61 410 276 744 |
|
Zeus Capital Limited Nominated Adviser - James Joyce / James Bavister Broking - Harry Ansell |
P: +44 (0) 20 3 829 5000 |
REVIEW OF OPERATIONS
Celsius continued its primary focus on the Maalinao-Caigutan-Biyog Copper-Gold Project (“MCB Project”) in the Philippines.
Key events over the 12 months to 30 June 2026 and to the date of the Directors Report include:
- Key management and board appointments;
- Completion of ~A$9.3 million equity raising;
- Updated Mineral Resources Estimate and a maiden Ore Reserve Estimate for the MCB Project;
- Completion of a Definitive Feasibility Study on the MCB Project;
- Continued momentum across key MCB Project workstreams;
- Ongoing commitment to the MCB Project community and local stakeholders;
- Restructuring of Makilala Mining Company, Inc (“MMCI”);
- Dispute with Kiri Industries;
- Pending sale of the Opuwo Cobalt-Copper Project to Chinalco;
- Increased focus on the Sagay Copper Project; and
- Renewal of the exploration permit for the Botilao Copper-Gold Project.
Key management and board appointments
There were a series of changes to the Celsius Board and management team over the period.
Following the completion of the 2025 Annual General Meeting Attorney Julito “Sarge” Sarmiento (“Attorney Sarmiento”) retired as Executive Chairman and Dr Attilenore “Nene” Manero resigned as a Director. The Board would like to extend its gratitude to Dr Manero for her significant contribution to Celsius.
On 2 April 2026, Mr Bardin Davis was appointed as Managing Director. Mr Davis has ~30 years of investment banking and corporate experience within the mining and energy sectors. He was the CEO of ASX listed Peak Rare Earths Limited (“Peak”) for ~5 years and is a former CFO of UPC/AC Renewables Australia (now ACEN Australia). During his banking career he spent almost 12 years in Asia and worked on a broad range of international advisory, capital market and financing transactions. He has held senior Australian and regional investment banking roles with Macquarie Capital, HSBC and ABN AMRO.
During his time with Peak he oversaw a project financing process, the execution of a binding offtake agreement, the securing of a special mining licence and an investment framework agreement with the Government of Tanzania, the delivery of a BFS Update and FEED Study and a sale of the company that delivered a 269% takeover premium and a ~330% premium after accounting for the value of a concurrent entitlement offer.
Mr Neil Grimes, a former Executive Director, resigned from the Board on 11 May 2026.
On 18 May 2026, Mr Ian Hobson was appointed as Celsius’ Company Secretary and Chief Financial Officer. Mr Hobson is a Chartered Accountant and Chartered Company Secretary with 40 years of experience. He was a director at PricewaterhouseCoopers for many years with experience working in Australia, UK and Canada.
On 14 July 2026, Mr George Bujtor was appointed as Non-Executive Chair. Mr Bujtor is a highly distinguished mining executive with over 50 years of technical, commercial and leadership experience across the global resources sector. His appointment brings strong technical expertise, senior leadership and governance experience and a proven track record in successfully funding, developing and operating Philippine mining projects.
He spent over 25 years with Rio Tinto, holding senior technical, development, and commercial roles in Australia. Mr Bujtor has been predominantly based in the Philippines since 2005, and has held a series of senior roles within the Philippine mining sector, including as Managing Director of both Toledo Mining Corporation plc (“Toledo Mining”) and Carmen Copper Corporation (“Carmen Copper”).
During his time with Toledo Mining, Mr Bujtor oversaw the successful funding and development of the Berong Nickel Laterite Project. As Managing Director of Carmen Copper, he led the ramp-up to full production of the rehabilitated Carmen Copper Project, the optimisation of by-product production and a US$300 million financing.
Completion of ~A$9.3 million equity raising
During the March Quarter, Celsius strengthened its cash position through the completion of ~A$9.3 million equity raising (before costs). The offering entailed issuing 465 million shares at A$0.02 per share and 232.5 million free attaching options (expiring 3 years from the date of issue and with an exercise price of A$0.022 per option).[1]
The funds raised have been and will continue to be applied towards:
- Corporate working capital purposes throughout 2026, including funds available to contribute to fees payable to advisors and consultants to support the process of financing the MCB Project;
- Compliance activities for the MCB, Sagay and Botilao Projects;
- Pursuing mineralised extensions at the Botilao Project;
- Fees associated with the Placement; and
- Legal and other costs associated with the arbitration dispute with MMCI.
Updated Mineral Resources and maiden Ore Reserves for the MCB Project
Following the completion of geotechnical and hydrogeological drilling programs and the commencement of a Definitive Feasibility Study (“DFS”), the Mineral Resource Estimate (“MRE”) for the MCB Project was updated and a maiden Ore Reserve Estimate was published.
The updated 2012 JORC Code compliant MRE was announced in November 2025. It comprised 343Mt at a grade of 0.46% copper and 0.12g/t gold, with contained copper of 1.6Mt and contained gold of 1.4Moz (based on a cutoff grade of 0.20% copper).
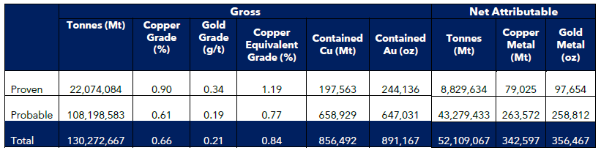
A maiden JORC compliant Ore Reserve Estimate was announced in December 2025, comprising of 130.2Mt at a grade of 0.66% copper and 0.21g/t, with contained copper of 856kt and contained gold of 891koz.
Completion of a Definitive Feasibility Study on the MCB Project
In January 2026, a DFS for the MCB Project was released.
The DFS confirmed a technically and economically enhanced MCB Project. It was completed to a Class 3 level of estimate accuracy (typically up to ±15%), consistent with industry standards and suitable for project financing and execution planning. The DFS follows a Scoping Study announced in December 2021.
Key technical and financial DFS outcomes are set out in the table below.
|
Item |
1st 10 years |
Life of mine |
|
Ore Mined |
24.5 Mt |
89.7 Mt |
|
Copper Grade |
1.08% |
0.69% |
|
Gold Grade |
0.51 g/t |
0.24 g/t |
|
Copper Recovery |
92.5% |
89.7% |
|
Gold Recovery |
79.7% |
72.6% |
|
Mine Life |
10 Years |
35.3 Years |
|
Process Plant Throughput |
2.64 Mtpa |
2.64 Mtpa |
|
Average Annual Cu Concentrate Production (dry) |
102.5 kt |
66.0 kt |
|
Total Copper Recovered |
542 Mlbs |
1,234 Mlbs |
|
Total Gold Recovered |
319 koz |
507 koz |
|
Copper Price for 1st 9 Years (assumed) |
US$4.3/lb |
US$4.3/lb |
|
Copper Price for Remaining Years |
US$7.0/lb |
US$7.0/lb |
|
Gold Price for 1st 9 Years (assumed) |
US$3,000/oz |
US$3,000/oz |
|
Gold Price for Remaining years |
US$4,500/oz |
US$4,500/oz |
|
Initial Capital |
US$276 M |
US$276 M |
|
NPV (Post Tax; 8%) |
US$444 M |
US$771 M |
|
NPV (Pre Tax; 8%) |
US$771 M |
US$1.3 Bn |
|
IRR (Pre Tax) |
28.5% |
30.5% |
|
IRR (Post Tax) |
22.1% |
24.1% |
|
Payback from Start of Production |
4.7 Years |
4.7 Years |
|
LOM C1 Cost (net of by-product credits) |
US$0.41/lb Cu |
US$1.73/lb Cu |
Continued momentum across key MCB Project workstreams
In addition to the completion of the DFS, other key MCB Project workstreams included:
- Further optimisation of underground mine development – including evaluating the potential for earlier access of higher-grade mineralised areas;
- Main access road – including completing a survey of the proposed alignment of the road between the MCB Project and Mt. Sapukoy;
- Process Plant – initiation of a tendering process for an Engineering, Procurement and Construction (“EPC”) contract; and
- Power supply – engagement with power companies around a range of power options.
Ongoing commitment to the MCB Project community and local stakeholders
A broad range of social and economic initiatives were implemented to support the local Balatoc Community including:
- Regular stakeholder engagement – including meetings with the Barangay Balatoc-Council of Elders;
- Community-based skills training – covering carpentry training and certification programs, financial literacy training and educational scholarships;
- Medical missions – covering medical and dental missions in partnership with the Municipal Health Office;
- Baseline studies – including a Balatoc Cultural Heritage Baseline Study to document and preserve cultural knowledge and practices for future generations; and
- Infrastructure support – including repairs and construction works to bridges, potable water systems and slope stabilisation.
MMCI dispute and proposed restructuring
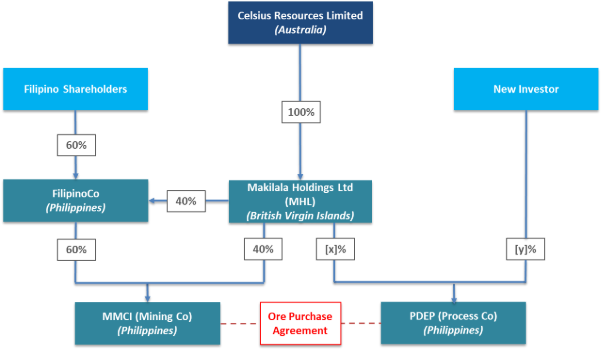
In the Philippines, the holder of a Mineral Production Sharing Agreement (“MPSA”) must be 60% owned by a Philippine entity, while a separate mineral processing company may be up to 100% foreign-owned.
To ensure compliance with these requirements, the following ownership arrangements for the MCB Project were agreed via binding deeds and agreements on 17 March 2023:
- Sodor, Inc. ("Sodor") was to acquire a 60% legal ownership in Makilala Mining Company, Inc. (“MMCI”) for consideration of PHP 300 million (~US$5 million);
- PMR Holding Corp. (“PMR”), an affiliate of Sodor, was to subscribe for shares in PDEP Inc. (“PDEP”), the intended mineral processing company for the MCB Project, for an amount of ~US$38 million (comprising of ~US$43 million less the PHP 300 million subscription in MMCI by Sodor); and
- These arrangements were to be relinquished, if Sodor and PMR had not provided the required payment within two years, unless shortened or extended by mutual agreement.
The MCB Project was to be owned and operated via the following two entities:
- MMCI - which would hold the MPSA and develop and operate the mine; and
- PDEP - which would own, develop and operate the processing plant and other ancillary equipment and assets, and would not be subject to foreign ownership restrictions.
Upon completion of the payment of the ~US$43 million, Sodor and PMR were to hold a combined 30% share of economics in the MCB Project with Celsius retaining a 70% share of economics.
The expiry date for the payment of ~US$43 million was extended to 16 February 2026.
Following the expiry of this deadline, Celsius provided written notice to Sodor that the MMCI shares must be relinquished in accordance with the agreement.
Notwithstanding the expiry of the payment deadline (and the provision of the notice to Sodor outlined above), Sodor subsequently (approximately 30 days after the deadline expired) attempted to pay the outstanding amount of PHP 300 million (~US$5 million) and a notice was received from PMR stating that it had sufficient funding to complete its subscription of shares in PDEP.
Celsius believes that the right of Sodor and PMR to make payment has expired and the matter has been referred to arbitration.
Way forward
Celsius is in discussions with potential replacement Filipino partners regarding the 60% interest in MMCI that Celsius contends is required to be relinquished by Sodor, subject to the outcome of the arbitration and applicable legal requirements, which would result in Celsius retaining its 40% direct interest in MMCI.
Subject to the outcome of arbitration, Celsius may be able to retain an interest in PDEP of up to 100% ahead of any potential sell-down or dilution to a new investor as part of the MCB Project funding process.
An indicative future structure for the MCB Project is set out below.
Dispute with Kiri Industries
Celsius is in a dispute with Equinaire Holdings Limited (“Equinaire”), a wholly-owned subsidiary of Indian-based Kiri Industries Limited (“Kiri”), with respect to the Omnibus Loan and Security Agreement (“OLSA”), which relates to a financing facility provided by Maharlika Investment Corporation (“MIC”) to MMCI.
Following the purported sale and assignment of the OLSA by MIC to Equinaire, Equinaire issued the following notices in July 2026:
- Notice of Event of Default – claiming that the Notice of Relinquishment issued to Sodor, constituted an Event of Default;
- Notice of Commencement of Foreclosure Proceedings – seeking to initiate a foreclosure process and the enforcement of security with respect to MHL’s 40% interest in MMCI; and
- Notice of Disposition – seeking to initiate a public auction for Celsius’ 40% interest in MMCI.
Equinaire subsequently issued the following additional notices:
- Notice of Event of Default – claiming that certain information-security incidents involving MMCI constituted an Event of Default;
- Notice of Event of Default – claiming that Celsius’ attempt to seek protections from Philippine courts in relation to Equinaire’s attempted foreclosure itself constituted an Event of Default;
- Notice of a Resumption of Foreclosure – seeking to recommence foreclosure and the enforcement of security with respect to Celsius’ 40% interest in MMCI; and
- Notice of Disposition - seeking to proceed with a public auction of Celsius’ 40% interest in MMCI on 8 September 2026.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI.
Petition for Interim Measures of Protection
A Petition for Interim Measures of Protection (“Petition”) was filed with a Philippine court, seeking to injunct any foreclosure of the OLSA or disposition of Celsius’ interest in MMCI until the conclusion of arbitration between the parties.
The court denied the Petition, finding that "irreparable injury” had not been sufficiently established and determining that any potential loss arising from the foreclosure could be addressed through remedies available in arbitration.
However, the court expressly stated that the denial of the Petition is not a determination that an Event of Default occurred or that Equinaire was entitled to foreclose. The Court likewise recognised that these issues remain disputed and should be addressed via arbitration. The court further emphasised that the arbitral tribunal has authority to determine the validity of any foreclosure and, where appropriate, grant interim relief.
Public auction
On 8 September 2026, Equinaire proceeded to conduct the public auction for the foreclosure of MHL’s shares in MMCI, which were pledged as collateral under the OLSA.
Representatives from MHL were in attendance to put on record that any results of the foreclosure sale remain subject to the final determination of the pending arbitration between MHL and Equinaire.
Equinaire submitted a credit bid of US$5,010,000. As there were no other registered bidders in attendance and no other bids received, Equinaire was declared the winning bidder.
Next steps
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI. It believes that Equinaire’s claimed Events of Default should be referred to arbitration in accordance with the dispute resolution clauses within the OLSA.
Celsius intends to protect its interests through a combination of appeals to higher Philippine courts and by progressing arbitration to seek an injunction around the transfer of MMCI shares, to dispute the occurrence and continuance of any claimed Events of Default and to pursue damages against Equinaire.
Pending sale of the Opuwo Cobalt-Copper Project to Chinalco
In June 2026, Celsius executed a binding Share Sale Agreement with Chinalco (Xiong’an) Mining Corporation Limited (“Chinalco (Xiong’an) Mining”), a subsidiary of Aluminum Corporation of China (“Chinalco”), in relation to a sale of its 95% interest in the Opuwo Cobalt-Copper Project (“Opuwo Project”) in Namibia.
The Opuwo Project is a large-scale, advanced cobalt-copper exploration and development Project located in the Kunene Region of North-Western Namibia.
The divestment will enable Celsius to increase its focus on its Philippine portfolio of copper-gold projects and provide a material source of near-term funding. Subject to resolving the current arbitration disputes with respect to MMCI, Celsius intends to utilise the net proceeds from the proposed sale to progress the development of the MCB Copper-Gold Project.
The transaction entails the sale of an intercompany loan and Celsius’ 95% interest in Opuwo Cobalt Holdings (Proprietary) Limited for total consideration of US$15 million.
Chinalco (Xiong'an) Mining is a specialised non-ferrous subsidiary of Chinalco that is focused on the development of large-scale international base metals projects.
The transaction, which remains subject to a series of conditions precedent, is targeted to complete before 29 December 2026.
Increased attention on the Sagay Copper Project
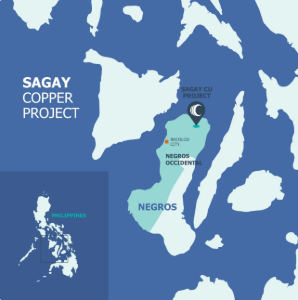
Following recent developments relating to MMCI, Celsius has renewed its attention on its longer-term plan to develop the Sagay Copper Project, which is located in the north-eastern part of Negros Island, within the Province of Negros Occidental, Philippines.
Sagay Project location and snapshot
|
|
|
The Sagay Project is intended to be developed in two phases.
Phase 1 - initial development of the shallow supergene copper deposit.
A small initial low-cost project entailing:
- Medium-scale surface mining operation (mine footprint limited to ~20 hectares);
- Processing of ore through gravity separation (avoiding the need for chemical reagents and flotation agents);
- Dry-stacking of tailings to eliminate the need for a tailings dam; and
- Production of a highly marketable copper concentrate with no material deleterious elements.
Phase 2 - potential future development of the large-scale deep copper-gold porphyry.
Subject to the support of the local community and further technical studies, Celsius intends to assess the longer-term potential for developing the large-scale copper porphyry project comprising of:
- An underground block cave mining operation; and
- Processing of ore and the production of a copper-gold concentrate via a standard milling and flotation operation.
A Declaration of Mining Project Feasibility application has been submitted to the Philippine Mines and Geosciences Bureau and an updated Environmental Impact Assessment has been submitted to the Department of Environment and Natural Resources.
Renewal of the exploration permit for the Botilao Copper-Gold Project
The exploration permit for the Botilao Copper-Gold Project (“Botilao Project”) was renewed in February 2026.
The Botilao Project is located in the Cordillera Administrative Region in the Philippines, ~320km north of Manila. It is located south-west of the MCB Project and comprises of an area of 947 hectares. The project could have the potential to provide additional feed to the MCB Project.
Drilling undertaken by Lepanto Exploration Asia in the 1970s determined the presence of copper-gold mineralisation in the area with copper grades up to ~1%.
The permit renewal secures the capacity to expand its resource base and demonstrates ongoing regulatory support from Philippine authorities.
MATERIAL BUSINESS RISKS
Litigation risks
The Company is currently involved in a series of legal disputes and arbitration proceedings. The outcome of these disputes and proceedings could have a material impact on the Company’s future prospects, including its interests and entitlements with respect to the MCB Project.
Exploration and development risk
The exploration for and development of mineral deposits involve significant risks that even a combination of careful evaluation, experience and knowledge may not eliminate. While the discovery of an ore body may result in substantial rewards, not all exploration activity will lead to the discovery of economic deposits, and even fewer are ultimately developed into producing mines. Major expenditure may be required to locate and establish Ore Reserves, to establish rights to mine the ground, to receive all necessary operating permits, to develop metallurgical processes and to construct mining and processing facilities at a particular site.
Future capital requirements
The Company has finite financial resources and no current cash flow from producing assets and therefore requires additional financing in order to carry out its exploration and development activities. There can be no assurance that any such funding will be available to the Company on favourable terms or at all. Failure to obtain appropriate financing on a timely basis could cause the Company to have an impaired ability to expend the capital necessary to undertake or complete drilling programs, forfeit its interests in certain properties, and reduce or terminate its operations entirely. If the Company raises additional funds through the issue of equity securities, this may result in dilution to the existing shareholders and/or a change of control at the Company.
Title, tenure and land access risks
The rights to mineral tenements carry with them various obligations which the holder is required to comply with in order to ensure the continued good standing of the tenement. Failure to meet these requirements could prejudice the right to maintain title to a given area and result in government or third-party action to forfeit a tenement or tenements.
Mining and exploration tenements are subject to periodic renewal. The renewal of the term of granted tenements is subject to compliance with the applicable mining legislation and regulations and the discretion of the relevant mining authority.
Sovereign risk
The Company is subject to political, social, economic and other uncertainties including, but not limited to, changes in policies or the personnel administering them, foreign exchange restrictions, changes of law affecting foreign ownership, currency fluctuations, royalties and tax increases.
Environmental regulation
The Company’s exploration and evaluation activities are subject to laws and regulations governing the protection of the environment. These laws and regulations are continually changing and generally becoming more restrictive. The Company believes its activities are materially in compliance with all applicable laws and regulations.
SIGNIFICANT CHANGES IN THE STATE OF AFFAIRS
On 17 March 2023, agreements were entered into whereby Sodor acquired a 60% legal ownership in MMCI (owner of the MCB Project) for consideration of ~US$5 million. PMR, an affiliate of Sodor, was to subscribe for shares in PDEP Inc. the intended mineral processing company for the MCB Project, for an amount of ~US$38 million. The net effect would leave CLA with 70% economic interest in the MCB project. Payment of the combined consideration of US$43M was not received by the due date (16 February 2026).
Up until 20 April 2026, MMCI had been consolidated into CLA. The determination of CLA as the parent of MMCI was based on the following factors:
1. CLA’s exclusive funding of MMCI until April 2026;
2. CLA’s exposure to economic risk and influence over financial direction;
3. The Board of MMCI comprised nominees of CLA and no Sodor representatives were appointed until April 2026.
On 20 April 2026, Sodor requisitioned a MMCI shareholder’s meeting at which all five MMCI board seats were declared vacant and Sodor appointed its own representatives to the MMCI Board and terminated key executives. CLA has been unable to exercise any form of management / control of MMCI since that time.
CLA considers that for financial reporting purposes, it ceased to be the parent of MMCI on 20 April 2026 and therefore MMCI should be deconsolidated as at that date. CLA has determined its 40% interest in MMCI provides it with significant influence and this investment will be subsequently measured using equity accounting. The FV of the retained equity interest on 20 April 2026 has been determined to be $16,408,178 after taking into account the fair value of the loan to MMCI.
The Directors are not aware of any other significant change in the state of affairs of the consolidated entity that occurred during the financial year other than as reported elsewhere in the Annual Report.
FINANCIAL POSITION
The net assets of the consolidated entity have decreased to $11,929,674 as at 30 June 2026, a decrease of $14,522,231 from net assets in the prior period of $26,451,905.
The consolidated entity’s net working capital is $9,702,808 (2025: $4,975,009).
EVENTS AFTER THE REPORTING PERIOD
Appointment of Chair
On 14 July 2026, the Company appointed George Bujtor as Non-Executive Chair of the board of directors.
Equinaire dispute
As highlighted in Note 23 CLA considers that for financial reporting purposes, it ceased to be the parent of MMCI on 20 April 2026 and therefore MMCI should be deconsolidated as at that date. Subsequent to 20 April 2026, the Philippine sovereign wealth fund, Maharlika Investment Corporation (“MIC”) completed the assignment of its rights, title, and interests under the Omnibus Loan and Security Agreement (“OLSA”) with Makilala Mining Company Inc. (“MMCI”) to Equinaire, a wholly-owned subsidiary of Kiri Industries Limited (“Kiri”) of India
Following the purported sale and assignment of the OLSA by MIC to Equinaire, Equinaire issued the following notices in July 2026:
- Notice of Event of Default – claiming that the Notice of Relinquishment issued to Sodor, constituted an Event of Default;
- Notice of Commencement of Foreclosure Proceedings – seeking to initiate a foreclosure process and the enforcement of security with respect to MHL’s 40% interest in MMCI; and
- Notice of Disposition – seeking to initiate a public auction for Celsius’ 40% interest in MMCI.
Equinaire subsequently issued the following additional notices:
- Notice of Event of Default – claiming that certain information-security incidents involving MMCI constituted an Event of Default;
- Notice of Event of Default – claiming that Celsius’ attempt to seek protections from Philippine courts in relation to Equinaire’s attempted foreclosure itself constituted an Event of Default;
- Notice of a Resumption of Foreclosure – seeking to recommence foreclosure and the enforcement of security with respect to Celsius’ 40% interest in MMCI; and
- Notice of Disposition - seeking to proceed with a public auction of Celsius’ 40% interest in MMCI on 8 September 2026.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI.
A Petition for Interim Measures of Protection (“Petition”) was filed with a Philippine court, seeking to injunct any foreclosure of the OLSA or disposition of Celsius’ interest in MMCI until the conclusion of arbitration between the parties.
The court denied the Petition, finding that "irreparable injury” had not been sufficiently established and determining that any potential loss arising from the foreclosure could be addressed through remedies available in arbitration.
However, the court expressly stated that the denial of the Petition is not a determination that an Event of Default occurred or that Equinaire was entitled to foreclose. The Court likewise recognised that these issues remain disputed and should be addressed via arbitration. The court further emphasised that the arbitral tribunal has authority to determine the validity of any foreclosure and, where appropriate, grant interim relief.
On 8 September 2026, Equinaire proceeded to conduct the public auction for the foreclosure of MHL’s shares in MMCI, which were pledged as collateral under the OLSA.
Representatives from MHL were in attendance to put on record that any results of the foreclosure sale remain subject to the final determination of the pending arbitration between MHL and Equinaire.
Equinaire submitted a credit bid of US$5,010,000. As there were no other registered bidders in attendance and no other bids received, Equinaire was declared the winning bidder.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI. It believes that Equinaire’s claimed Events of Default should be referred to arbitration in accordance with the dispute resolution clauses within the OLSA.
Celsius is seeking to protect its interests through a combination of appeals to higher Philippine courts and by progressing arbitration to seek an injunction around the transfer of MMCI shares, to dispute the occurrence and continuance of any claimed Events of Default and to pursue damages against Equinaire.
Other
On 14 September 2026 the Company issued, following shareholder approval, 100,000,000 performance rights issued to Mr Bardin Davis.
Other
The Directors are not aware of any other matters or circumstances that have arisen since the end of the financial year which significantly affected or may significantly affect the operations of the consolidated entity, the results of those operations, or the state of affairs of the consolidated entity in future financial years.
LIKELY DEVELOPMENTS
The Directors believe, on reasonable grounds, that to include in this report particular information regarding likely developments in the operations of the company and the expected results of those operations in future financial years would be speculative and likely to result in unreasonable prejudice to the company. Accordingly, this information has not been included in this report.
ENVIRONMENTAL REGULATION
The Company’s operations are not regulated by any significant environmental regulation under a law of the Commonwealth or of a State or Territory. The Directors have considered the enacted National Greenhouse and Energy Reporting Act 2007 (the “NGER Act”) which introduces a single national reporting framework for the reporting and dissemination of information about the greenhouse gas emissions, greenhouse gas projects, and energy use and production of corporations. Given the absence of operational mining activities and the relatively low levels of energy consumption and greenhouse gas emissions associated with current activities, the Directors have determined that the Company has not met the thresholds requiring registration or reporting under the NGER Act for the current financial year. Nonetheless, Celsius has proactively initiated internal systems positioning the Company for future compliance as project development progresses. The Directors will continue to reassess this position as and when the need arises.
ANNUAL MINERAL RESOURCE AND ORE RESERVE STATEMENT
The Company updated its Mineral Resource Estimate (MRE) and issued a maiden Ore Reserve Estimate (ORE) during the year relating to its 40% interest in the MCB Project. The MRE for the Sagay Copper-Gold project was released on 6 February 2024 and the Opuwo Cobalt-Copper-Gold Project on 12 December 2022.
Review of Material Changes
On 24 November 2025 Celsius announced an updated 2012 JORC Code compliant MRE for the MCB Project of 343Mt of 0.46% copper, and 0.12g/t gold, for a total of 1.6Mt of contained copper and 1.4Moz of contained gold, reported to a cutoff grade of 0.20% copper. See table 1.
A Maiden JORC-Compliant Ore Reserve Estimate was announced for the MCB Project on 12 December 2025 with an underground gross total Ore Reserves of 130.2Mt @ 0.66% Cu and 0.21g/t Au, for 856kt of contained copper and 891 koz of contained gold at a 0.84% CuEq grade. See table 2.
There have been no material changes to the MRE tables as shown in Tables 3 and 4 below for the Sagay and Opuwo Projects.
Governance and Internal Controls
The Company has put in place governance arrangements and internal controls with respect to its estimates of Mineral Resources and the estimation process, including:
- Oversight and approval of each annual statement by responsible senior officers;
- Establishment of internal procedures and controls to meet JORC Code 2012 compliance in all external reporting; and
- Board approval of new and materially changed estimates.
Mineral Resource Estimates
MCB Copper-Gold Project, Philippines
Table 1: Comparison between the 2025 MRE and the 2022 MRE for the updated MRE at the MCB Project in the Philippines, at a cut-off grade of 0.20% copper
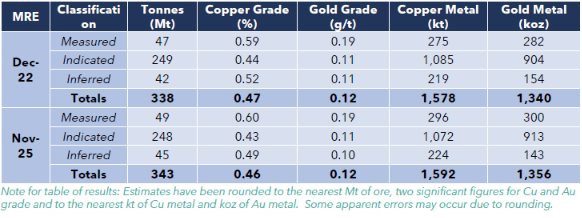
Table 2: MCB Project Ore Reserve Estimate
Sagay Copper-Gold Project, Philippines
Table 3: Summary results for the MRE at the Sagay Project in the Philippines at a cut-off grade of 0.20%
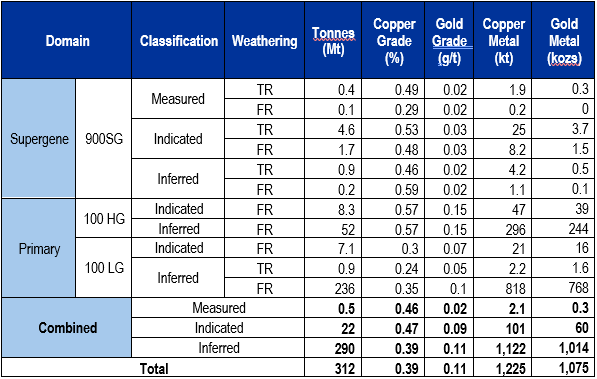
Note for table of results: Calculations have been rounded to the nearest Mt of ore (to the nearest 100,000t where <10Mt), two significant figures for Cu and Au grade and to the nearest kt of Cu metal and kozs of Au metal (to the nearest 100t where <10kt). Some apparent errors may occur due to rounding. TR – Transition or partially oxidised Rock, FR – Fresh Rock.
Opuwo Cobalt-Copper-Gold Project, Namibia
Table 4: Opuwo Cobalt Project Mineral Resources in Namibia
|
Category |
Mining Method |
Cut-off (Co eq%) |
Tonnage (Mt) |
Cobalt (%) |
Copper (%) |
Zinc (%) |
Contained Cobalt (t) |
||||
|
Indicated |
Open Pit |
0.06 |
38.0 |
0.11 |
0.45 |
0.51 |
40,600 |
||||
|
|
Underground |
0.155 |
7.3 |
0.11 |
0.41 |
0.49 |
8,000 |
||||
|
Total Indicated |
|
|
45.3 |
0.11 |
0.44 |
0.51 |
48,400 |
||||
|
Inferred |
Open Pit |
0.06 |
28.8 |
0.09 |
0.38 |
0.44 |
26,800 |
||||
|
|
Underground |
0.155 |
151.4 |
0.12 |
0.44 |
0.57 |
183,200 |
||||
|
Total Inferred |
|
|
180.2 |
0.12 |
0.43 |
0.55 |
210,800 |
||||
|
Total |
|
|
225.5 |
0.12 |
0.43 |
0.54 |
259,300 |
||||
* Note that minor rounding errors occur in this table.
Cobalt equivalent values (Coeq) were used solely to provide a guide to the cut-off grade for the resource and were calculated using the formula:
Coeq = (Cobalt% x Cobalt Recovery) + ((Copper% x Copper Recovery x (Copper$/Cobalt$)) + (Zinc% x Zinc Recovery x (Zinc$/Cobalt$))
The prices applied in the cobalt equivalent calculations above and for open pit and underground cut-off grade calculations are based upon the LME spot price on the 31st May 2021 (Copper: US$10,159/t; Cobalt: US$45,200/t; Zinc: US$3,054/t).
Competent Persons Statement
MCB Copper-Gold Project, Philippines
Information in this report relating to the reporting of Mineral Resource Estimates, Exploration Results and the Annual Mineral Resource Statement for the MCB Project is based on information compiled, reviewed and assessed by Mr. Steven Olsen, who is a Fellow of the Australasian Institute of Mining and Metallurgy and a Member of the Australian Institute of Geoscientists. Mr. Olsen is a consultant to Celsius Resources Limited and has sufficient experience which is relevant to the style of mineralisation and type of deposit under consideration and to the activity which he is undertaking to qualify as a Competent Person as defined by the 2012 Edition of the Australasian Code for reporting of Exploration Results, Mineral Resources and Ore Reserves. Mr. Olsen consents to the inclusion of the data in the form and context in which it appears.
Information in this report relating to the Ore Reserve Estimate is based on information compiled, reviewed and assessed by the following Competent Persons: Mr. Steven Olsen (Geology) from Global Geologica, Mr. John Burgess (Metallurgy) from BMECS Pty Ltd, Mr. Florian Beier (Mining) From DMT, and Mr. Matt Pyle (Process Plant and on-site infrastructure capital and operating costs) from Ausenco Australia, who are all Members of the Australasian Institute of Mining and Metallurgy. Each is a consultant through their relevant companies to Makilala Mining Company, Inc., an affiliate of Celsius Resources Limited, and has sufficient experience relevant to the style of mineralisation, the type of deposit, and mining project under consideration, the activities undertaken to qualify as a Competent Person as defined by the 2012 Edition of the Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves (JORC Code) and to be considered as a Qualified Person for the purposes of the AIM Rules.
The information in this Report with respect to the updated JORC compliant Mineral Resource Estimate for the MCB Project was announced to the ASX on 24 November 2025. The information in this Report with respect to the updated JORC compliant Ore Reserve Estimate for the MCB Project was announced to the ASX on 12 December 2025. The Company confirms that it is not aware of any new information or data that materially affects the information included in those announcements and that all material assumptions and technical parameters underpinning the Mineral Resource Estimate continue to apply and have not materially changed.
Sagay Copper-Gold Project, Philippines
Information in this Report relating to the reporting of Mineral Resource Estimates and Exploration Results, and the Annual Mineral Resource Statement for the Sagay Project, is based on information compiled, reviewed and assessed by Mr. Steven Olsen, who is a Fellow of the Australasian Institute of Mining and Metallurgy and a Member of the Australian Institute of Geoscientists. Mr. Olsen is a consultant to Celsius Resources Limited and has sufficient experience which is relevant to the style of mineralisation and type of deposit under consideration and to the activity which he is undertaking to qualify as a Competent Person as defined by the 2012 Edition of the Australasian Code for reporting of Exploration Results, Mineral Resources and Ore Reserves. Mr. Olsen consents to the inclusion of the data in the form and context in which it appears.
The information in this Report with respect to the Mineral Resource Estimate for the Sagay Project was first announced to the ASX on 7 November 2022. An updated Mineral Resource Estimate was announced to the ASX/AIM on 06 February 2024 and the Company confirms that it is not aware of any new information or data that materially affects the information included in the announcement and that all material assumptions and technical parameters underpinning the Mineral Resource Estimate continue to apply and have not materially changed.
Opuwo Cobalt-Copper-Gold Project, Namibia
The information in this Report that relates to the estimate of Mineral Resources, Exploration Results and the Annual Mineral Resource Statement for the Opuwo Project is based upon, and fairly represents, information and supporting documentation compiled by Mr Kerry Griffin, a Competent Person, who is a Member of the Australian Institute of Geoscientists (AIG). Mr Griffin is a Principal Geology Consultant at Mining Plus Pty Ltd and an independent consultant engaged by Celsius Resources Limited for this work and has sufficient experience that is relevant to the style of mineralisation and type of deposit under consideration and to the activity being undertaken to qualify as a Competent Person as defined in the 2012 edition of the “Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves” (the JORC Code). Mr Griffin consents to the inclusion in this announcement of matters based on his information in the form and context in which it appears.
INFORMATION ON DIRECTORS
|
Mr George Bujtor |
Non-Executive Chairman (appointed 14 July 2026) |
|
|
|
|
Qualifications |
B App Science & University Medal [UNSW 1973] Geology & Mining Engineering Master Mineral Economics [Macquarie Univ. 1981] Master Engineering Science in Mining Engineering [Melb. Univ. 1985] Master of Business Administration & Alan Knott Scholar [Macquarie Univ. 1989] |
|
|
|
|
Experience |
Mr Bujtor spent over 25 years with Rio Tinto, holding senior technical, development, and commercial roles in Australia. He has been predominantly based in the Philippines since 2005, and has held a series of senior roles within the Philippine mining sector, including as Managing Director of both Toledo Mining Corporation plc and Carmen Copper Corporation.
During his time with Toledo Mining, Mr Bujtor oversaw the successful funding and development of the Berong Nickel Laterite Project. As Managing Director of Carmen Copper, he led the ramp-up to full production of the rehabilitated Carmen Copper Project, the optimisation of by-product production and a US$300 million financing. |
|
|
|
|
Interest in shares, options, performance rights and warrants |
Nil
|
|
|
|
|
Directorships held in other listed entities |
None
|
|
|
|
|
Mr. Bardin Davis |
Managing Director (appointed 02 April 2026) |
|
|
|
|
Qualifications |
Bachelor of Agricultural Economics (1st Class Hons), Graduate Diploma in Accounting, Master of Applied Finance, GAICD. |
|
|
|
|
Experience |
Mr Davis has ~30 years of investment banking and corporate experience within the mining and energy sectors. He was CEO of ASX listed Peak Rare Earths Limited ("Peak") for ~5 years and is a former CFO of UPC/AC Renewables Australia (now ACEN Australia). During his banking career he spent almost 12 years in Asia and worked on a broad range of international advisory, capital market and financing transactions. He has held senior Australian and regional investment banking roles with Macquarie Capital, HSBC and ABN AMRO.
During his time with Peak, Mr Davis oversaw a project financing process, the execution of a binding offtake agreement, the securing of a special mining licence and an investment framework agreement with the Government of Tanzania, the delivery of a BFS Update and FEED Study and a sale of the company that delivered a 269% takeover premium and a ~330% premium after accounting for the value of a concurrent entitlement offer. |
|
|
|
|
Interest in shares, options, performance rights and warrants |
4,553,396 fully paid ordinary shares 100,000,000 performance rights |
|
|
|
|
Directorships held in other listed entities |
None
|
|
|
|
|
Mr Peter Hume |
Non-Executive Director |
|
|
|
|
Qualifications |
Aust. J. Civ. Eng |
|
|
|
|
Experience |
Mr. Hume has over 40 years of substantial and practical experience on major mining and construction development projects on lead roles throughout Australia and internationally. This experience has greatly helped build his proven skills in general management, project management, construction management, dispute resolution, infrastructure, and process design. He has carried out operational assignments in mining, materials handling, processing, and infrastructure where he was responsible for a range of roles from concept planning to commissioning and operations with design management, development and implementation of quality, safety, and maintenance management systems. These assignments have been demonstrated when he worked with companies such as Porgera Joint Venture, Xstrata Copper, Xstrata Coal, Anglo Coal, Glencore, Newmont Mining Corporation, BMA Coal, Kaltim Prima Coal, and Dyno Nobel, among others. |
|
|
|
|
Interest in shares, options, performance rights and warrants |
26,000,000 fully paid ordinary shares
|
|
|
|
|
Directorships held in other listed entities |
None
|
|
|
|
|
Mr Paul Dudley |
Non-Executive Director
|
|
Qualifications |
BSc (Hons), FCA, MSI
|
|
Experience |
Paul Dudley is a Fellow of the Institute of Chartered Accountants of England and Wales and is a Member of the UK's Chartered Institute of Securities and Investment. Paul founded Aer Ventures, a corporate advisory business, in 2011, where he is Managing Partner. Previously he worked at stockbroking firm WH Ireland where he was approved as a Qualified Executive acting as the Corporate Finance adviser on AIM corporate transactions.
Paul graduated from Durham University and began his career at PricewaterhouseCoopers. In addition to Celsius Resources Ltd, he is currently a director of a number of public and private companies including Pyne Gould Corporation Ltd, Watercycle Technologies Ltd and Rockwood Strategic Plc, a UK listed Investment Trust.
|
|
Interest in shares, options performance rights and warrants
|
9,375,000 fully paid ordinary shares 9,375,000 listed options exercisable at $0.01 and expiring 20 May 2028
|
|
Directorships held in other listed entities |
Pyne Gould Corporation Ltd, and Rockwood Strategic plc, a UK listed Investment Trust. |
|
|
|
|
Mr. Mark Van Kerkwijk |
Non-Executive Director (appointed 16 June 2025) |
|
|
Previously Executive Director (appointed 8 May 2024) |
|
|
|
|
Qualifications |
Master of Management, Member of AICD |
|
|
|
|
Experience |
Mr. Van Kerkwijk is an experienced investor in the resources sector and has over 30 years of project delivery for technology and security solutions across multiple industry sectors, including financial services, construction, defence and agriculture. |
|
|
|
|
Interest in shares, options, performance rights and warrants |
32,413,273 fully paid ordinary shares 9,375,000 listed options exercisable at $0.01 and expiring 20 May 2028
|
|
|
|
|
Directorships held in other listed entities |
None
|
|
|
|
|
Mr. Neil Grimes |
Executive Director (resigned 11 May 2026) |
|
Interest in shares, options, performance rights and warrants at time of resignation |
500,000 fully paid ordinary shares |
|
|
|
|
|
|
|
|
|
|
Mr Julito Sarmiento |
Executive Chairman (resigned 26 November 2025) |
|
|
|
|
Interest in shares, options, performance rights and warrants at time of resignation |
4,000,000 fully paid ordinary shares
|
|
|
|
|
Ms Attilenore Manero |
Non-Executive Sustainability Director (resigned 26 November 2025)
|
|
Interest in shares, options, performance rights and warrants at time of resignation |
21,000,000 fully paid ordinary shares |
|
|
|
COMPANY SECRETARY
Ian Hobson is a Chartered Accountant and Chartered Company Secretary with 40 years of experience in the profession. Ian was a director at PricewaterhouseCoopers for many years with experience working in Australia, UK and Canada. Ian now provides company secretary services and undertakes corporate, management and accounting positions with a number of listed public companies. Ian was appointed on 18 May 2026 following the resignation of Kellie Davis on the same date.
MEETING OF DIRECTORS
|
|
Full Board |
Nomination and Remuneration Committee |
Audit and Risk Committee |
|||
|
|
Attended |
Held |
Attended |
Held |
Attended |
Held |
|
Bardin Davis1 |
3 |
3 |
- |
- |
- |
- |
|
Peter Hume |
8 |
10 |
5 |
5 |
3 |
3 |
|
Paul Dudley |
10 |
10 |
5 |
5 |
3 |
3 |
|
Mark van Kerkwijk |
10 |
10 |
1 |
1 |
- |
- |
|
Julito Sarmiento2 |
1 |
4 |
- |
- |
- |
- |
|
Attilenore Manero2 |
3 |
4 |
1 |
1 |
1 |
1 |
|
Neil Grimes3 |
8 |
8 |
- |
- |
- |
- |
- Appointed 02 April 2026
- Resigned 26 November 2025
- Resigned 11 May 2026
REMUNERATION REPORT (AUDITED)
This report details the nature and amount of the remuneration for each key management person of Celsius Resources Limited for 30 June 2026.
Key management personnel are those persons having authority and responsibility for planning, directing and controlling the activities of the entity, directly or indirectly, including all directors.
The remuneration report is set out under the following headings:
A Principles used to determine the nature and amount of remuneration
B Details of remuneration
C Service agreements
D Share-based compensation
E Option holdings
F Shareholdings
G Performance rights holdings
H Related party disclosures
The information provided under headings A - H includes remuneration disclosures that are required under accounting Standard AASB 124 Related Party Disclosures. These disclosures have been transferred from the financial report and have been audited.
A. Principles used to determine the nature and amount of remuneration
In determining competitive remuneration rates, the Board, acting in its capacity as the remuneration committee, seeks independent advice on local and international trends among comparative companies and industry generally. It examines terms and conditions for employee incentive schemes benefit plans and share plans. Independent advice may be obtained to confirm that executive remuneration is in line with market practice and is reasonable in the context of Australian executive reward practices.
The Board recognises that Celsius Resources Limited operates in a global environment. To prosper in this environment we must attract, motivate and retain key executive staff.
Market Comparisons
Consistent with attracting and retaining talented executives, the Board endorses the use of incentive and bonus payments. The Board will continue to seek external advice to ensure reasonableness in remuneration scale and structure, and to compare the company’s position with the external market. The impact and high cost of replacing senior employees and the competition for talented executives requires the committee to reward key employees when they deliver consistently high performance.
Board Remuneration
Shareholders approve the maximum aggregate remuneration for non-executive Directors, which currently stands at $300,000 per annum, as approved by shareholders at the Annual General Meeting on 21 November 2006. The Board determines actual payments to Directors and reviews their remuneration annually based on independent external advice with regard to market practice, relativities, and the duties and accountabilities of Directors. A review of Directors’ remuneration is conducted annually to benchmark overall remuneration including retirement benefits.
Performance-based Remuneration
The Company has established a Performance Rights Plan (“PRP”) to provide ongoing incentives to Directors, executives and employees of the Company. The objective of the PRP is to provide the Company with a remuneration mechanism, through the issue of securities in the capital of the Company, to motivate and reward the performance of the Directors and employees in achieving specified performance milestones within a specified performance period. The Board will ensure that the performance milestones attached to the securities issued pursuant to the PRP are aligned with the successful growth of the Company’s business activities.
The Directors and employees of the Company have been, and will continue to be, instrumental in the growth of the Company. The Directors consider that the PRP is an appropriate method to:
- reward Directors and employees for their past performance;
- provide long term incentives for participation in the company’s future growth;
- motivate Directors and generate loyalty from senior employees; and
- assist to retain the services of valuable Directors and employees.
Group Performance, Shareholder Wealth and Directors and Executives Remuneration
The remuneration policy has been tailored to increase the direct positive relationship between shareholder’s investment objectives and Director’s and executive’s performance. Currently, Directors and executives are encouraged to hold shares in the company to ensure the alignment of personal and shareholder interests. Mr Davis was granted performance rights on 2 April 2026, subject to shareholder approval. These performance rights were issued on 14 September 2026.
The following summarises the performance of the consolidated entity over the last 5 financial years:
|
|
2026 |
2025 |
2024 |
2023 |
2022 |
|
Other income ($) |
80,147 |
795 |
647 |
28,759 |
23,127 |
|
Net loss after income tax ($) |
(23,379,327) |
(7,571,653) |
(8,438,903) |
(5,830,650) |
(3,917,778) |
|
Share price at year end (cents/share) |
0.8 |
0.7 |
1.4 |
2.4 |
1.2 |
|
Dividends paid (cents/share) |
- |
- |
- |
- |
- |
Use of remuneration consultants
During the financial year ended 30 June 2026, the Company did not engage any remuneration consultants.
Voting and comments made at the Company's 2025 Annual General Meeting ('AGM')
At the 2025 AGM, 82.76% of the votes received voted against the adoption of the remuneration report for the year ended 30 June
2025. The Company did not receive any specific feedback at the AGM regarding its remuneration practices.
B. Details of remuneration
Amounts of remuneration
The remuneration for each key management person of the Company for the year was as follows:
|
2026 |
|
|
|
|
|
|
|
|
|
Key Management Person |
Short-term Benefits |
Post- employment Benefits |
Share based Payments |
|
|
|||
|
|
Cash, salary & |
Cash profit Share |
Non-Cash |
Payments by MMCI1
|
Superannuation |
Equity |
Total |
Performance Related |
|
|
$ |
$ |
$ |
$ |
$ |
$ |
$ |
% |
|
Mr. Bardin Davis2 |
100,000 |
- |
25,000 |
- |
7,500 |
39,594 |
172,094 |
23% |
|
Mr. P Hume |
53,284 |
- |
- |
411,886 |
6,176 |
- |
471,346 |
- |
|
Mr. P Dudley |
60,000 |
- |
- |
- |
- |
- |
60,000 |
- |
|
Ms. A Manero4 |
20,000 |
- |
- |
208,117 |
- |
- |
228,117 |
- |
|
Mr. M van Kerkwijk |
63,086 |
- |
- |
- |
266 |
- |
63,352 |
- |
|
Mr. J Sarmiento4 |
41,665 |
- |
- |
304,211 |
- |
- |
345,876 |
- |
|
Mr. N Grimes3 |
185,920 |
- |
- |
- |
- |
- |
185,920 |
- |
|
|
523,955 |
- |
25,000 |
924,214 |
13,942 |
39,594 |
1,526,705 |
3% |
- Payments by MMCI were made to directors for consulting fees, detailed in related party transactions of this remuneration report.
- Appointed 2 April 2026. Prior to his appointment as Managing Director, Mr Bardin Davis was engaged as a consultant via his private company Baromoda Investment Pty Ltd for a fee of A$200 per hour capped at A$1,400 per day. Payment of fees under this Agreement was 50% paid in cash and 50% paid via the issue of fully paid ordinary shares in Celsius at the end of the three-month period from the commencement of the agreement, at the five day volume weighted average price of Celsius shares prior to the issue date. Termination requires 1-month written notice. Mr Davis was paid $7,615 and received Consideration Shares to the value of $7,615 for services provided for the period 9 January to 1 April 2026.
- Resigned 11 May 2026
- Resigned 26 November 2025
|
2025 |
|
|
|
|
|
|
|
|
|
|
Key Management Person |
|
Short-term Benefits |
Post- employment Benefits |
Share based Payments |
|
|
|||
|
|
Cash, salary & |
Cash profit Share |
Non-Cash |
Other1
|
Payments by MMCI2
|
Superannuation |
Equity |
Total |
Performance Related |
|
|
$ |
$ |
$ |
$ |
$ |
$ |
$ |
$ |
% |
|
Mr. J Sarmiento |
99,996 |
- |
- |
- |
420,612 |
- |
- |
520,608 |
- |
|
Mr. N Grimes3 |
21,671 |
- |
- |
- |
- |
- |
- |
21,671 |
- |
|
Mr. P Hume |
118,966 |
- |
- |
- |
478,653 |
5,520 |
- |
603,139 |
- |
|
Mr. P Dudley4 |
60,000 |
- |
- |
150,000 |
- |
- |
- |
210,000 |
- |
|
Ms. A Manero |
83,482 |
- |
- |
- |
241,657 |
- |
- |
325,139 |
- |
|
Mr. M van Kerkwijk5 |
48,000 |
- |
- |
153,313 |
- |
5,520 |
- |
206,833 |
- |
|
|
432,115 |
- |
- |
303,313 |
1,140,922 |
11,040 |
- |
1,887,390 |
- |
- Payments by Celsius were made to directors for additional consulting fees, detailed in related party transactions of this remuneration report.
- Payments by MMCI were made to directors for consulting fees, detailed in related party transactions of this remuneration report.
- Appointed as Executive Director on 16 June 2025 (previously Non-Executive Director from 17 March 2025).
- During the year ended 30 June 2025,$75,000 of accrued and unpaid director fees were satisfied by the issue of 9,375,000 fully paid ordinary shares and 4,687,500 free attaching listed options exercisable at $0.01 each and expiring on 20 May 2028, on the same terms as the March 2025 placement (2024: Nil). The listed options issued to Mr P Dudley vested immediately.
- Appointed as Non-Executive Director on 16 June 2025 (previously Executive Director from 8 May 2024).
C. Service agreements
On 2 April 2026, Mr Bardin Davis was appointed Managing Director. An executive services agreement was entered into with Mr Davis. Refer to Employment Contracts of Key Management Personnel section below for further information.
From 1 December 2024 to 31 December 2025 Ms. Manero had a consultancy agreement in place with the Group's affiliate, Makilala Mining Company Inc. (“MMCI”) to perform services as "Chief Sustainability Officer" which was converted into a 5-year employment contract as a condition of the OLSA until terminated in April 2026. From 16 May 2025 Ms. Manero was an employee of MMCI until terminated in April 2026. On 9 June 2026, the Company’s wholly owned subsidiary Tambuli Mining Company, Inc. retained
Ms. Manero pursuant to a consultancy agreement terminating 31 December 2026. Refer to Employment Contracts of Key Management Personnel section below for further information.
Mr. Peter Hume was engaged as a consultant to MMCI as a Director and Consultant in the Philippines which concluded in April 2026.
Mr. Julito Sarmiento provided consultancy services to MMCI.
Mr. Neil Grimes (resigned 11 May 2026) entered into a consultancy agreement with Celsius Resources Limited on his appointment as Executive Director on 16 June 2025.
Employment Contracts of Key Management Personnel
Each member of the Company’s key management personnel is employed on open-ended employment contracts between the individual person and the Group.
Non-Executive Directors have entered into a service agreement with the Group in the form of a letter of appointment.
The below is as at the date of the financial report:
|
Key Management Person |
Appointment |
Term of Agreement |
Base Salary including superannuation (excludes GST) $ p.a. |
Termination Benefit |
|
George Bujtor1 |
Non-Executive Chair |
No fixed term |
100,000 |
Nil |
|
Bardin Davis2 |
Managing Director |
No fixed term |
530,000 |
Nil |
|
Peter Hume3 |
Non-Executive Director |
No fixed term |
53,760 plus USD5,000PM |
Nil |
|
Paul Dudley |
Non-Executive Director |
No fixed term |
60,000 |
Nil |
|
Mark van Kerkwijk |
Non-Executive Director |
No fixed term |
53,760 |
Nil |
- Mr George Bujtor was appointed on 14 July 2026
- Mr Bardin Davis is engaged pursuant to an executive services agreement at $530,000 per annum of which $100,000 will be paid by share issuance less applicable tax.
- Mr Peter Hume is considered a Non-Executive Director and receives USD 5,000 per month as a consultant to TMCI and a Non-Executive Director fee from the Company of $53,760.
D. Share-based compensation
Options, Performance Rights and Warrants
The terms and conditions of each grant of performance rights, options and warrants over ordinary shares affecting remuneration of Directors and other key management personnel in this financial year or future reporting years are as follows:
|
Name |
Number of rights granted |
Vesting conditions |
Grant date |
Expiry date |
Fair value per right at grant date $ |
|
Mr B Davis |
6,250,000 |
A(1) |
02/04/2026 |
18 months from the date of issue |
0.0070 |
|
Mr B Davis |
18,750,000 |
A(2) |
02/04/2026 |
24 months from the date of issue |
0.0070 |
|
Mr B Davis |
10,000,000 |
B |
02/04/2026 |
48 months from the date of issue |
0.0070 |
|
Mr B Davis |
15,000,000 |
C |
02/04/2026 |
12 months from the date of issue |
0.0070 |
|
Mr B Davis |
10,000,000 |
D |
02/04/2026 |
12 months from the date of issue |
0.0037 |
|
Mr B Davis |
20,000,000 |
E |
02/04/2026 |
24 months from the date of issue |
0.0046 |
|
Mr B Davis |
20,000,000 |
F |
02/04/2026 |
36 months from the date of issue |
0.0045 |
A(1) - In respect of the Company’s MCB Project, announcement to ASX of a positive final investment decision supported by binding financing arrangements.
A(2) - In respect of the Company’s MCB Project, announcement to ASX of a positive final investment decision supported by binding financing arrangements.
B - In respect of the Company’s MCB Project, announcement to ASX of completion of construction to a point where commissioning of the process plant has been achieved with the first concentrate road freight shipment to the port completed.
C - Announcement to ASX of the completion of the sale of the Opuwo Project.
D - The Company’s Shares achieving a 20-Day VWAP of $0.015 or greater from the issue date of the Performance Rights to 12 months from the date of issue.
E - The Company’s Shares achieving a 20-Day VWAP of $0.020 or greater from the issue date of the Performance Rights to 24 months from the date of issue.
F - The Company’s Shares achieving a 20-Day VWAP of $0.030 or greater from the issue date of the Performance Rights to 36 months from the date of issue.
Pursuant to the terms of Mr Davis’ appointment as Managing Director, the Company granted, subject to the prior receipt of Shareholder approval which was received on 9 September 2026, to issue up to 100,000,000 Performance Rights to Mr Davis as above (which all were unvested as at 30 June 2026). Unvested Performance Rights lapse on leaving employment and vested Performance Rights lapse 1 month after leaving employment.
The value disclosed in the remuneration of key management personnel is the portion of the fair value of the share-based payments that is recognised as expense in each reporting period in accordance with the requirement of AASB 2.
Shares
During the year ended 30 June 2026, Directors Bardin Davis (1,250,000 shares) and Neil Grimes (500,000 shares) participated in the Placement announced on 23 February 2026 on the same terms as unrelated parties, as approved by shareholders on 30 April 2026. Also during the year ended 30 June 2026, Mr Bardin Davis was issued 846,111 fully paid ordinary shares in lieu of consultancy fees prior to his appointment as a director.
E. Option holdings
The number of options over ordinary shares in the Company held during the financial year by each Director and other members of key management personnel of the consolidated entity, including their personally related parties, is set out below:
|
30 June 2026 |
Balance at beginning of the year |
Granted during the year |
Acquired on-market or as part of capital raising |
Expiry of options |
Other changes |
Balance at end of year |
|
Mr. B Davis |
- |
- |
- |
- |
- |
- |
|
Mr. J Sarmiento1 |
- |
- |
- |
- |
- |
- |
|
Mr. Neil Grimes2 |
- |
- |
- |
- |
- |
- |
|
Mr. P Hume |
- |
- |
- |
- |
- |
- |
|
Mr. P Dudley3 |
4,687,500 |
- |
- |
- |
4,687,500 |
9,375,000 |
|
Ms. A Manero1 |
- |
- |
- |
- |
- |
- |
|
Mr. M van Kerkwijk |
4,687,500 |
- |
- |
- |
4,687,500 |
9,375,000 |
|
|
9,375,000 |
- |
- |
- |
9,375,000 |
18,750,000 |
- Resigned 26 November 2025.
- Resigned 11 May 2026.
- Additional options issued on the same terms as unrelated parties approved by shareholders on 5 August 2026.
F. Shareholdings
The number of shares in the Company held during the financial year by each Director and other members of key management personnel of the consolidated entity, including their personally related parties, is set out below:
|
30 June 2026 |
Balance at beginning of the year |
Conversion of performance rights |
Acquired on-market or as part of capital raising3 |
Other changes4 |
Balance at end of year/ resignation |
|
Mr. B Davis |
- |
- |
1,250,000 |
846,111 |
2,096,111 |
|
Mr. J Sarmiento1 |
4,000,000 |
- |
- |
- |
4,000,000 |
|
Mr. N Grimes2 |
- |
- |
500,000 |
- |
500,000 |
|
Mr. P Hume |
26,000,000 |
- |
- |
- |
26,000,000 |
|
Mr. P Dudley |
9,375,000 |
- |
- |
- |
9,375,000 |
|
Ms. A Manero1 |
21,000,000 |
- |
- |
- |
21,000,000 |
|
Mr. Mark van Kerkwijk |
32,413,273 |
- |
- |
- |
32,413,273 |
|
|
92,788,273 |
- |
1,750,000 |
846,111 |
95,384,384 |
- Resigned 26 November 2025.
- Resigned 11 May 2026.
- Participation in the Placement announced on 23 February 2026 on the same terms as unrelated parties, as approved by shareholders on 30 April 2026.
- In lieu of consultancy fees prior to his appointment as director.
G. Performance rights holdings
|
30 June 2026 |
Balance at beginning of the year |
Granted during the year |
Converted to ordinary shares |
Expiry of Performance Rights |
Other changes |
Balance at end of year |
|
Mr. Bardin Davis1 |
- |
100,000,000 |
- |
- |
- |
100,000,000 |
|
Mr. J Sarmiento |
- |
- |
- |
- |
- |
- |
|
Mr. N. Grimes |
- |
- |
- |
- |
- |
- |
|
Mr. P Hume |
- |
- |
- |
- |
- |
- |
|
Mr. P Dudley |
- |
- |
- |
- |
- |
- |
|
Ms. A Manero |
- |
- |
- |
- |
- |
- |
|
Mr. M van Kerkwijk |
- |
- |
- |
- |
- |
- |
|
|
- |
100,000,000 |
- |
- |
- |
100,000,000 |
- Granted to Bardin Davis on execution of executive services agreement on 2 April 2026. Approved by shareholders on 9 September 2026.
H. Warrants holdings
|
30 June 2026 |
Balance at beginning of the year |
Warrants on initial appointment |
Warrants issued |
Converted to ordinary shares |
Expiry of Warrants |
Other changes |
Balance at end of year |
|
Mr. Bardin Davis |
|
|
|
|
|
|
|
|
Mr. J Sarmiento |
- |
- |
- |
- |
- |
- |
- |
|
Mr. N. Grimes |
- |
- |
- |
- |
- |
- |
- |
|
Mr. P Hume |
- |
- |
- |
- |
- |
- |
- |
|
Mr. P Dudley |
10,000,000 |
- |
- |
- |
(10,000,000) |
- |
- |
|
Ms. A Manero |
- |
- |
- |
- |
- |
- |
- |
|
Mr. M van Kerkwijk |
- |
- |
- |
- |
- |
- |
- |
|
|
10,000,000 |
- |
- |
- |
(10,000,000) |
- |
- |
I. Related party disclosures
- Transactions with related parties
During the year, Bardin Davis was paid managing director fees of $100,000 plus superannuation of $7,500. A further $25,000 accrued for consideration shares and taxation obligations (approved at the EGM on 9 September 2026) plus $39,594 recognised as the expense of performance rights approved by shareholders on 9 September 2026.
During the year, Julito Sarmiento was paid director and consultancy fees. The group paid Mr Julito Sarmiento $41,665 for director fees and $304,211 for consultancy services.
During the year, payments were made to Mannerim Capital Pty Ltd, a company in which Mr Grimes is a shareholder and Director. Payments were made to the company for director fees to the value of $185,920.
During the year, payments were made to Peter Hume for director fees and consultancy services. Payments were for the value of $471,346.
During the year, payments were made to Skyhill Partners Ltd, a company in which Mr Dudley is a shareholder and Director. Payments were made to this company for consultancy services to the value of $60,000.
During the year, payments were made to Attilenore P. Manero for director fees and consultancy services. Payments were for the value of $228,117.
During the year, payments were made to Hybrid FS Pty Ltd, a company in which Mr Mark van Kerkwijk is a shareholder and Director. Payments were made to this company for director fees to the value of $63,352.
There were no other transactions with related parties.
- Payables owing to related parties
|
|
2026 $ |
2025 $ |
|
Bardin Davis |
437 |
- |
|
Julito Sarmiento |
- |
634,287 |
|
Mannerim Capital Pty Ltd |
- |
11,671 |
|
Peter Hume |
- |
565,069 |
|
Skyhill Partners Ltd |
15,000 |
25,000 |
|
Attilenore P. Manero |
- |
4,000 |
|
Hybrid FS Pty Ltd |
5,980 |
8,363 |
|
|
21,417 |
1,248,390 |
- Receivables from related parties
There are no receivables from related parties at 30 June 2026 (2025: Nil).
This concludes the remuneration report, which has been audited.
SHARES UNDER OPTION AND WARRANTS
The Company has 421,577,913 listed options on issue exercisable at $0.01 per share and 33,673,355 unlisted options on issue exercisable at $0.025 per share.
The Company also has 236,101,390 unlisted warrants on issue at the date of this report and are exercisable at GBP 0.005-0.009 per share. 181,694,414 expire on 26 December 2026, 36,606,976 expire on 31 December 2026, 12,500,000 expire on 28 April 2028 and 5,300,000 expire on 19 November 2028.
No person entitled to exercise the options or warrants had or has any right by virtue of the option to participate in any share issue of the company or of any other body corporate.
SHARES ISSUED ON THE EXERCISE OF OPTIONS AND WARRANTS
During the year, and up to the date of this report, 2,372,157 shares were issued on the exercise of options (2025: Nil) and 12,500,000 shares were issued on the exercise of warrants (2025: Nil).
SHARES ISSUED ON THE EXERCISE OF PERFORMANCE RIGHTS
During the year and up to the date of this report, no performance rights were exercised (2025: Nil).
INDEMNITY AND INSURANCE OF OFFICERS
The company has indemnified the Directors and executives of the Company for the costs incurred, in their capacity as a Director or executive, for which they may be held personally liable, except where there is a lack of good faith. During the financial year, the Company paid a premium in respect of a contract to insure the Directors and executives of the company against a liability to the extent permitted by the Corporations Act 2001. The contract of insurance prohibits disclosure of the nature of liability and the amount of the premium.
INDEMNITY AND INSURANCE OF AUDITOR
The Company has not, during or since the end of the financial year, indemnified or agreed to indemnify the auditor of the Company or any related entity against a liability incurred by the auditor. During the financial year, the Company has not paid a premium in respect of a contract to insure the auditor of the Company or any related entity.
PROCEEDINGS ON BEHALF OF THE COMPANY
No person has applied to the Court under section 237 of the Corporations Act 2001 for leave to bring proceedings on behalf of the Company, or to intervene in any proceedings to which the company is a party, for the purpose of taking responsibility on behalf of the Company for all or part of those proceedings. No proceedings have been brought or intervened in on behalf of the Company with leave of the Court under section 237 of the Corporations Act 2001.
NON-AUDIT SERVICES
The Board of Directors is satisfied that the provision of non-audit services during the year is compatible with the general standard of independence for auditors imposed by the Corporations Act 2001. The Directors are satisfied that the services disclosed below did not compromise the external auditor’s independence for the following reasons:
- all non-audit services are reviewed and approved by the Directors prior to commencement to ensure they do not adversely affect the integrity and objectivity of the auditor; and
- the nature of the services provided does not compromise the general principles relating to auditor independence in accordance with APES 110: Code of Ethics for Professional Accountants set by the Accounting Professional and Ethical Standards Board.
Non-audit services that have been provided by the entity’s auditor, Grant Thornton Audit Pty Ltd as well as the Company’s previous auditor, RSM Australia Partners, have been disclosed in Note 23.
OFFICERS OF THE COMPANY WHO ARE FORMER PARTNERS OF GRANT THORNTON AUDIT PTY LTD
There are no officers of the Company who are former partners of Grant Thornton Audit Pty Ltd.
AUDITOR
Grant Thornton Audit Pty Ltd replaced RSM Australia Partners during the financial year.
AUDITOR’S INDEPENDENCE DECLARATION
A copy of the auditor’s independence declaration as required under section 307C of the Corporations Act 2001 is included within this financial report.
This Directors’ report, incorporating the remuneration report, is signed in accordance with a resolution of the Board of Directors.
This Directors’ report is signed in accordance with a resolution of Directors made pursuant to section 298(2)(a) of the Corporations Act 2001.
On behalf of the Directors
Bardin Davis
Managing Director
Date: 30 September 2026
|
Perth |
|
|
Notes |
2026 |
2025 |
|
|
|
$ |
$ |
|
|
|
|
|
|
Other income |
3 |
80,147 |
795 |
|
Gain on disposal of subsidiary |
25 |
13,270,366 |
- |
|
Directors’ and employee benefits expense |
|
(570,311) |
(344,044) |
|
Legal and other professional fees |
|
(1,819,572) |
(954,160) |
|
Travel and accommodation |
|
(118,624) |
(42,174) |
|
Depreciation and amortisation expense |
|
(82,013) |
(48,540) |
|
Finance costs |
|
(70,281) |
(49,119) |
|
Share based payments |
|
(39,594) |
- |
|
Impairment expense |
13,14 |
(30,680,889) |
(125,962) |
|
Project costs |
|
(1,628,448) |
(333,636) |
|
Foreign exchange (loss)/gain |
|
(29,625) |
(833) |
|
Share of loss of associate |
|
(696,799) |
- |
|
Other expenses |
4 |
(951,227) |
(1,121,856) |
|
Loss before income tax expenses from continuing operations |
|
(23,336,870) |
(3,019,529) |
|
Income tax expense |
5 |
- |
- |
|
Loss after income tax expenses from continuing operations |
|
(23,336,870) |
(3,019,529) |
|
Loss after income tax expense from discontinued operations |
9 |
(42,457) |
(4,552,124) |
|
Loss after income tax expense for the year |
|
(23,379,327) |
(7,571,653) |
|
|
|
|
|
|
Other comprehensive income Items that may be reclassified subsequently to operating result |
|
|
|
|
Exchange differences on translating foreign controlled entities |
|
(2,049,608) |
402,921 |
|
Reclassified to profit or loss on loss of control of subsidiary |
|
1,024,724 |
- |
|
Other comprehensive income for the year |
|
(1,024,884) |
402,921 |
|
Total comprehensive loss for the year |
|
(24,404,211) |
(7,168,732) |
|
|
|
|
|
|
Profit/(Loss) for the year is attributable to: |
|
|
|
|
Members of the parent entity |
|
(23,379,327) |
(7,569,867) |
|
Non-controlling interest |
|
- |
(1,786) |
|
|
|
(23,379,327) |
(7,571,653) |
|
|
|
|
|
|
Total comprehensive profit/(loss) attributable to: |
|
|
|
|
Non-controlling interest - Continuing operations |
|
- |
- |
|
Non-controlling interest - Discontinued operations |
|
(68) |
(1,015) |
|
|
|
(68) |
(1,015) |
|
|
|
|
|
|
Total comprehensive profit/(loss) attributable to: |
|
|
|
|
Member of the parent entity - Continuing operations |
|
(24,404,143) |
(7,167,717) |
|
Member of parent entity - Discontinued operations |
|
- |
- |
|
|
|
(24,404,143) |
(7,167,717) |
|
|
|
(24,404,211) |
(7,168,732) |
|
Earnings per share for loss from continuing operations attributable to the owners of Celsius Resources Limited |
|
|
|
|
- Basic earnings per share (cents) |
28 |
(0.69) |
(0.11) |
|
- Diluted earnings per share (cents) |
28 |
(0.69) |
(0.11) |
|
Earnings per share for loss from discontinued operations attributable to the owners of Celsius Resources Limited |
|
|
|
|
- Basic earnings per share (cents) |
28 |
(0.00) |
(0.17) |
|
- Diluted earnings per share (cents) |
28 |
(0.00) |
(0.17) |
|
Earnings per share for loss attributable to the owners of Celsius Resources Limited |
|
|
|
|
Basic earnings per share (cents) |
28 |
(0.69) |
(0.28) |
|
Diluted earnings per share (cents) |
28 |
(0.69) |
(0.28) |
The accompanying notes form part of this financial report.
|
|
|
Consolidated |
|
|
|
Notes |
2026 |
2025 |
|
|
|
$ |
$ |
|
ASSETS |
|
|
|
|
Current assets |
|
|
|
|
Cash and cash equivalents |
6 |
7,204,425 |
4,368,851 |
|
Trade and other receivables |
7 |
11,693 |
38,826 |
|
Other assets |
8 |
135,650 |
158,645 |
|
|
|
7,351,768 |
4,566,322 |
|
Fixed assets classified as held for sale |
10 |
3,230 |
3,159 |
|
Assets of disposal groups classified as held for sale |
11 |
3,020,744 |
3,042,006 |
|
Total current assets |
|
10,375,742 |
7,611,487 |
|
|
|
|
|
|
Non-current assets |
|
|
|
|
Exploration and evaluation |
12 |
2,223,843 |
23,635,393 |
|
Mine development |
|
- |
444,831 |
|
Property, plant and equipment |
|
3,023 |
264,876 |
|
Right of use asset |
|
- |
143,016 |
|
Financial asset |
13 |
- |
- |
|
Investment in associate |
14 |
- |
- |
|
Total non-current assets |
|
2,226,866 |
24,488,116 |
|
|
|
|
|
|
Total assets |
|
12,602,608 |
32,099,603 |
|
|
|
|
|
|
LIABILITIES |
|
|
|
|
Current liabilities |
|
|
|
|
Trade and other payables |
15 |
416,670 |
693,645 |
|
Other liabilities |
16 |
218,059 |
1,699,220 |
|
Lease liabilities |
|
- |
33,592 |
|
Liabilities directly associated with assets classified as held for sale |
17 |
38,205 |
49,680 |
|
Total current liabilities |
|
672,934 |
2,476,137 |
|
|
|
|
|
|
Non-current liabilities |
|
|
|
|
Loans and borrowings |
18 |
- |
3,073,552 |
|
Lease liabilities |
|
- |
98,009 |
|
Total non-current liabilities |
|
- |
3,171,561 |
|
|
|
|
|
|
Total liabilities |
|
672,934 |
5,647,698 |
|
|
|
|
|
|
Net assets |
|
11,929,674 |
26,451,905 |
|
|
|
|
|
|
EQUITY |
|
|
|
|
Issued capital |
19 |
95,660,856 |
85,852,075 |
|
Reserves |
20 |
(2,235,205) |
(1,283,588) |
|
Accumulated losses |
|
(81,495,176) |
(58,115,849) |
|
Equity attributable to the owners of Celsius Resources Limited |
|
11,930,475 |
26,452,638 |
|
Non-controlling interest |
|
(801) |
(733) |
|
Total equity |
|
11,929,674 |
26,451,905 |
The accompanying notes form part of this financial report.
|
|
Issued Capital |
Accumulated Losses |
Share Based Payment Reserve |
Foreign Currency Translation Reserve |
Non-Controlling Interest |
Total |
|
|
$ |
$ |
$ |
$ |
$ |
$ |
|
Balance at 1 July 2025 |
85,852,075 |
(58,115,849) |
1,038,450 |
(2,322,038) |
(733) |
26,451,905 |
|
Loss for the year |
- |
(23,379,327) |
- |
- |
- |
(23,379,327) |
|
Other comprehensive loss |
- |
- |
- |
(1,024,816) |
(68) |
(1,024,884) |
|
Total comprehensive loss for the year |
- |
(23,379,327) |
- |
(1,024,816) |
(68) |
(24,404,211) |
|
Transactions with owners, directly in equity |
|
|
|
|
|
|
|
Issue of share capital |
10,515,472 |
- |
- |
- |
- |
10,515,472 |
|
Capital raising costs |
(673,086) |
- |
- |
- |
- |
(673,086) |
|
Share based payments |
(33,605) |
- |
73,199 |
- |
- |
39,594 |
|
Balance at 30 June 2026 |
95,660,856 |
(81,495,176) |
1,111,649 |
(3,346,854) |
(801) |
11,929,674 |
|
|
|
|
|
|
|
|
|
Balance at 1 July 2024 |
81,188,958 |
(50,545,982) |
502,759 |
(2,722,158) |
(1,748) |
28,421,829 |
|
Loss for the year |
- |
(7,569,867) |
- |
- |
(1,786) |
(7,571,653) |
|
Other comprehensive loss |
- |
- |
- |
400,120 |
2,801 |
402,921 |
|
Total comprehensive loss for the year |
- |
(7,569,867) |
- |
400,120 |
1,015 |
(7,168,732) |
|
Transactions with owners, directly in equity |
|
|
|
|
|
|
|
Issue of share capital |
5,737,295 |
- |
- |
- |
- |
5,737,295 |
|
Capital raising costs |
(1,074,178) |
- |
535,691 |
- |
- |
(538,487) |
|
Share based payments |
- |
- |
- |
- |
- |
- |
|
Balance at 30 June 2025 |
85,852,075 |
(58,115,849) |
1,038,450 |
(2,322,038) |
(733) |
26,451,905 |
The accompanying notes form part of this financial report.
|
|
|
Consolidated |
|
|
|
Notes |
2026 |
2025 |
|
|
|
$ |
$ |
|
Cash flows from operating activities |
|
|
|
|
Interest received |
|
80,110 |
- |
|
Payments to suppliers and employees |
|
(5,324,614) |
(2,306,626) |
|
Net cash outflow from operating activities |
29 |
(5,244,504) |
(2,306,626) |
|
Cash flows from investing activities |
|
|
|
|
Payments for property, plant and equipment. |
|
(147,697) |
(55,493) |
|
Payments for exploration and evaluation |
|
(11,038,726) |
(3,245,881) |
|
Cash derecognised on deconsolidation |
|
(635,374) |
- |
|
Net cash outflow from investing activities |
|
(11,821,797) |
(3,301,374) |
|
Cash flows from financing activities |
|
|
|
|
Proceeds from issue of shares |
|
10,480,472 |
5,770,968 |
|
Payment of capital raising costs |
|
(658,761) |
(568,808) |
|
Proceeds from loans |
|
10,294,311 |
3,248,609 |
|
Net cash inflow from financing activities |
|
20,116,022 |
8,450,769 |
|
|
|
|
|
|
Net increase/ (decrease) in cash and cash equivalents |
|
3,049,721 |
2,842,769 |
|
Effect of exchange rate changes on the balance of cash held in foreign currencies |
|
(214,147) |
(73,643) |
|
Cash and cash equivalents at the beginning of the financial year |
|
4,368,851 |
1,599,725 |
|
Cash and cash equivalents at the end of the financial year |
6 |
7,204,425 |
4,368,851 |
|
|
|
|
|
The accompanying notes form part of this financial report.
These consolidated financial statements and notes represent those of Celsius Resources Limited and its controlled entities (the “consolidated entity” or “Group”).
The financial statements were authorised for issue on XX September 2026 by the Directors of the Company.
- Material accounting policy information
Basis of preparation
The financial statements are general purpose financial statements that have been prepared in accordance with Corporations Act 2001, Australian Accounting Standards, Interpretations of the Australian Accounting Standards Board and International Financial Reporting Standards as issued by the International Accounting Standards Board. The consolidated entity is a for-profit entity for financial reporting purposes under Australian Accounting Standards. Material accounting policies adopted in the preparation of these financial statements are presented below and have been consistently applied unless otherwise stated. Except for cash flow information, these financial statements have been prepared on an accruals basis and are based on historical costs, modified, where applicable, by the measurement at fair value of selected non-current assets, financial assets and financial liabilities.
Going concern
The financial statements have been prepared on the going concern basis that contemplates the continuity of normal business activities and the realisation of assets and extinguishment of liabilities in the ordinary course of business.
At 30 June 2026, the Group held cash and cash equivalents of $7.2 million. The directors have reviewed the Group’s cash flow forecasts covering the period 12 months from the date these financial statements are authorised for issue. The forecasts incorporate existing cash resources, exploration, taxation, corporate and working capital expenditure.
Based on these forecasts, the directors have concluded that the Group has sufficient financial resources to meet its obligations as and when they fall due. Accordingly, the directors consider it appropriate to prepare the consolidated financial statements on a going concern basis.
a) Comparatives
When required by accounting standards, comparative figures have been adjusted to conform to changes in presentation for the current financial year.
b) Principles of consolidation
The consolidated financial statements incorporate the assets and liabilities of all subsidiaries of Celsius Resources Limited as at 30 June 2026 and the results of all subsidiaries for the year then ended. Celsius Resources Limited and its subsidiaries together are referred to in these financial statements as the 'consolidated entity', ‘Consolidated Group’ or the ‘Group’.
Subsidiaries are all those entities over which the Company has control. The Company controls an entity when the Company is exposed to, or has rights to, variable returns from its involvement with the entity and has the ability to affect those returns through its power to direct the activities of the entity. Subsidiaries are fully consolidated from the date on which control is transferred to the Company. They are de-consolidated from the date that control ceases.
Intercompany transactions, balances and unrealised gains on transactions between entities in the Company are eliminated. Unrealised losses are also eliminated unless the transaction provides evidence of the impairment of the asset transferred. Accounting policies of subsidiaries have been changed where necessary to ensure consistency with the policies adopted by the Company.
The acquisition of subsidiaries is accounted for using the acquisition method of accounting. A change in ownership interest, without the loss of control, is accounted for as an equity transaction, where the difference between the consideration transferred and the book value of the share of the non-controlling interest acquired is recognised directly in equity attributable to the parent.
Where the Company loses control over a subsidiary, it derecognises the assets including goodwill, liabilities and non
controlling interest in the subsidiary together with any cumulative translation differences recognised in equity. The
Company recognises the fair value of the consideration received and the fair value of any investment retained together
with any gain or loss in profit or loss.
c) Parent entity
In accordance with the Corporations Act 2001, these financial statements present the results of the consolidated entity only. Supplementary information about the parent entity is disclosed in Note 30.
- Material accounting policy (continued)
d) Income tax
The income tax expense (revenue) for the year comprises current income tax expense (income) and deferred tax expense (income).
Deferred income tax expense reflects movements in deferred tax asset and deferred tax liability balances during the year as well as unused tax losses.
Current and deferred income tax expense (income) is charged or credited directly to equity instead of the profit or loss when the tax relates to items that are credited or charged directly to equity.
Deferred tax assets and liabilities are ascertained based on temporary differences arising between the tax bases of assets and liabilities and their carrying amounts in the financial statements. Deferred tax assets also result where amounts have been fully expensed but future tax deductions are available. No deferred income tax will be recognised from the initial recognition of an asset or liability, excluding a business combination, where there is no effect on accounting or taxable profit or loss.
Deferred tax assets and liabilities are calculated at the tax rates that are expected to apply to the period when the asset is realised or the liability is settled, based on tax rates enacted or substantively enacted at the end of the reporting period. Their measurement also reflects the manner in which management expects to recover or settle the carrying amount of the related asset or liability.
Deferred tax assets relating to temporary differences and unused tax losses are recognised only to the extent that it is probable that future taxable profit will be available against which the benefits of the deferred tax asset can be utilised.
Where temporary differences exist in relation to investments in subsidiaries, branches, associates, and joint ventures, deferred tax assets and liabilities are not recognised where the timing of the reversal of the temporary difference can be controlled and it is not probable that the reversal will occur in the foreseeable future.
Current tax assets and liabilities are offset where a legally enforceable right of set-off exists and it is intended that net settlement or simultaneous realisation and settlement of the respective asset and liability will occur. Deferred tax assets and liabilities are offset where a legally enforceable right of set-off exists, the deferred tax assets and liabilities relate to income taxes levied by the same taxation authority on either the same taxable entity or different taxable entities where it is intended that net settlement or simultaneous realisation and settlement of the respective asset and liability will occur in future periods in which significant amounts of deferred tax assets or liabilities are expected to be recovered or settled.
Tax consolidation
Celsius Resources Limited and its wholly-owned Australian subsidiaries have formed an income tax consolidated group under the tax consolidation legislation. Each entity in the consolidated entity recognises its own current and deferred tax liabilities, except for any deferred tax liabilities resulting from unused tax losses and tax credits, which are immediately assumed by the parent entity. The consolidated entity notified the Australian Tax Office that it had formed an income tax consolidated group to apply from 12 August 2003. The tax consolidated group has entered a tax sharing agreement whereby each company in the consolidated entity contributes to the income tax payable in proportion to their contribution to the net profit before tax of the tax consolidated group.
e) Trade and other receivables
Trade receivables are initially recognised at fair value and subsequently measured at amortised cost, using the effective interest method, less any allowances for expected credit losses. Trade receivables are generally due for settlement within 120 days.
The consolidated entity has applied the simplified approach to measuring expected credit losses, which uses a lifetime expected loss allowance. To measure the expected losses, trade receivables have been grouped based on days overdue.
Other receivables are recognised at amortised cost, less any allowance for expected credit losses.
- Material accounting policy (continued)
f) Plant and equipment
Plant and equipment is stated at historical cost less accumulated depreciation and impairment. Historical cost includes expenditure that is directly attributable to the acquisition of the items.
Depreciation is calculated on a straight-line basis to write off the net cost of each item of property, plant and equipment (excluding land) over their expected useful lives as follows:
|
Plant and equipment |
|
3-10 years |
|
Motor vehicles |
|
5 years |
|
Furniture and fixtures |
|
5-10 years |
The residual values, useful lives and depreciation methods are reviewed, and adjusted if appropriate, at each reporting date.
An item of property, plant and equipment is derecognised upon disposal or when there is no future economic benefit to the consolidated entity. Gains and losses between the carrying amount and the disposal proceeds are taken to profit or loss.
g) Impairment of assets
At the end of each reporting period, the consolidated entity assesses whether there is any indication that an asset is impaired. The assessment will include the consideration of external and internal sources of information including dividends received from subsidiaries, associates or jointly controlled entities deemed to be out of pre-acquisition profits. If such an indication exists, an impairment test is carried out on the asset by comparing the recoverable amount of the asset, being the higher of the asset’s fair value less costs to sell and value in use, to the asset’s carrying value. Any excess of the asset’s carrying value over its recoverable amount is recognised immediately in the profit or loss.
Where it is not possible to estimate the recoverable amount of an individual asset, the consolidated entity estimates the recoverable amount of the cash-generating unit to which the asset belongs.
h) Current and non-current classification
Assets and liabilities are presented in the statement of financial position based on current and non-current classification.
An asset is classified as current when: it is either expected to be realised or intended to be sold or consumed in normal operating cycle; it is held primarily for the purpose of trading; it is expected to be realised within 12 months after the reporting period or the asset is cash or cash equivalent unless restricted from being exchanged or used to settle a liability for at least 12 months after the reporting period. All other assets are classified as non-current.
A liability is classified as current when: it is either expected to be settled in the normal operating cycle; it is held primarily for the purpose of trading; it is due to be settled within 12 months after the reporting period; or the entity does not have the right at the end of the reporting period to defer settlement of the liability for at least 12 months after the reporting period. All other liabilities are classified as non-current.
i) Exploration and evaluation expenditure
Exploration and evaluation expenditure in relation to separate areas of interest for which rights of tenure are current is carried forward as an asset in the statement of financial position where it is expected that the expenditure will be recovered through the successful development and exploitation of an area of interest, or by its sale; or exploration activities are continuing in an area and activities have not reached a stage which permits a reasonable estimate of the existence or otherwise of economically recoverable reserves.
Where a project or an area of interest has been abandoned, the expenditure incurred thereon is written off in the year in which the decision is made.
j) Trade and other payables
These amounts represent liabilities for goods and services provided to the consolidated entity prior to the end of the financial year and which are unpaid. Due to their short-term nature they are measured at amortised cost and are not discounted. The amounts are unsecured and are usually paid within 30 days of recognition.
- Material accounting policy (continued)
k) Issued capital
Ordinary shares are classified as equity.
Incremental costs directly attributable to the issue of new shares or options are shown in equity as a deduction, net of tax, from the proceeds.
l) Cash and cash equivalents
Cash and cash equivalents include cash on hand, deposits held at call with banks, other short-term highly liquid investments with short periods to maturity and bank overdrafts. Bank overdrafts are shown within short-term borrowings in current liabilities on the statement of financial position.
m) Other income
Interest
Interest revenue is recognised as interest accrues using the effective interest method. This is a method of calculating the amortised cost of a financial asset and allocating the interest income over the relevant period using the effective interest rate, which is the rate that exactly discounts estimated future cash receipts through the expected life of the financial interest to the net carrying amount of the financial asset.
Other revenue
Other revenue is recognised when it is received or when the right to receive payment is established.
n) Borrowing costs
Borrowing costs are capitalised, net of interest received on cash drawn down yet to be expended when they are directly attributable to the acquisition, contribution or production of an asset that necessarily takes a substantial period of time to get ready for its intended use or sale.
o) Employee benefits
Equity-settled compensation
The consolidated entity operates equity-settled share based payment employee share and option schemes. The fair value of the equity to which employees become entitled is measured at grant date and recognised as an expense over the vesting period, with a corresponding increase to an equity account.
Share based payments to non-employees are measured at the fair value of goods or services received or the fair value of the equity instruments issued, if it is determined the fair value of the good or services cannot be reliably measured, and are recorded at the date the goods or services are received. The corresponding amount is shown in the option reserve.
The fair value of shares is ascertained as the market bid price. The fair value of options is ascertained using an appropriate valuation model which incorporates all market vesting conditions. The number of shares and options expected to vest is reviewed and adjusted at the end of each reporting period such that the amount recognised for services received as consideration for the equity instruments granted shall be based on the number of equity instruments that eventually vest.
p) Goods and services tax (“GST”)
Revenues, expenses and assets are recognised net of the amount of GST, except where the amount of GST incurred is not recoverable from the Australian Tax Office. In these circumstances the GST is recognised as part of the cost of acquisition of the asset or as part of an item of the expense. Receivables and payables in the statement of financial position are shown inclusive of GST.
Cash flows are presented in the statement of cash flows on a gross basis, except for the GST component of investing and financing activities, which are disclosed as operating cash flows.
- Material accounting policy (continued)
q) Earnings/ loss per share
- Basic earnings/ loss per share
Basic earnings/loss per share is determined by dividing net profit after income tax attributable to members of the company, excluding any costs of servicing equity other than ordinary shares, by the weighted average number of ordinary shares outstanding during the financial year, adjusted for bonus elements in ordinary shares issued during the year.
- Diluted earnings/ loss per share
Diluted earnings/loss per share adjusts the figures used in the determination of basic earnings/loss per share to take into account the after income tax effect of interest and other financing costs associated with dilutive potential ordinary shares and the weighted average number of shares assumed to have been issued for no consideration in relation to dilutive potential ordinary shares.
r) Foreign currency translation
The financial statements are presented in Australian dollars, which is Celsius Resources Limited’s functional and presentation currency.
Foreign currency transactions
Foreign currency transactions are translated into Australian dollars using the exchange rates prevailing at the dates of the transactions. Foreign exchange gains and losses resulting from the settlement of such transactions and from the transaction at the financial year-end exchange rates of monetary assets and liabilities denominated in foreign currencies are recognised in profit or loss.
Foreign operations
The assets and liabilities of foreign operations are translated into Australian dollars using the exchange rates at the reporting date. The revenues and expenses of foreign operations are translated into Australian dollars using the average exchange rates, which approximate the rates of the transactions, for the period. All resulting foreign exchange differences are recognised in other comprehensive income through the foreign currency reserve in equity.
The foreign currency reserve is recognised in profit or loss when the foreign operation or net investment is disposed of.
s) Provisions
Provisions are recognised when the consolidated entity has a present (legal or constructive) obligation as a result of a past event, it is probable the consolidated entity will be required to settle the obligation, and a reliable estimate can be made of the amount of the obligation. The amount recognised as a provision is the best estimate of the consideration required to settle the present obligation at the reporting date, taking into account the risks and uncertainties surrounding the obligation. If the time value of money is material, provisions are discounted using a current pre-tax rate specific to the liability.
t) Segment reporting
Operating segments are reported in a manner consistent with the internal reporting provided to the chief operating decision maker. The chief operating decision maker is responsible for allocating resources and assessing the performance of the operating segments.
Operating segments are identified based on the internal reports that are regularly reviewed by the chief operating decision maker in order to allocate resources to the segment and assess its performance.
u) Discontinued operations
A discontinued operation is a component of the consolidated entity that has been disposed of or is classified as held for sale and that represents a separate major line of business or geographical area of operations, is part of a single co-ordinated plan to dispose of such a line of business or area of operations, or is a subsidiary acquired exclusively with a view to resale. The results of discontinued operations are presented separately on the face of the statement of profit or loss and other comprehensive income.
- Material accounting policy (continued)
v) Financial instruments
Financial assets and financial liabilities are recognised in the Group’s statement of financial position when the Group becomes a party to the contractual provisions of the instrument.
Financial assets and financial liabilities are initially measured at fair value. Transaction costs that are directly attributable to the acquisition or issue of financial assets and financial liabilities (other than financial assets and financial liabilities at fair value through profit or loss) are added to or deducted from the fair value of the financial assets or financial liabilities, as appropriate, on initial recognition. Transaction costs directly attributable to the acquisition of financial assets or financial liabilities at fair value through profit or loss are recognised immediately in profit or loss.
At each reporting date, the financial assets are assessed for impairment.
w) Non-current assets or disposal groups classified as held for sale
Non-current assets and assets of disposal groups are classified as held for sale if their carrying amount will be recovered principally through a sale transaction rather than through continued use. They are measured at the lower of their carrying amount and fair value less costs of disposal. For non-current assets or assets of disposal groups to be classified as held for sale, they must be available for immediate sale in their present condition and their sale must be highly probable.
An impairment loss is recognised for any initial or subsequent write down of the non-current assets and assets of disposal groups to fair value less costs of disposal. A gain is recognised for any subsequent increases in fair value less costs of disposal of non-current assets and assets of disposal groups, but not in excess of any cumulative impairment loss previously recognised.
Non-current assets classified as held for sale and the assets of disposal groups classified as held for sale are presented separately on the face of the statement of financial position, in current assets. The liabilities of disposal groups classified as held for sale are presented separately on the face of the statement of financial position, in current liabilities.
x) Borrowings
Loans and borrowings are initially recognised at the fair value of the consideration received, net of transaction costs. They are subsequently measured at amortised cost using the effective interest method.
y) Critical accounting judgments, estimates and assumptions
The preparation of the financial statements requires management to make judgements, estimates and assumptions that affect the reported amounts in the financial statements. Management continually evaluates its judgements and estimates in relation to assets, liabilities, contingent liabilities, revenue and expenses. Management bases its judgements, estimates and assumptions on historical experience and on other various factors, including expectations of future events, management believes to be reasonable under the circumstances. The resulting accounting judgements and estimates will seldom equal the related actual results. The judgements, estimates and assumptions that have a significant risk of causing a material adjustment to the carrying amounts of assets and liabilities (refer to the respective notes) within the next financial year are discussed below.
Following is a summary of the key judgements that have not been disclosed elsewhere in these financial statements.
Consolidation
Up until 20 April 2026, MMCI had been consolidated into CLA. The determination of CLA as the parent of MMCI was based on the following factors:
1. CLA’s exclusive funding of MMCI until April 2026;
2. CLA’s exposure to economic risk and influence over financial direction;
3. The Board of MMCI comprised nominees of CLA and no Sodor representatives were appointed until April 2026.
On 20 April 2026, Sodor requisitioned a MMCI shareholder’s meeting at which all five MMCI board seats were declared vacant and Sodor appointed its own representatives to the MMCI Board and terminated key executives. CLA has been unable to exercise any form of management / control of MMCI since that time. CLA considers that for financial reporting purposes, it ceased to be the parent of MMCI on 20 April 2026 and therefore MMCI should be deconsolidated as at that date.
- Material accounting policy (continued)
Critical accounting judgments, estimates and assumptions (continued)
Following is a summary of the key assumptions concerning the future and other key sources of estimation at reporting date that have not been disclosed elsewhere in these financial statements.
Exploration and evaluation assets
Exploration and evaluation costs have been capitalised on the basis that activities in the area have not yet reached a stage that permits reasonable assessment of the existence of economically recoverable reserves. Key judgements are applied in considering costs to be capitalised which includes determining expenditures directly related to these activities and allocating overheads between those that are expensed and capitalised. In addition, costs are only capitalised that are expected to be recovered either through successful development or sale of the relevant mining interest. Factors that could impact the future
commercial production at the mine include the level of reserves and resources, future technology changes, which could impact the cost of mining, future legal changes and changes in commodity prices. To the extent that capitalised costs are determined not to be recoverable in the future, they will be written off in the period in which this determination is made.
Share based payment transactions
The consolidated entity measures the cost of equity-settled transactions with employees by reference to the fair value of the equity instruments at the date at which they are granted. The fair value is determined by using either the Binomial or Black-Scholes model taking into account the terms and conditions upon which the instruments were granted. The accounting estimates and assumptions relating to equity-settled share-based payments would have no impact on the carrying amounts of assets and liabilities within the next annual reporting period but may impact profit or loss and equity.
z) New or amended Accounting Standards and Interpretations adopted
The consolidated entity has adopted all of the new or amended Accounting Standards and Interpretations issued by the Australian Accounting Standards Board ('AASB') that are mandatory for the current reporting period.
Any new or amended Accounting Standards or Interpretations that are not yet mandatory have not been early adopted.
aa) New Accounting Standards and Interpretations not yet mandatory or early adopted
Australian Accounting Standards and Interpretations that have recently been issued or amended but are not yet mandatory have not been early adopted by the consolidated entity for the annual reporting period ended 30 June 2026. The consolidated entity has not yet assessed the impact of these new or amended Australian Accounting Standards Board (AASB) Standards and Interpretations.
AASB 18 Presentation and Disclosure in Financial Statements
This standard is applicable to annual reporting periods beginning on or after 1 January 2027 and early adoption is permitted. The standard replaces IAS 1 'Presentation of Financial Statements', with many of the original disclosure requirements retained and there will be no impact on the recognition and measurement of items in the financial statements. But the standard will affect presentation and disclosure in the financial statements, including introducing five categories in the statement of profit or loss and other comprehensive income: operating, investing, financing, income taxes and discontinued operations. The standard introduces two mandatory sub-totals in the statement: 'Operating profit' and 'Profit before financing and income taxes'. There are also new disclosure requirements for 'management-defined performance measures', such as earnings before interest, taxes, depreciation and amortisation ('EBITDA') or 'adjusted profit'. The standard provides enhanced guidance on grouping of information (aggregation and disaggregation), including whether to present this information in the primary financial statements or in the notes. The consolidated entity will adopt this standard from 1 July 2027 and it is expected that there will be a significant change to the layout of the statement of profit or loss and other comprehensive income.
- Segment information
The consolidated entity operates within three geographical segments within mineral exploration and extraction being Australia, Namibia and Philippines. The segment information provided to the chief operating decision maker is as follows:
|
2026 |
AUSTRALIA |
NAMIBIA |
PHILIPPINES |
Consolidated |
|
|
$ |
$ |
$ |
$ |
|
Revenue |
|
|
|
|
|
Segment other income |
80,147 |
- |
- |
80,147 |
|
Total other income |
|
|
|
80,147 |
|
|
|
|
|
|
|
Total segment expenditure |
(21,441,715) |
(42,457) |
(1,975,302) |
(23,459,474) |
|
Loss before income tax expense |
|
|
|
(23,379,327) |
|
|
|
|
|
|
|
Segment assets |
7,358,022 |
3,020,744 |
2,223,842 |
12,602,608 |
|
Total assets |
|
|
|
12,602,608 |
|
|
|
|
|
|
|
Segment liabilities |
(622,423) |
(38,205) |
(12,306) |
(672,934) |
|
Total liabilities |
|
|
|
(672,934) |
|
2025 |
AUSTRALIA |
NAMIBIA |
PHILIPPINES |
Consolidated |
|
|
|
$ |
$ |
$ |
$ |
|
|
Revenue |
|
|
|
|
|
|
Segment other income |
- |
- |
795 |
795 |
|
|
Total other income |
|
|
|
795 |
|
|
|
|
|
|
|
|
|
Total segment expenditure |
(1,627,245) |
(4,546,699) |
(1,398,504) |
(7,572,448) |
|
|
Loss before income tax expense |
|
|
|
(7,571,653) |
|
|
|
|
|
|
|
|
|
Segment assets |
1,463,237 |
3,048,971 |
27,587,395 |
32,099,603 |
|
|
Total assets |
|
|
|
32,099,603 |
|
|
|
|
|
|
|
|
|
Segment liabilities |
(169,483) |
(49,680) |
(5,428,535) |
(5,647,698) |
|
|
Total liabilities |
|
|
|
(5,647,698) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Other income |
80,147 |
795 |
|
|
80,147 |
795 |
- Other expenses
|
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Expenses, excluding finance costs, included in the statement of profit or loss and other comprehensive income |
|
|
|
Consulting fees |
108,429 |
561,930 |
|
Regulatory costs |
210,974 |
195,103 |
|
Shareholder meeting costs |
13,341 |
19,629 |
|
Marketing costs |
107,133 |
49,179 |
|
Insurance costs |
63,505 |
30,002 |
|
AIM Listing costs |
180,761 |
28,397 |
|
Sundry expenses |
267,084 |
237,616 |
|
|
951,227 |
1,121,856 |
- Income tax expense
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Loss before income tax expense |
(23,379,327) |
(7,571,653) |
|
Tax at the Australian tax rate of 30% (2025: 30%) |
(7,013,798) |
(2,271,497) |
|
|
|
|
|
Tax effect amounts which are not deductible in calculating taxable income |
1,806,623 |
4,698 |
|
Deferred tax assets not brought to account |
5,284,799 |
982,742 |
|
Movement in temporary differences |
(77,624) |
1,284,057 |
|
Income tax expense |
- |
- |
|
|
|
|
|
|
|
|
|
Tax benefit not recognised – opening balance |
35,887,499 |
33,620,700 |
|
Tax benefit not recognised – current year |
5,207,175 |
2,266,799 |
|
Tax benefit at 30% not recognised (2025: 30%) |
41,094,674 |
35,887,499 |
The deferred tax asset attributable to carried forward income tax losses and temporary differences has not been recognised as an asset as the company has not commenced trading and the availability of future profits to recoup these losses is not considered probable at the date of this report.
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Cash at bank and on hand |
7,204,425 |
4,368,851 |
|
|
7,204,425 |
4,368,851 |
|
|
|
|||
|
|
2026 |
2025 |
|||
|
|
$ |
$ |
|||
|
Other debtors |
11,693 |
38,826 |
|||
|
|
11,693 |
38,826 |
|||
|
In the reporting period ended 30 June 2024, the Group discontinued operations for the entire Opuwo Group segment. The Directors undertook a sale process following a strategic decision to place greater focus on the Group’s key assets in the Philippines.
The discontinued operations have continued for the reporting period ended 30 June 2026, when the contract of sale of the segment was finalised. Although intra-group transactions have been fully eliminated in the consolidated financial results, the directors have elected to attribute the elimination of transactions between the continuing operations and the discontinued operation before the disposal in a way that reflects the continuance of these transactions subsequent to the disposal, because the directors believe this is useful to the user of the financial statements.
To achieve this presentation, the Directors have eliminated from the results of the discontinued operations the inter-segment transactions made before any disposal occurs. Because expenditure from the discontinued operation will continue after the disposal, inter-segment purchases made by the continuing operations before the disposal are retained in continuing operations.
Financial performance information
|
- To the extent that capitalised exploration and evaluation expenditure is determined not to be recoverable in the future, profits/(losses) and net assets will be varied in the period in which this determination is made.
Cash flow information
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Net cash used in operating activities |
(166,578) |
(64,182) |
|
Net cash used in investing activities |
- |
(118,682) |
|
Net cash from financing activities |
167,612 |
191,394 |
|
|
1,034 |
8,530 |
- Fixed assets classified as held for sale
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Plant and equipment |
3,230 |
3,159 |
|
|
3,230 |
3,159 |
In the prior reporting period, the Company reclassified assets in the Opuwo Cobalt Group to Assets Held for Sale and the carrying value for all property, plant & equipment associated with the Opuwo Cobalt Group was reclassified at 30 June 2024. The Company continues to classify the assets in the Opuwo Cobalt Group as held for sale at 30 June 2026.
- Assets of disposal groups classified as held for sale
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Other current assets |
831 |
20,171 |
|
Exploration and evaluation |
3,016,025 |
3,016,025 |
|
Prepayments |
3,888 |
5,810 |
|
|
3,020,744 |
3,042,006 |
In the prior reporting period, the Company reclassified assets in the Opuwo Cobalt Group, View Nickel Pty Ltd and Cullarin Metals Pty to Assets Held for Sale. All current assets associated with the Opuwo Cobalt Group, View Nickel Pty Ltd and Cullarin Metals Pty Ltd were reclassified at 30 June 2024.
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Expenditure brought forward |
23,635,393 |
19,577,942 |
|
Expenditure incurred during the year |
9,799,922 |
4,201,800 |
|
Foreign exchange movements |
(2,440,959) |
(144,349) |
|
Deconsolidation of MMCI |
(28,770,513) |
- |
|
Expenditure carried forward |
2,223,843 |
23,635,393 |
- In accordance with AASB 6 Exploration for and Evaluation of Mineral Resources an indication of impairment may exist if the right to explore in the specific area has expired during the year and is not expected to be renewed. No impairments were recorded for the period ending 30 June 2026 (2025: Nil).
- Financial asset
|
|
2026 |
2025 |
|
|
$ |
$ |
|
MMCI receivable on deconsolidation |
14,969,510 |
- |
|
Less provision for impairment |
(14,969,510) |
- |
|
|
- |
- |
|
|
|
2026 |
|
|
|
$ |
|
Opening balance |
|
- |
|
Recognise MMCI receivable on deconsolidation |
|
14,969,510 |
|
Less provision for impairment recognised |
|
(14,969,510) |
|
Closing balance |
|
- |
The interest free loan from Celsius to Makilala Mining Company Inc (now an associate of the Celsius group) was recognised upon the deconsolidation of Makilala Mining Company Inc on 20 April 2026. The loan is unsecured and bears no interest. No interest income was recognised in relation to the loan during the year. The transaction was entered into on terms that are not equivalent to those that would be expected to apply in an arm’s length transaction.
Notwithstanding that MMCI has confirmed the balance of the loan as at 30 June 2026, the carrying value of the loan has been impaired to a nil value having regard to the developments outlined in notes 14 and 25.
- Investment in associate
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Investment in associate |
15,711,379 |
- |
|
Less provision for impairment |
(15,711,379) |
- |
|
|
- |
- |
Given the loss of control of Makilala Mining Company Inc (“MMCI”) described in note 25 and the Group’s 40% interest, MMCI is recognised as an associate.
The Group is in a dispute with Equinaire Holdings Limited (“Equinaire”), a wholly-owned subsidiary of Indian-based Kiri Industries Limited (“Kiri”), with respect to the Omnibus Loan and Security Agreement (“OLSA”), which relates to a financing facility provided by Maharlika Investment Corporation (“MIC”) to MMCI.
Following the purported sale and assignment of the OLSA by MIC to Equinaire, Equinaire issued a series of claimed Events of Default and proceeded with foreclosure of Celsius’ 40% interest in MMCI and a public auction of this interest on 8 September 2026.
Equinaire submitted a credit bid of US$5,010,000. As there were no other registered bidders in attendance and no other bids received, Equinaire was declared the winning bidder.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI. It believes that Equinaire’s claimed Events of Default should be referred to arbitration in accordance with the dispute resolution clauses within the OLSA.
Celsius intends to protect its interests through a combination of appeals to higher Philippine courts and by progressing arbitration to seek an injunction around the transfer of MMCI shares, to dispute the occurrence and continuance of any claimed Events of Default and to pursue damages against Equinaire.
Given the ongoing dispute with Equinaire, the carrying value of the Group’s investment in MMCI has been impaired. Information relating to MMCI and its impairment is set out below:
|
|
|
|
Ownership interest |
|||||
|
|
|
Principal place of business |
|
|
2026 |
|
2025 |
|
|
Name |
|
|
|
|
% |
|
% |
|
|
Makilala Mining Company Inc |
|
Philippines |
|
|
40 |
|
100 |
|
|
|
|
|
|
|
|
|
|
|
Carrying amount of the investment
|
|
|
2026 |
|
|
|
$ |
|
Opening balance |
|
- |
|
Recognition of investment in MMCI at fair value (upon deconsolidation) |
|
16,408,178 |
|
Share of loss (40%) |
|
(696,799) |
|
Less provision for impairment |
|
(15,711,379) |
|
Closing balance |
|
- |
Celsius’ share of MMCI’s loss is recognised from 20 April 2026, being the date on which Celsius is deemed to have obtained significant influence.
At 30 June 2026, the carrying amount of the investment was nil.
- Trade and other payables
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Trade creditors and other payables |
416,670 |
693,645 |
|
|
416,670 |
693,645 |
- Other current liabilities
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Accrued expenses |
218,059 |
1,699,220 |
|
|
218,059 |
1,699,220 |
- Liabilities directly associated with assets classified as held for sale
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Trade payables |
12,852 |
15,981 |
|
Accrued expenses |
25,353 |
33,699 |
|
|
38,205 |
49,680 |
- Loans and borrowings
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Secured loans |
- |
3,073,552 |
|
|
- |
3,073,552 |
In February 2025 the Company’s Philippine affiliated company (former subsidiary), Makilala Mining Company, Inc. (“MMCI”) entered into a bridge loan facility (“Facility”) to fully finance the updating of the Company’s Feasibility Study and Front-End Engineering Design (“FEED”), and to partially finance the development and operations of the Maalinao-Caigutan-Biyog Copper-Gold Project (“MCB”) Project; and to maintain regulatory compliance of the MCB Project.
The Facility is covered by two Omnibus Loan and Security Agreements (respectively, “First OLSA” and the “Second OLSA”; collectively, the “OLSAs”). The total available amount under the Facility is USD 76.4 million of which USD 2 million was drawn down as at 30 June 2025. The amounts drawn down are repayable on maturity date which is 3 years after the first drawdown under the Second OLSA, or within 1 year of the first drawdown under the First OLSA if the FEED and the Feasibility Study is unsatisfactory.
Interest is compounded quarterly and added to the principal amount, payable on maturity date at a fixed interest rate of 12.5%, compounded quarterly. The loan is a United States dollar denominated loan which is carried at amortised cost.
The Facility is secured by a Real Estate Mortgage on MMCI’s mining rights and Project-related property; a security interest in collateral, moveable assets and project documents; Share Collateral on shares of the Company’s wholly-owned Philippine subsidiary Makilala Holding Limited and Sodor, Inc. in MMCI; Control over the Project’s financial accounts; and Corporate Suretyship from Celsius Resources Limited for 40% of the Facility Amount.
- Issued capital
|
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Ordinary shares – fully paid |
103,303,313 |
92,787,841 |
|
Capital raising costs |
(7,642,457) |
(6,935,766) |
|
|
95,660,856 |
85,852,075 |
|
a) Ordinary shares |
|
|
||||||||
|
|
2026 |
2025 |
|
2026 |
2025 |
|||||
|
Date |
No. of shares |
No. of shares |
Issue price $ |
$ |
$ |
|||||
|
At the beginning of the year: |
3,135,488,452 |
2,427,912,743 |
|
85,852,075 |
81,188,958 |
|||||
|
Shares issued during the year |
|
|
|
|
|
|||||
|
19 November 2025 |
106,000,000 |
- |
0.01 |
1,069,453 |
- |
|||||
|
12 February 2026 |
7,500,000 |
- |
0.009 |
74,174 |
- |
|||||
|
27 February 2026 |
463,250,000 |
- |
0.02 |
9,265,000 |
- |
|||||
|
27 February 2026 |
7,372,157 |
- |
0.009 |
71,845 |
- |
|||||
|
1 May 2026 |
846,111 |
- |
0.009 |
- |
- |
|||||
|
1 May 2026 |
1,750,000 |
- |
0.02 |
35,000 |
|
|||||
|
30 September 2024 |
- |
143,111,758 |
0.013 |
- |
1,217,850 |
|||||
|
16 December 2024 |
- |
87,500,000 |
0.008 |
- |
703,255 |
|||||
|
20 December 2024 |
- |
10,713,951 |
0.008 |
- |
86,190 |
|||||
|
19 March 2025 |
- |
212,333,535 |
0.008 |
- |
1,698,668 |
|||||
|
26 March 2025 |
- |
25,999,213 |
0.008 |
- |
207,994 |
|||||
|
16 May 2025 |
- |
227,917,252 |
0.008 |
- |
1,823,338 |
|||||
|
Capital raising costs |
- |
- |
- |
(706,691) |
(1,074,178) |
|||||
|
At the end of the year |
3,722,206,720 |
3,135,488,452 |
|
95,660,856 |
85,852,075 |
|||||
|
|
|
|
|
|
|
|||||
|
Ordinary shares entitle the holder to participate in dividends and the proceeds on winding up of the Company in proportion to the number of and amounts paid on the shares held.
|
||||||||||
|
On a show of hands every holder of ordinary shares present at a meeting in person or by proxy is entitled to one vote, and upon a poll, each share is entitled to one vote.
|
||||||||||
|
b) Capital management
|
|
|
||||||||
|
The objectives of management when managing capital are to safeguard the consolidated entity’s ability to continue as a going concern, so that the consolidated entity may continue to provide returns for shareholders and benefits for other stakeholders. |
||||||||||
|
The consolidated entity’s strategy is to ensure appropriate liquidity is maintained to meet anticipated operating requirements, with a view to initiating appropriate capital raisings as required. The working capital position of the consolidated entity at 30 June 2026 and 2025 is as follows: |
||||||||||
|
|
|
|||||||||
|
|
2026 |
2025 |
||||||||
|
|
$ |
$ |
||||||||
|
|
|
|
||||||||
|
Cash and cash equivalents |
7,204,425 |
4,368,851 |
||||||||
|
Trade and other receivables |
11,693 |
6,380 |
||||||||
|
Other current assets |
135,650 |
158,645 |
||||||||
|
Trade and other payables |
(634,729) |
(2,422,751) |
||||||||
|
Working capital positions |
6,717,039 |
2,111,125 |
||||||||
|
|
|
|
||||||||
- Reserves
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Share based payment reserve |
1,111,649 |
1,038,450 |
|
Foreign currency translation |
(3,346,854) |
(2,322,038) |
|
|
(2,235,205) |
(1,283,588) |
|
Share based payment reserve |
|
|
|
Balance 1 July |
1,038,450 |
502,759 |
|
Issue of options - Capital raising costs |
- |
535,691 |
|
Issue of warrants |
33,605 |
- |
|
Performance rights recognised |
39,594 |
- |
|
Balance 30 June |
1,111,649 |
1,038,450 |
2,372,157 options were exercised during the period (2025: Nil).
Set out below is a summary of the movements in options on issue during the year:
|
Grant date |
Expiry date |
Exercise price $ |
Balance at the start of the year |
Granted |
Exercised |
Expired/ forfeited |
Balance at the end of the year |
|
|
30/09/2024 |
30/09/2027 |
0.025 |
33,673,355 |
- |
- |
- |
33,673,355 |
|
|
20/05/2025 |
20/05/2028 |
0.01 |
301,875,000 |
- |
(2,372,157) |
- |
299,502,843 |
|
|
14/08/2025 |
20/05/2028 |
0.01 |
- |
122,075,070 |
|
|
122,075,070 |
|
|
|
|
|
335,548,355 |
122,075,070 |
(2,372,157) |
- |
455,251,268 |
|
|
Weighted average exercise price |
0.011 |
- |
- |
- |
0.011 |
|||
The options issued during the period were issued as free attaching and subsequently, not valued.
The weighted average remaining contractual life of options outstanding at the end of the financial year was 1.68 years. (2025: 2.83 years).
Warrants
Set out below is a summary of the movements in warrants on issue during the year:
|
Grant date |
Expiry date |
Exercise price GBP |
Balance at the start of the year |
Granted |
Exercised |
Expired/ forfeited |
Balance at the end of the year |
||
|
31/01/2023 |
28/04/2028 |
0.008 |
12,500,000 |
- |
- |
- |
12,500,000 |
||
|
31/01/2023 |
28/04/2026 |
0.008 |
13,500,000 |
- |
- |
(13,500,000) |
- |
||
|
05/04/2023 |
28/04/2026 |
0.008 |
10,000,000 |
- |
- |
(10,000,000) |
- |
||
|
15/04/2024 |
26/12/2026 |
0.009 |
153,666,663 |
- |
- |
- |
153,666,663 |
||
|
15/04/2024 |
26/12/2026 |
0.009 |
8,474,999 |
- |
- |
- |
8,474,999 |
||
|
26/06/2024 |
26/12/2026 |
0.009 |
19,552,752 |
- |
- |
- |
19,552,752 |
||
|
16/12/2024 |
31/12/2026 |
0.005 |
43,750,000 |
- |
(12,500,000) |
- |
31,250,000 |
||
|
20/12/2024 |
31/12/2026 |
0.005 |
5,356,976 |
- |
- |
- |
5,356,976 |
||
|
19/11/2025 |
19/11/2028 |
0.007 |
- |
5,300,000 |
- |
- |
5,300,000 |
||
|
|
|
|
266,801,390 |
5,300,000 |
(12,500,000) |
(23,500,000) |
236,101,390 |
||
|
|
|
|
|
|
|
||||
Set out below are the warrants on issue at the end of the financial year:
|
Grant date |
Expiry date |
2026 Number |
2025 Number |
|
31/01/2023 |
28/04/2028 |
12,500,000 |
12,500,000 |
|
31/01/2023 |
28/04/2026 |
- |
13,500,000 |
|
05/04/2023 |
28/04/2026 |
- |
10,000,000 |
|
15/04/2024 |
26/12/2026 |
153,666,663 |
153,666,663 |
|
15/04/2024 |
26/12/2026 |
8,474,999 |
8,474,999 |
|
26/06/2024 |
26/12/2026 |
19,552,752 |
19,552,752 |
|
16/12/2024 |
31/12/2026 |
31,250,000 |
43,750,000 |
|
20/12/2024 |
31/12/2026 |
5,356,976 |
5,356,976 |
|
19/11/2025 |
19/11/2028 |
5,300,000 |
- |
|
|
|
236,101,390 |
266,801,390 |
|
Foreign currency translation reserve |
|
|
|
|
2026 |
2025 |
|
Balance 1 July |
(2,322,038) |
(2,722,158) |
|
Foreign currency translation movement |
(2,049,540) |
400,120 |
|
Reclassified to profit or loss on loss of control of subsidiary |
1,024,724 |
- |
|
Balance 30 June |
(3,346,854) |
(2,322,038) |
The reserve is used to recognise exchange differences arising from the translation of financial statements of foreign operations to Australian dollars.
- Interests of Key Management Personnel (“KMP”)
Refer to the remuneration report contained in the Directors’ report for details of the remuneration paid or payable to each member of the consolidated entity’s key management personnel for the year ended 30 June 2026.
The total remuneration paid to KMP of the Company and the group are as follows:
|
|
2026 |
2025 |
|
Short-term employee benefits |
548,955 |
1,876,350 |
|
Post-employment benefits |
13,942 |
11,040 |
|
Other: Consultancy |
924,214 |
- |
|
Share based payments |
39,594 |
- |
|
|
1,526,705 |
1,887,390 |
- Related parties
- Parent entity
The parent entity is Celsius Resources Limited.
- Controlled entities
Interests in controlled entities are set out in Note 26.
- Key management personnel
Disclosures relating to key management personnel are set out in Note 21 and the remuneration report included in the Directors’ report.
- Transactions and balances with related parties
During the year, Bardin Davis was paid managing director fees of $100,000 plus superannuation of $7,500. A further $25,000 accrued for consideration shares and taxation obligations (approved at the EGM on 9 September 2026) plus $39,594 recognised as the expense of performance rights approved by shareholders on 9 September 2026.
During the year, Julito Sarmiento was paid director and consultancy fees. The group paid Mr Julito Sarmiento $41,665 for director fees and $304,211 for consultancy services.
During the year, payments were made to Mannerim Capital Pty Ltd, a company in which Mr Grimes is a shareholder and Director. Payments were made to the company for director fees to the value of $185,920.
During the year, payments were made to Peter Hume for director fees and consultancy services. Payments were for the value of $471,346.
During the year, payments were made to Skyhill Partners Ltd, a company in which Mr Dudley is a shareholder and Director. Payments were made to this company for consultancy services to the value of $60,000.
During the year, payments were made to Attilenore P. Manero for director fees and consultancy services. Payments were for the value of $228,117.
During the year, payments were made to Hybrid FS Pty Ltd, a company in which Mr Mark van Kerkwijk is a shareholder and Director. Payments were made to this company for director fees to the value of $63,352.
There were no other transactions with related parties.
- Payables owing to related parties
|
|
2026 $ |
2025 $ |
|
Bardin Davis |
437 |
- |
|
Julito Sarmiento |
- |
634,287 |
|
Mannerim Capital Pty Ltd |
- |
11,671 |
|
Peter Hume |
- |
565,069 |
|
Skyhill Partners Ltd |
15,000 |
25,000 |
|
Attilenore P. Manero |
- |
4,000 |
|
Hybrid FS Pty Ltd |
5,980 |
8,363 |
|
|
21,417 |
1,248,390 |
- Remuneration of auditors
|
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
- Tenement expenditure commitments:
The consolidated entity is required to maintain current rights of tenure to tenements, which require outlays of expenditure in future financial periods. Under certain circumstances these commitments are subject to the possibility of adjustment to the amount and/or timing of such obligations, however, they are expected to be fulfilled in the normal course of operations.
|
|
2026 |
2025 |
|
|
$ |
$ |
|
The consolidated entity has tenement rental and expenditure commitments payable of: |
||
|
– not later than 12 months |
439,197 |
4,849,502 |
|
– between 12 months and 5 years |
213,674 |
38,796,440 |
|
– more than 5 years |
6,223 |
9,933,959 |
|
|
659,094 |
53,579,901 |
- Capital commitments
There are no capital commitments contracted for at balance date (2025: Nil).
- Deconsolidation of subsidiary
On 20 April 2026, the Group ceased to control Makilala Mining Company Inc (“MMCI”).
MMCI has been consolidated to 20 April 2026 and deconsolidated from that date. The retained 40% interest has been recognised at fair value and is accounted for as an investment in an associate under the equity method (note 14).
|
|
2026 |
|
|
$ |
|
Fair value of consideration received |
- |
|
Fair value of the 40% interest retained |
16,408,178 |
|
Foreign currency translation reserve reclassified to profit or loss |
(1,024,724) |
|
Assets derecognised |
(29,284,419) |
|
Liabilities derecognised |
27,171,331 |
|
Gain on deconsolidation of subsidiary |
13,270,366 |
Assets and liabilities derecognised
The carrying amounts of the assets and liabilities of MMCI derecognised at 20 April 2026 were:
|
|
|
|
|
2026 |
|
|
|
|
|
$ |
|
Cash |
|
|
|
635,374 |
|
Debtors |
|
|
|
266,618 |
|
Prepayments |
|
|
|
16,627 |
|
Mine development |
|
|
|
27,959,416 |
|
Right of use asset |
|
|
|
81,854 |
|
Fixed assets |
|
|
|
324,530 |
|
Total assets |
|
|
|
29,284,419 |
|
|
|
|
|
|
|
Trade creditors |
|
|
|
(345,375) |
|
Accrued creditors |
|
|
|
(1,278,579) |
|
Other payables |
|
|
|
(105,187) |
|
Lease liability |
|
|
|
(86,524) |
|
Intercompany loans |
|
|
|
(25,355,666) |
|
Total liabilities |
|
|
|
(27,171,331) |
|
|
|
|
|
|
|
Net assets derecognised |
|
|
|
2,113,088 |
Cash flow effect
|
|
|
|
|
2026 |
|
|
|
|
|
$ |
|
Cash consideration received |
|
|
|
- |
|
Less: cash and cash equivalents derecognised |
|
|
|
(635,374) |
|
Net cash outflow on loss of control of subsidiary |
|
|
|
(635,374) |
Results of MMCI to the date of loss of control
The consolidated statement of profit or loss and other comprehensive income includes the results of MMCI for the period from 1 July 2025 to 20 April 2026. MMCI has not been presented as a discontinued operation, as the Group retains a 40% interest in it.
Fair value of the retained interest
The interest retained in MMCI has been recognised at fair value measured as at the date of loss of control.
- Controlled entities
|
|
|
|
Percentage Owned (%) |
|
Name of Entity |
Country of Incorporation |
Class of Shares |
2026 |
2025 |
|
Opuwo Cobalt Pty Ltd |
Australia |
Ordinary |
100% |
100% |
|
View Nickel Pty Ltd |
Australia |
Ordinary |
100% |
100% |
|
Opuwo Cobalt Holdings (Pty) Ltd |
Namibia |
Ordinary |
95% |
95% |
|
Opuwo Cobalt Mining (Pty) Ltd |
Namibia |
Ordinary |
95% |
95% |
|
Cullarin Metals Pty Ltd |
Australia |
Ordinary |
100% |
100% |
|
Makilala Holding Ltd |
British Virgin Islands |
Ordinary |
100% |
100% |
|
PDEP Holdings, LLC |
United States |
Ordinary |
100% |
100% |
|
Tambuli, LLC |
United States |
Ordinary |
100% |
100% |
|
PDEP, Inc. |
Philippines |
Ordinary |
100% |
100% |
|
Tambuli Mining Company, Inc. |
Philippines |
Ordinary |
100% |
100% |
On 17 March 2023, agreements were entered into whereby Sodor acquired a 60% legal ownership in MMCI (owner of the MCB Project) for consideration of ~US$5 million. PMR, an affiliate of Sodor, was to subscribe for shares in PDEP Inc. the intended mineral processing company for the MCB Project, for an amount of ~US$38 million. The net effect would leave CLA with 70% economic interest in the MCB project. Payment of the combined consideration of US$43M was not received by the due date (16 February 2026).
Up until 20 April 2026, MMCI had been consolidated into CLA. The determination of CLA as the parent of MMCI was based on the following factors:
1. CLA’s exclusive funding of MMCI until April 2026;
2. CLA’s exposure to economic risk and influence over financial direction;
3. The Board of MMCI comprised nominees of CLA and no Sodor representatives were appointed until April 2026.
On 20 April 2026, Sodor requisitioned a MMCI shareholder’s meeting at which all five MMCI board seats were declared vacant and Sodor appointed its own representatives to the MMCI Board and terminated key executives. CLA has been unable to exercise any form of management / control of MMCI since that time.
CLA considers that for financial reporting purposes, it ceased to be the parent of MMCI on 20 April 2026 and therefore MMCI should be deconsolidated as at that date. CLA has determined its 40% interest in MMCI entitles it to significant influence and this investment will be subsequently measured using equity accounting. The FV of the retained equity interest on 20 April 2026 has been determined to be $16,408,178 (after recording the $14,969,510 loan to MMCI).
Summarised financial information
Summarised financial information of the subsidiary with non-controlling interests that are material to the consolidated entity are set out below:
|
|
|
2026 |
|
2025 |
|
|
|
$ |
|
$ |
|
Summarised statement of financial position |
|
|
|
|
|
Current assets |
|
3,028,814 |
|
3,048,971 |
|
Non-current assets |
|
- |
|
- |
|
Total assets |
|
3,028,814 |
|
3,048,971 |
|
|
|
|
|
|
|
Current liabilities |
|
(16,923) |
|
(49,680) |
|
Non-current liabilities |
|
(11,287,323) |
|
(11,084,276) |
|
Total liabilities |
|
(11,304,246) |
|
(11,133,956) |
|
Net assets |
|
(8,275,432) |
|
(8,084,985) |
|
|
|
|
|
|
|
Summarised statement of profit or loss and other comprehensive income |
|
|
|
|
|
Expenses |
|
(65,803) |
|
(35,716) |
|
Profit/(Loss) before income tax expense |
|
(65,803) |
|
(35,716) |
|
Income tax expense |
|
- |
|
- |
|
|
|
|
|
|
|
Profit/(Loss) after income tax expense |
|
(65,803) |
|
(35,716) |
|
Other comprehensive income |
|
- |
|
- |
|
Total comprehensive profit/(loss) |
|
(65,803) |
|
(35,716) |
|
|
|
|
|
|
|
Statement of cash flows |
|
|
|
|
|
Net cash outflow from operating activities |
|
(65,803) |
|
(35,716) |
|
Net cash inflow from investing activities |
|
- |
|
- |
|
Net cash inflow from financing activities |
|
- |
|
- |
|
Net (decrease) / increase in cash and cash equivalents |
|
(65,803) |
|
(35,716) |
- Events after the reporting period
Appointment of Chair
On 14 July 2026, the Company appointed George Bujtor as Non-Executive Chair of the board of directors.
Equinaire dispute
As highlighted in Note 25 CLA considers that for financial reporting purposes, it ceased to be the parent of MMCI on 20 April 2026 and therefore MMCI should be deconsolidated as at that date. Subsequent to 20 April 2026, the Philippine sovereign wealth fund, Maharlika Investment Corporation (“MIC”) completed the assignment of its rights, title, and interests under the Omnibus Loan and Security Agreement (“OLSA”) with Makilala Mining Company Inc. (“MMCI”) to Equinaire, a wholly-owned subsidiary of Kiri Industries Limited (“Kiri”) of India
Following the purported sale and assignment of the OLSA by MIC to Equinaire, Equinaire issued the following notices in July 2026:
- Notice of Event of Default – claiming that the Notice of Relinquishment issued to Sodor, constituted an Event of Default;
- Notice of Commencement of Foreclosure Proceedings – seeking to initiate a foreclosure process and the enforcement of security with respect to MHL’s 40% interest in MMCI; and
- Notice of Disposition – seeking to initiate a public auction for Celsius’ 40% interest in MMCI.
Equinaire subsequently issued the following additional notices:
- Notice of Event of Default – claiming that certain information-security incidents involving MMCI constituted an Event of Default;
- Notice of Event of Default – claiming that Celsius’ attempt to seek protections from Philippine courts in relation to Equinaire’s attempted foreclosure itself constituted an Event of Default;
- Notice of a Resumption of Foreclosure – seeking to recommence foreclosure and the enforcement of security with respect to Celsius’ 40% interest in MMCI; and
- Notice of Disposition - seeking to proceed with a public auction of Celsius’ 40% interest in MMCI on 8 September 2026.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI.
A Petition for Interim Measures of Protection (“Petition”) was filed with a Philippine court, seeking to injunct any foreclosure of the OLSA or disposition of Celsius’ interest in MMCI until the conclusion of arbitration between the parties.
The court denied the Petition, finding that "irreparable injury” had not been sufficiently established and determining that any potential loss arising from the foreclosure could be addressed through remedies available in arbitration.
However, the court expressly stated that the denial of the Petition is not a determination that an Event of Default occurred or that Equinaire was entitled to foreclose. The Court likewise recognised that these issues remain disputed and should be addressed via arbitration. The court further emphasised that the arbitral tribunal has authority to determine the validity of any foreclosure and, where appropriate, grant interim relief.
On 8 September 2026, Equinaire proceeded to conduct the public auction for the foreclosure of MHL’s shares in MMCI, which were pledged as collateral under the OLSA.
Representatives from MHL were in attendance to put on record that any results of the foreclosure sale remain subject to the final determination of the pending arbitration between MHL and Equinaire.
Equinaire submitted a credit bid of US$5,010,000. As there were no other registered bidders in attendance and no other bids received, Equinaire was declared the winning bidder.
Celsius refutes the occurrence and continuance of an Event of Default under the OLSA and the capacity of Equinaire to initiate a foreclosure process and sell its interest in MMCI. It believes that Equinaire’s claimed Events of Default should be referred to arbitration in accordance with the dispute resolution clauses within the OLSA.
Celsius is seeking to protect its interests through a combination of appeals to higher Philippine courts and by progressing arbitration to seek an injunction around the transfer of MMCI shares, to dispute the occurrence and continuance of any claimed Events of Default and to pursue damages against Equinaire.
Other
On 14 September 2026 the Company issued, following shareholder approval, 100,000,000 performance rights to Mr Bardin Davis.
The Directors are not aware of any other matters or circumstances that have arisen since the end of the financial year which significantly affected or may significantly affect the operations of the consolidated entity the results of those operations, or the state of affairs of the consolidated entity in future financial years.
- Earnings per share
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Earnings per share for loss from continuing operations |
|
|
|
Loss after income tax attributable to the owners of Celsius Resources Limited |
(23,379,327) |
(3,019,529) |
|
|
|
|
|
|
Number |
Number |
|
Weighted average number of ordinary shares used in calculating basic earnings per share |
3,362,105,690 |
2,682,929,559 |
|
Weighted average number of ordinary shares used in calculating diluted earnings per share |
3,362,105,690 |
2,682,929,559 |
|
|
|
|
|
|
Cents |
Cents |
|
Basic earnings per share |
(0.69) |
(0.11) |
|
Diluted earnings per share |
(0.69) |
(0.11) |
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Earnings per share for loss from discontinued operations |
|
|
|
Loss after income tax attributable to the owners of Celsius Resources Limited |
(42,457) |
(4,552,124) |
|
|
|
|
|
|
Cents |
Cents |
|
Basic earnings per share |
(0.00) |
(0.17) |
|
Diluted earnings per share |
(0.00) |
(0.17) |
|
|
|
|
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Earnings per share for loss attributable to the owners of Celsius Resources Limited |
|
|
|
Loss after income tax attributable to the owners of Celsius Resources Limited |
(23,379,327) |
(7,571,653) |
|
|
|
|
|
|
Cents |
Cents |
|
Basic earnings per share |
(0.69) |
(0.28) |
|
Diluted earnings per share |
(0.69) |
(0.28) |
- Cash flow information
|
a) Reconciliation of loss after income tax to net cash outflow from operating activities |
2026 $ |
2025 $ |
|
|
|
|
|
Loss after income tax |
(23,379,327) |
(7,569,181) |
|
Depreciation |
82,013 |
48,736 |
|
Impairment |
30,680,889 |
4,489,955 |
|
Gain on disposal of subsidiary |
(13,270,366) |
- |
|
Share based payments |
39,594 |
- |
|
Share of loss of associate |
696,799 |
- |
|
|
|
|
|
Change in operating assets and liabilities: |
|
|
|
Trade and other receivables |
5,315 |
37,307 |
|
Trade and other payables1 |
(99,421) |
686,557 |
|
Net cash outflow from operating activities |
(5,244,504) |
(2,306,626) |
|
1 – Net of deconsolidation of subsidiary and investing activities. |
|
|
b) Non-cash investing and financing activities
|
|
|
2026 |
|
2025 |
|
|
|
$ |
|
$ |
|
Additions to the right-of-use assets |
|
- |
|
170,798 |
|
Share-based payments |
|
- |
|
535,692 |
|
|
|
- |
|
706,490 |
- Parent entity disclosures
|
|
|
|
|
|||
|
|
|
2026 |
2025 |
|||
|
(a) Financial position |
|
$ |
$ |
|||
|
Assets |
|
|
|
|||
|
Current assets |
|
7,205,746 |
1,380,977 |
|||
|
Non-current assets |
|
6,845,346 |
16,515,043 |
|||
|
Total assets |
|
14,051,092 |
17,896,020 |
|||
|
|
|
|
|
|||
|
Liabilities |
|
|
|
|||
|
Current liabilities |
|
643,705 |
169,483 |
|||
|
Total liabilities |
|
643,705 |
169,483 |
|||
|
|
|
|
|
|||
|
Equity |
|
|
|
|||
|
Issued capital |
|
95,660,856 |
85,852,075 |
|||
|
Reserves |
|
1,111,649 |
1,038,451 |
|||
|
Accumulated losses |
|
(83,365,117) |
(69,163,989) |
|||
|
Total equity |
|
13,407,388 |
17,726,537 |
|||
|
(b) Financial performance |
|
|
|
|
Loss for the year |
|
(14,212,994) |
(1,788,439) |
|
Other comprehensive income |
|
- |
- |
|
Total comprehensive loss |
|
(14,212,994) |
(1,788,439) |
|
(c) Contingent asset and liabilities of the Parent Entity |
|
|
|
|
There are no such contingencies as at 30 June 2026 and 30 June 2025. |
|
|
|
|
|
|
|
|
|
(d) Commitments of the Parent Entity |
|
|
|
|
The parent entity had no capital commitments for property, plant and equipment as at 30 June 2026 and 30 June 2025.
|
|||
|
(e) Guarantees |
|
|
|
|
In the prior year, the parent entity executed a corporate surety agreement in May 2025 to provide a surety to the value of 40% of the amount of the non-current secured loan to its then subsidiary, Makilala Mining Company, Inc. Refer to Note 18 for further details. |
|||
(f) Material accounting policy information
The accounting policies of the parent entity are consistent with those of the consolidated entity, as disclosed in Note 1, except for the following:
- Investments in subsidiaries are accounted for at cost, less any impairment, in the parent entity.
- Investments in joint ventures are accounted for at cost, less any impairment, in the parent entity.
- Financial risk management
The consolidated entity’s principal financial instruments comprise cash and short-term deposits. The consolidated entity has various other financial assets and liabilities such as other receivables and payables, which arise directly from its operations.
The consolidated entity’s activities expose it to a variety of financial risks, including, credit risk, liquidity risk, foreign exchange rate risk and cash flow interest rate risk. The Company is not exposed to price risk.
Risk management is carried out by the Board of Directors, whose members evaluate and agree upon risk management and objectives.
- Market risk
Interest rate risk
The consolidated entity’s exposure to interest rate risk, which is the risk that a financial instrument’s value will fluctuate as a result of changes in market interest rates and the effective weighted average interest rate for each class of financial assets and financial liabilities comprises:
- Financial risk management (continued)
|
2026 |
Floating Interest Rate |
Fixed Interest Rate
|
Non-Interest Bearing |
Total |
Weighted Average Effective Interest Rate |
|
|
1 Year or Less |
1 to 5 Years |
|||||
|
|
2026 |
2026 |
2026 |
2026 |
2026 |
2026 |
|
Financial assets |
|
|
|
|
|
|
|
Cash |
6,942,459 |
- |
- |
261,966 |
7,204,425 |
1.20% |
|
Trade and other receivables |
- |
- |
- |
11,693 |
11,693 |
- |
|
Total financial assets |
6,942,459 |
- |
- |
273,659 |
7,216,118 |
1.20% |
|
Financial liabilities |
|
|
|
|
|
|
|
Trade and other payables |
- |
- |
- |
634,729 |
634,729 |
- |
|
Lease liability |
- |
- |
- |
- |
- |
- |
|
Loans and borrowings |
- |
- |
- |
- |
- |
- |
|
Total financial liabilities |
- |
- |
- |
634,729 |
634,729 |
|
|
2025 |
Floating Interest Rate |
Fixed Interest Rate
|
Non-Interest Bearing |
Total |
Weighted Average Effective Interest Rate |
|
|
1 Year or Less |
1 to 5 Years |
|||||
|
|
2025 |
2025 |
2025 |
2025 |
2025 |
2025 |
|
Financial assets |
|
|
|
|
|
|
|
Cash |
2,944,535 |
- |
- |
1,424,316 |
4,368,851 |
0.02% |
|
Trade and other receivables |
- |
- |
- |
38,826 |
38,826 |
- |
|
Total financial assets |
2,944,535 |
- |
- |
1,463,142 |
4,407,677 |
|
|
Financial liabilities |
|
|
|
|
|
|
|
Trade and other payables |
- |
- |
- |
2,392,865 |
2,392,865 |
- |
|
Lease liability |
- |
33,592 |
98,009 |
- |
131,601 |
6.07% |
|
Loans and borrowings |
- |
- |
3,073,552 |
- |
3,073,552 |
12.5% |
|
Total financial liabilities |
- |
33,592 |
3,171,561 |
2,392,865 |
5,598,018 |
|
The consolidated entity policy is to monitor the interest rate yield curve out to six months to ensure a balance is maintained between the liquidity of cash assets and the interest rate return. Cash at bank and in hand earns interest at floating rates based on daily bank deposit rates. The consolidated entity does not have any receivables or payables that may be affected by interest rate risk.
The interest rate risk to the consolidated entity is not material.
- Credit risk
The consolidated entity does not have any significant concentrations of credit risk. Credit risk is managed by the Board of Directors and arises from cash and cash equivalents as well as credit exposure including outstanding receivables.
All cash balances held in Australia are held at internationally recognised institutions.
The maximum exposure to credit risk at reporting date is the carrying amount of the financial assets disclosed within the financial report. The credit quality of financial assets that are neither past due nor impaired can be assessed by reference to external credit ratings (if available) or to historical information about default rates.
Financial assets that are neither past due and not impaired are as follows:
- Financial risk management (continued)
|
|
2026 |
2025 |
|
|
$ |
$ |
|
Financial assets - counterparties without external credit rating |
|
|
|
Financial assets with no defaults in the past |
11,693 |
38,826 |
|
Cash and cash equivalents |
|
|
|
‘AA’ S&P rating |
7,204,425 |
4,368,851 |
- Liquidity risk
Prudent liquidity risk management implies maintaining sufficient cash balances and access to equity funding. The consolidated entity’s exposure to the risk of changes in market interest rates relate primarily to cash assets. The Directors monitor the cash-burn rate of the consolidated entity on an on-going basis against budget and the maturity profiles of financial assets and liabilities to manage its liquidity risk.
The financial liabilities the consolidated entity had at reporting date were other payables incurred in the normal course of the business. These were non-interest bearing and were due within the normal 30-60 days terms of creditor payments.
Maturity analysis for financial liabilities
Financial liabilities of the consolidated entity comprise trade and other payables. As at 30 June 2026 and 30 June 2025 all financial liabilities are contractually maturing within 60 days.
- Foreign currency risk
The consolidated entity undertakes certain transactions denominated in foreign currency and is exposed to foreign currency risk through foreign exchange rate fluctuations.
Foreign exchange risks arise when future commercial transactions and recognised financial assets and financial liabilities are denominated in a currency that is not the entity’s functional currency. The risk is measured using sensitivity analysis and cash flow forecasting.
The carrying amount of the consolidated entity's foreign currency denominated financial assets and financial liabilities at the reporting date were as follows:
|
|
|
Assets |
Liabilities |
|||||
|
|
|
2026 |
2025 |
|
2026 |
|
2025 |
|
|
Consolidated |
|
$ |
$ |
|
$ |
|
$ |
|
|
|
|
|
|
|
|
|
|
|
|
British Pound |
|
- |
- |
|
- |
|
- |
|
|
Philippine Peso |
|
123,815 |
3,099,278 |
|
12,306 |
|
2,223,382 |
|
|
US Dollar |
|
- |
- |
|
- |
|
3,073,552 |
|
The consolidated entity has considered the sensitivity relating to its exposure to foreign currency risk at reporting date. A 10% strengthening of the AUD against the following currencies at the end of the reporting date would have increased post-tax profit or loss by the amounts shown below. This analysis assumes that all other variables, in particular interest rates, remained constant and ignores any impact of forecasted sales and purchases.
|
|
|
Profit or (loss) |
|||
|
|
|
2026 |
|
2025 |
|
|
Consolidated |
|
$ |
|
$ |
|
|
|
|
|
|
|
|
|
British Pound |
|
- |
|
- |
|
|
Philippine Peso |
|
7,622 |
|
139,560 |
|
|
US Dollar |
|
- |
|
307,355 |
|
|
|
|
|
|
|
|
|
|
|
7,622 |
|
446,915 |
|
A 10% weakening of AUD against the above currencies at the end of the reporting date would have had equal but opposite effect on the above currencies to the amounts shown above, on the basis that all other variables remain constant.
- Financial risk management (continued)
- Fair value estimation
The fair value of financial assets and financial liabilities must be estimated for recognition and measurement or for disclosure purposes. All financial assets and financial liabilities of the consolidated entity at the reporting date are recorded at amounts approximating their carrying amount. The fair value of financial instruments traded in active markets is based on quoted market prices at the reporting date. The quoted market price used for financial assets held by the consolidated entity is the current bid price. At reporting date the consolidated entity had no such financial assets.
The carrying value less impairment provision of trade receivables and payables are assumed to approximate their fair values due to their short-term nature.
- Contingent assets and liabilities
In the prior year, the parent entity executed a corporate surety agreement in May 2025 to provide a surety to the value of 40% of the amount of the non-current secured loan to its then subsidiary, Makilala Mining Company, Inc. Refer to Note 18 for further details.
The consolidated entity had no other contingent liabilities or contingent assets at 30 June 2026 and 30 June 2025.
|
|
|
|
|
Place formed / |
|
Ownership interest |
|
|
|
Entity name |
|
Entity type |
|
Country of incorporation |
|
% |
|
Tax residency |
|
|
|
|
|
|
|
|
|
|
|
Opuwo Cobalt Mining (Pty) Ltd |
|
Body corporate |
|
Namibia |
|
95.00% |
|
Namibia |
|
Opuwo Cobalt Holdings (Pty) Ltd |
|
Body corporate |
|
Namibia |
|
95.00% |
|
Namibia |
|
Opuwo Cobalt Pty Ltd |
|
Body corporate |
|
Australia |
|
100.00% |
|
Australia |
|
PDEP INC |
|
Body corporate |
|
Philippines |
|
100.00% |
|
Philippines |
|
Tambuli Mining Company, Inc. |
|
Body corporate |
|
Philippines |
|
100.00% |
|
Philippines |
|
PDEP Holdings, LLC |
|
Body corporate |
|
United States of America |
|
100.00% |
|
United States of America |
|
Tambuli, LLC |
|
Body corporate |
|
United States of America |
|
100.00% |
|
United States of America |
|
Makilala Holding Ltd |
|
Body corporate |
|
British Virgin Islands |
|
100.00% |
|
British Virgin Islands |
|
View Nickel Pty Ltd |
|
Body corporate |
|
Australia |
|
100.00% |
|
Australia |
|
Cullarin Metals Pty Ltd |
|
Body corporate |
|
Australia |
|
100.00% |
|
Australia |
|
Celsius Resources Limited |
|
Body corporate |
|
Australia |
|
N/A |
|
Australia |
Celsius Resources and its wholly-owned Australian subsidiaries have formed an income tax consolidated group under the tax consolidation regime.
BASIS OF PREPARATION
The consolidated entity disclosure statement (CEDS) has been prepared in accordance with Section 295 (3A) of the Corporations Act 2001. The entities listed in the statement are Celsius Resources Limited and all the entities it controls in accordance with AASB 10 Consolidated Financial Statements.
DETERMINATION OF TAX RESIDENCY
Section 295 (3A) of the Corporations Act requires that the tax residency of each entity which is included in the CEDS be disclosed. In the context of an entity which was an Australian resident, "Australian resident" has the meaning provided in the Income Tax Assessment Act 1997 (Cth). The determination of tax residency involves judgment as the determination of tax residency is highly fact dependent and there are currently several different interpretations that could be adopted, and which could give rise to a different conclusion on residency.
In determining tax residency, the Consolidated Entity has applied the following interpretations:
AUSTRALIAN TAX RESIDENCY
The Consolidated Entity has applied current legislation and judicial precedent, including having regard to the Commissioner of Taxation's public guidance in Tax Ruling TR 2018/5.
FOREIGN TAX RESIDENCY
The Consolidated Entity has applied current legislation and where available judicial precedent in the determination of foreign residency. Where necessary, the Consolidated Entity has used independent tax advisers in foreign jurisdictions to assist in its determination of tax residency to ensure applicable foreign tax legislation has been complied with.
In the directors' opinion:
- the attached financial statements and notes comply with the Corporations Act 2001, the Accounting Standards, the Corporations Regulations 2001 and other mandatory professional reporting requirements;
- the attached financial statements and notes comply with International Financial Reporting Standards as issued by the International Accounting Standards Board as described in note 1 to the financial statements;
- the attached financial statements and notes give a true and fair view of the consolidated entity's financial position as at 30 June 2026 and of its performance for the financial year ended on that date;
- there are reasonable grounds to believe that the Company will be able to pay its debts as and when they become due and payable; and
- the information disclosed in the attached consolidated entity disclosure statement is true and correct.
The directors have been given the declarations required by section 295A of the Corporations Act 2001.
Signed in accordance with a resolution of directors made pursuant to section 295(5)(a) of the Corporations Act 2001.
On behalf of the directors
Bardin Davis
Managing Director
Date: 30 September 2026
|
Perth |
As at 14 September 2026 the following information applied:
- Equity Securities
The Company has five classes of equity securities, being fully paid ordinary shares (“Shares”), listed options, unlisted options and unlisted warrants. The Shares and listed options are quoted on the Australian Securities Exchange under the codes CLA and CLAOA respectively.
- Distribution of equity securities
- Distribution of fully paid ordinary shares
|
Range |
Total Holders |
Units |
% of Issued Capital |
|
1 – 1,000 |
299 |
9,283 |
0.00% |
|
1,001 – 5,000 |
129 |
499,508 |
0.01% |
|
5,001 – 10,000 |
160 |
1,332,082 |
0.04% |
|
10,001 – 100,000 |
1,156 |
56,793,254 |
1.52% |
|
100,001 – 9,999,999,999 |
1,433 |
3,666,029,878 |
98.43% |
|
Total |
3,177 |
3,724,664,005 |
100.00% |
Unmarketable Parcels
|
|
Minimum Parcel Size |
Holders |
Units |
|
Minimum $500.00 parcel at $0.004 per unit |
125,000 |
1,827 |
67,843,749 |
- Distribution of listed options
|
Range |
Total Holders |
Units |
% of Issued Capital |
|
1 – 1,000 |
- |
- |
- |
|
1,001 – 5,000 |
- |
- |
- |
|
5,001 – 10,000 |
- |
- |
- |
|
10,001 – 100,000 |
13 |
877,238 |
0.21% |
|
100,001 – 9,999,999,999 |
90 |
420,700,675 |
99.79% |
|
Total |
103 |
421,577,913 |
100.00% |
- Distribution of unlisted options
|
Range |
Total Holders |
Units |
% of Issued Capital |
|
1 – 1,000 |
- |
- |
- |
|
1,001 – 5,000 |
- |
- |
- |
|
5,001 – 10,000 |
- |
- |
- |
|
10,001 – 100,000 |
- |
- |
- |
|
100,001 – 9,999,999,999 |
2 |
33,673,355 |
100.00% |
|
Total |
2 |
33,673,355 |
100.00% |
- Distribution of Performance Rights
|
Range |
Total Holders |
Units |
% of Issued Capital |
|
1 – 1,000 |
- |
- |
- |
|
1,001 – 5,000 |
- |
- |
- |
|
5,001 – 10,000 |
- |
- |
- |
|
10,001 – 100,000 |
- |
- |
- |
|
100,001 – 9,999,999,999 |
1 |
100,000,000 |
100.00% |
|
Total |
1 |
100,000,000 |
100.00% |
- Distribution of unlisted warrants
|
Range |
Total Holders |
Units |
% of Issued Capital |
|
1 – 1,000 |
- |
- |
- |
|
1,001 – 5,000 |
- |
- |
- |
|
5,001 – 10,000 |
- |
- |
- |
|
10,001 – 100,000 |
- |
- |
- |
|
100,001 – 9,999,999,999 |
18 |
236,101,390 |
100.00% |
|
Total |
18 |
236,101,390 |
100.00% |
- Top 20 shareholders
|
Rank |
Name |
Units |
% of Units |
|
1 |
CITICORP NOMINEES PTY LIMITED |
400,210,496 |
10.74% |
|
2 |
BNP PARIBAS NOMINEES PTY LTD <IB AU NOMS RETAILCLIENT> |
314,822,711 |
8.45% |
|
3 |
HSBC CUSTODY NOMINEES (AUSTRALIA) LIMITED |
268,447,858 |
7.21% |
|
4 |
COMPUTERSHARE CLEARING PTY LTD <CCNL DI A/C> |
246,067,314 |
6.61% |
|
5 |
BNP PARIBAS NOMS PTY LTD |
109,640,857 |
2.94% |
|
6 |
BNP PARIBAS NOMINEES PTY LTD <CLEARSTREAM> |
60,598,901 |
1.63% |
|
7 |
MR ANDREW GRAHAM PALLESON & MRS HUI PALLESON <PALLESON SUPERFUND A/C> |
60,000,000 |
1.61% |
|
8 |
EMERALD STREET PTY LTD |
56,000,000 |
1.50% |
|
9 |
SHARESIES AUSTRALIA NOMINEE PTY LIMITED |
46,800,207 |
1.26% |
|
10 |
KOZLOWSKI NOMINEES PTY LTD <KOZLOWSKI FAMILY S/F A/C> |
40,000,000 |
1.07% |
|
11 |
MR HAMISH POTATAU GRAHAM COOPER |
34,769,355 |
0.93% |
|
12 |
MARK VAN KERKWIJK |
32,413,273 |
0.87% |
|
13 |
MACDONNELL INVESTMENT GROUP PTY LTD |
32,352,060 |
0.87% |
|
14 |
JSMINDUSTRIES SUPER PTY LTD <JSMINDUSTRIES SUPER S/F A/C> |
30,725,011 |
0.82% |
|
15 |
SUNSET CAPITAL MANAGEMENT PTY LTD <SUNSET SUPERFUND A/C> |
30,000,000 |
0.81% |
|
15 |
MR JABIN GEOFFREY MULLANE |
30,000,000 |
0.81% |
|
16 |
MR PETER PAUL KOZLOWSKI |
28,000,000 |
0.75% |
|
17 |
JAGEORPH PTY LTD <NIKARRY SUPER A/C> |
26,362,228 |
0.71% |
|
18 |
PETER HUME |
26,000,000 |
0.70% |
|
19 |
REGIONAL MANAGEMENT PTY LTD <MVC A/C> |
25,397,827 |
0.68% |
|
20 |
MR JONATHAN COLVILE |
22,461,888 |
0.60% |
|
Total |
1,921,069,986 |
51.57% |
|
|
Total Issued Capital |
3,724,664,005 |
100.00% |
|
- Top 20 Listed option holders
|
Rank |
Name |
Units |
% of Units |
|
1 |
ZEUS CAPITAL LTD |
48,161,247 |
11.42% |
|
2 |
MORGAN STANLEY AUSTRALIA SECURITIES (NOMINEE) PTY LIMITED <NO 1 ACCOUNT> |
30,422,215 |
7.22% |
|
3 |
SILVERCORP METALS INC |
30,116,838 |
7.14% |
|
4 |
JSMINDUSTRIES SUPER PTY LTD <JSMINDUSTRIES SUPER S/F A/C> |
26,500,000 |
6.29% |
|
5 |
MR STEFAN PIRUK |
24,370,192 |
5.78% |
|
6 |
MRS LAURA EVELYN PIRUK |
19,392,870 |
4.60% |
|
7 |
CITICORP NOMINEES PTY LIMITED |
18,889,732 |
4.48% |
|
8 |
MR PETER PAUL KOZLOWSKI |
17,100,733 |
4.06% |
|
9 |
PERSHING NOMINEES LIMITED <WRCLT A/C> |
15,329,100 |
3.64% |
|
10 |
PAC PARTNERS SECURITIES PTY LTD |
14,969,615 |
3.55% |
|
11 |
EMERGING EQUITIES PTY LTD |
13,826,270 |
3.28% |
|
12 |
HSBC CUSTODY NOMINEES (AUSTRALIA) LIMITED |
10,247,719 |
2.43% |
|
13 |
MR ANDREW GRAHAM PALLESON & MRS HUI PALLESON <PALLESON SUPERFUND A/C> |
10,000,000 |
2.37% |
|
13 |
MR ANDREW GRAHAM PALLESON |
10,000,000 |
2.37% |
|
14 |
MARK VAN KERKWIJK |
9,375,000 |
2.22% |
|
14 |
PAUL JAMES DUDLEY |
9,375,000 |
2.22% |
|
15 |
MR NIKITA BALACHOV |
7,771,850 |
1.84% |
|
16 |
REGIONAL MANAGEMENT PTY LTD <MVC A/C> |
6,425,670 |
1.52% |
|
17 |
BILGOLA NOMINEES PTY LIMITED |
5,765,738 |
1.37% |
|
18 |
HURLEY ST PTY LTD <TRINDER FAMILY S/F A/C> |
5,048,495 |
1.20% |
|
19 |
MR WAYNE STEPHEN GLYNNE |
5,000,000 |
1.19% |
|
20 |
MR CLIFTON DOUGLAS WORTHING & MRS HEATHER SIMONE WORTHING |
4,988,855 |
1.18% |
|
Total |
343,077,139 |
81.38% |
|
|
Total Issued Capital |
421,577,913 |
100.00% |
|
- Substantial shareholders
The names of the substantial shareholders listed in the Company’s share register as at 14 September 2026 were:
|
Name |
Units |
% of Units |
|
CITICORP NOMINEES PTY LIMITED |
400,210,496 |
10.74% |
|
BNP PARIBAS NOMINEES PTY LTD <IB AU NOMS RETAILCLIENT> |
314,822,711 |
8.45% |
|
HSBC CUSTODY NOMINEES (AUSTRALIA) LIMITED |
268,447,858 |
7.21% |
|
COMPUTERSHARE CLEARING PTY LTD <CCNL DI A/C> |
246,067,314 |
6.61% |
- On-market buyback
In accordance with ASX Listing Rule 4.10.18, the Company confirms that it is not currently subject to an on-market buyback.
- Voting rights
Shares
All ordinary shares (whether fully paid or not) carry one vote per share without restriction.
Listed options
There are no voting rights attached to the listed options.
Unlisted options
There are no voting rights attached to the unlisted options.
Warrants
There are no voting rights attached to the warrants.
- Unlisted options
The following unlisted options are on issue as at 14 September 2026:
|
Name |
Total Holders |
Units |
|
UNLISTED OPTIONS EXERCISABLE AT $0.025 EACH EXPIRING 30/09/2027 |
2 |
33,673,355 |
|
Total |
2 |
33,673,355 |
Holding more than 20%:
- Patras Capital Pte Ltd hold 30,000,000 (89.09%) of the unlisted options on issue.
- Performance Rights
The following unlisted performance rights are on issue as at 14 September 2026:
|
Name |
Total Holders |
Units |
|
PERFORMANCE RIGHTS EXPIRING 14/03/2028 |
1 |
6,250,000 |
|
PERFORMANCE RIGHTS EXPIRING 14/09/2027 |
1 |
25,000,000 |
|
PERFORMANCE RIGHTS EXPIRING 14/09/2028 |
1 |
38,750,000 |
|
PERFORMANCE RIGHTS EXPIRING 14/09/2029 |
1 |
20,000,000 |
|
PERFORMANCE RIGHTS EXPIRING 14/09/2030 |
1 |
10,000,000 |
|
Total |
1 |
100,000,000 |
Holding more than 20%:
- Baromoda Holdings Pty Ltd holds 100,000,000 (100%) of the unlisted performance rights on issue.
- Unlisted warrants
The following unlisted warrants are on issue as at 14 September 2026:
|
Name |
Total Holders |
Units |
|
WARRANTS EXERCISABLE AT GBP0.008 EACH EXPIRING 28/04/2028 |
1 |
12,500,000 |
|
WARRANTS EXERCISABLE AT GBP0.009 EACH EXPIRING 19/11/2028 |
1 |
5,300,000 |
|
WARRANTS EXERCISABLE AT GBP0.009 EACH EXPIRING 26/12/2026 |
14 |
181,694,414 |
|
WARRANTS EXERCISABLE AT GBP0.005 EACH EXPIRING 31/12/2026 |
6 |
36,606,976 |
|
Total |
22 |
236,101,390 |
Holding more than 20%:
- Pershing Nominees Limited holds 128,008,333 (54%) of the warrants on issue.
- Schedule of interest in mining tenements
|
PERMIT |
PERMIT |
REGISTERED HOLDER / APPLICANT |
PERMIT STATUS |
PERMIT EXPIRY |
INTEREST / CONTRACTUAL RIGHT |
|
Namibia |
|||||
|
Opuwo |
EL 4346 |
Opuwo Cobalt Holdings (Pty) Ltd |
Granted |
TBA |
95% |
|
Philippines |
|||||
|
Maalinao-Caigutan-Biyog |
MPSA-356-2024-CAR |
Makilala Mining Company Inc. |
Granted |
13/03/2049 |
40% |
|
Botilao |
EP-011-2023-CAR |
Makilala Mining Company Inc. |
Granted |
27/01/2028 |
40% |
|
Panaon |
EXPA-000127-VIII |
PDEP, Inc. |
Complying with further permitting requirements |
TBA |
100% |
|
Sagay |
EP-000003-VI |
Tambuli Mining Company Inc. |
Granted |
Automatic extension until the approval of DMPF/MPSA |
100% |
[1] Shareholder approved lowering the exercise price of the options from A$0.035 per share to A$0.022 per share at the Company’s General Meeting on 9 September 2026.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 19 minutes ago Liontrust Asset Management
- 19 minutes ago Quantum Helium Limited
- 2 hours ago Microsalt
- 2 hours ago Arrow Exploration Corp. (Cdi)
- 3 hours ago VP