
NAV and Investment Update

NOT FOR RELEASE, PUBLICATION OR DISTRIBUTION IN WHOLE OR IN PART IN OR INTO THE UNITED STATES
Sequoia Economic Infrastructure Income Fund Limited ("SEQI" or the "Company")
MONTHLY UPDATE & COMMENTARY - September 2026
The NAV per share for SEQI, the largest LSE listed infrastructure debt fund, decreased to 90.43 pence per share from the prior month's NAV per share of 91.50 pence, representing a decrease of 1.07 pence per share.
|
|
pence per share |
|
31 August NAV |
91.50 |
|
Interest income, net of expenses |
0.57 |
|
Asset valuations, net of FX movements |
-1.64 |
|
Subscriptions / share buybacks |
0.00 |
|
30 September NAV |
90.43 |
Interest income, net of expenses, of 0.57 pence per share partially offset the 1.64 pence per share decline in asset valuations, net of FX movements, resulting in an overall NAV decrease of 1.07 pence per share.
Asset valuations, net of FX movements, declined by 1.64 pence per share during September, comprising:
· 1.05 pence per share, of which a decline of 0.95 pence per share was due to adjustments to Active Care Group ("ACG"), as outlined in the "Ongoing investment in ACG" section below.
· 0.27 pence per share from lower fixed-rate loan valuations, largely driven by the material rise in risk-free rates during September. These unrealised mark-to-market losses attributable to interest-rate movements are expected to unwind as investments approach repayment.
· 0.32 pence per share from other valuation and FX movements, mostly driven by unrealised FX losses on the hedging book.
As the portfolio is approximately 100% currency-hedged, no material net FX gains or losses are expected over time. However, differences in the valuation methodologies used for FX hedges and the underlying investments can give rise to short-term unrealised FX movements in the NAV. These fluctuations typically reverse over time.
Key Performance Highlights - September 2026
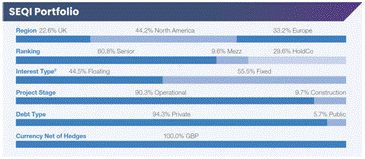
Dividend yield of 8.10%[1], based on the closing share price of 84.90 pence as at 30 September and the annual dividend target of 6.875 pence per share.
Weighted average portfolio yield-to-worst ("YTW") was 9.61% as at 30 September, reflecting the portfolio's strong income returns.
Portfolio pull-to-par[2] (which is incremental to NAV as loans mature over time) was 4.53 pence per share as at 30 September, increasing from 4.29 pence per share as at 31 August.
12-month (to 30 September) share price total return was 18.64%.
|
Performance Highlights |
|
|
|
|
Cumulative Total Returns |
1Y |
3Y |
5Y |
|
NAV |
3.87% |
21.29% |
25.15% |
|
Share Price |
18.64% |
31.83% |
18.25% |
Market Summary - September 2026
|
· |
Risk-free rates increased sharply across SEQI's key investment regions during September. The US 5-year Treasury yield rose by 0.60% to 5.09%, the UK 5-year gilt yield by 0.35% points to 4.98%, and the German 5-year government bond yield by 0.30% points to 3.33%. These increases generally resulted in downward valuation movements for the portfolio's fixed-rate investments, equivalent to 0.27 pence per share.
|
|
|
· |
Elevated energy prices, particularly diesel, continued to exert inflationary pressure through higher transport, logistics and production costs. The Investment Adviser expects these pressures to persist while the Russia-Ukraine war and conflicts in the Middle East continue to disrupt refining capacity and energy supplies.
|
|
|
· |
Eurozone headline inflation increased to 3.2% in August, UK CPI rose to 3.1%, and US headline inflation remained elevated at 3.4%. At their September meetings, each of the Federal Reserve and ECB increased interest rates by 0.25%, while the Bank of England maintained the rate at 3.75%.
|
|
|
· |
In a higher interest-rate environment, SEQI benefits from its dynamic interest-rate positioning, with 55.5% of the portfolio invested in fixed-rate instruments as at 30 September. |
|
|
· |
Credit spreads remain tight relative to historical averages. Any resulting market dislocation or spread widening may create opportunities for SEQI to originate new loans at attractive risk-adjusted returns, supported by its disciplined credit approach and flexible investment strategy.
|
Portfolio Update - September 2026
Revolving Credit Facility and Cash Holdings
|
· |
As at 30 September, SEQI had drawn £87.9 million under its £250 million revolving credit facility and held cash of £41.2 million, inclusive of interest income. Net undrawn investment commitments stood at £54.0 million. |
New Investment Activity - September 2026
|
· |
A senior secured loan of $60 million extended for Project Cloud, financing the acquisition of a portfolio of six operating power generation assets in New York State with a combined capacity of approximately 1.55 GW. Taking account of upfront fees and when converted into SEQI's base currency, the yield to maturity ("YTM") on this loan is 10.34%. |
|
· |
A drawdown of €4.4 million by Portuguese High-Speed Rail, a project company developing a high-speed railway line in Portugal connecting Porto to Aveiro, forming part of the wider Lisbon-Porto high-speed rail corridor. SEQI's total commitment is €24.0 million. When converted into SEQI's base currency, the YTM on this loan is approximately 9.44%. |
|
· |
A drawing of approximately £5.2 million by ACG Bidco Ltd under a senior loan facility. An update on the company's exposure to the Active Care Group and exit strategy is covered in more detail below. |
No investments repaid during September.
Ongoing investment in ACG
Active Care Group, or ACG, is the UK's leading provider of complex care, with over 5,000 employees and supporting over 2,000 people each day. Services include neuro-rehabilitation, brain and spinal injury, learning disabilities and autism, and adult mental health, and are provided through a mixture of specialist hospitals, residential facilities and care in the home. The Company acquired the entire share capital of ACG in May 2024 following a restructuring of the business. Since then, the Company has provided funding to improve the quality of clinical care, as evidenced by materially better Care Quality Commission ratings across its estate.
The Company's current exposure to ACG consists of various classes of senior loans, totalling 5.0% of NAV, that are held at the operating company level and are supported by underlying assets and cash flows from the business. In addition, SEQI has exposure to ACG through a Holdco loan, currently equal to 1.3% of NAV, which is held higher in the ACG group capital structure, the value of which is dependent upon the residual value of the ACG group business after its senior debt has been repaid. This economic substance of this tranche is, equivalent to the full equity interest in the business.
The exit strategy from ACG is continuing and consists of three phases:
1. A strategic refocus of the ACG business, which is already underway, from a predominantly public-sector funded revenue model to one with a significantly higher proportion of private-pay revenues, which are generally more profitable and typically more resilient to cost pressures. This business, under the Active Neuro brand, will focus on neuro rehabilitation, which is regarded as a fast-growing, under-served and high-margin sector of the UK healthcare market. This transition of the ACG business will involve both opening new facilities and repositioning existing ones. The Company will be providing financial support to ACG with funding for capex to bring new facilities into active service delivery, and funding for certain opex items which include costs associated with existing facilities that are being re-positioned. This additional future funding is estimated to be approximately 0.9% of current NAV of SEQI, which equates to approximately £12.5 million, and is expected to be largely provided to ACG over the next three months.
2. In parallel with the re-orientation of its business portfolio, ACG is in the process of a disposal programme involving divesting certain non-core and relatively low-growth business divisions. This asset optimisation process began with the successful disposal of Remeo, a specialist provider of inpatient ventilator weaning and respiratory rehabilitation care, to SOL Group earlier this year. Further disposals are expected over the coming 12 months. Proceeds from these disposals are expected to reduce group indebtedness and provide further funding for investment into growth opportunities within the Active Neuro division.
3. SEQI intends to fully exit from the business after the Active Neuro division has scaled up and the completion of the disposal programme. Additionally, it may be possible for ACG to raise third-party funding prior to that, which may result in a reduction in SEQI's exposure to the business.
The Company is mindful of the execution risks associated with delivering the exit strategy outlined above, notably the successful disposal of non-core assets and the pivot to a business with a much higher exposure to the private sector. The current valuation of its investment in ACG reflects the present value of an estimate of the final exit value of the business, taking account of a range of outcomes of ACG's strategy. The Company is closely monitoring and will continue to incorporate any changes in expected outcomes into the modelling used in SEQI's published monthly valuations.
Asset valuations are independently reviewed every month by PricewaterhouseCoopers LLP ("PwC").
Portfolio Composition
|
· |
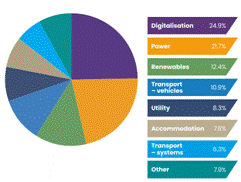
SEQI's invested portfolio as at 30 September consisted of 49 private debt investments and two infrastructure bonds, diversified across 8 sectors and 25 sub-sectors.
|
|
· |
Private debt investments which allow SEQI to capture illiquidity yield premiums, represented 94.3% of the total portfolio.
|
|
· |
The weighted average loan life was 3.1 years. |
|
|
|
|
· |
SEQI's portfolio remained geographically diversified, with 44.2% of investments located in the U.S., 22.6% in the U.K. and 33.2% in Europe. |
Non-performing Loans - September 2026
|
· |
SEQI continues to work towards maximising recovery from two non-performing loans in the portfolio (representing 1.4% of NAV[3]). There are no additional updates on non-performing loans during September. |
Diversified Portfolio
Portfolio by Sector
Top 15 Individual Debt Investments
|
Transaction name |
Currency |
% of SEQI Portfolio |
Type |
Ranking |
Value £mm |
Sector |
Sub-sector |
Cash-on-cash yield (%) |
Yield to worst (%) |
|
AP Wireless Junior |
EUR |
4.4% |
Private |
Mezz |
60.0 |
Digitalisation |
Telecom Towers |
6.90 |
8.56 |
|
Grange Backup Power |
EUR |
4.1% |
Private |
Senior |
56.7 |
Power |
Standby Generators |
9.50 |
9.28 |
|
OCU |
GBP |
3.8% |
Public |
Senior |
52.5 |
Utility |
Utility Services |
8.24 |
8.20 |
|
Muehlhan |
EUR |
3.8% |
Private |
Senior |
51.9 |
Other |
Renewables Equipment & Services |
7.91 |
7.33 |
|
ACG BidCo Ltd C |
GBP |
3.6% |
Private |
Senior |
49.5 |
Accommodation |
Health Care |
0.00 |
17.00 |
|
Project Hero |
EUR |
3.6% |
Private |
Senior |
49.5 |
Transport - vehicles |
Health & Safety |
6.73 |
7.72 |
|
Expedient |
USD |
3.6% |
Private |
Senior |
49.1 |
Digitalisation |
Data Centres |
8.63 |
8.60 |
|
Project Sienna |
GBP |
3.5% |
Private |
Senior |
48.8 |
Renewables |
Waste to Energy |
10.05 |
11.43 |
|
Hawkeye Solar |
USD |
3.5% |
Private |
HoldCo |
48.4 |
Renewables |
Solar & Wind |
9.05 |
11.33 |
|
Project Cloud |
USD |
3.3% |
Private |
Senior |
45.2 |
Power |
Energy Transition (Peaker) Plant |
9.58 |
9.58 |
|
Project Dynamo |
USD |
3.3% |
Private |
HoldCo |
45.2 |
Power |
Standby Generators |
9.16 |
9.16 |
|
Community Fibre |
GBP |
3.2% |
Private |
Senior |
44.6 |
Digitalisation |
Broadband & Fibre |
8.02 |
8.20 |
|
Kenai HoldCo 2024 |
EUR |
3.2% |
Private |
HoldCo |
44.0 |
Power |
Base Load |
0.00 |
17.26 |
|
Project Tyre |
USD |
3.1% |
Private |
Senior |
42.5 |
Transport - vehicles |
Specialist Shipping |
9.83 |
9.82 |
|
Salt Creek Second Out 2L Facility 2027 |
USD |
3.1% |
Private |
Senior |
42.4 |
Utility |
Midstream |
0.00 |
7.50 |
Top 10 Aggregate Debt Exposures
|
Transaction name |
Currency |
Type |
Country |
Ranking |
Value £mm |
Sector |
Sub-sector |
% of SEQI Portfolio |
|
ACG BidCo Ltd |
GBP |
Private |
UK |
Senior |
68.4 |
Accommodation |
Health Care |
5.0% |
|
AP Wireless Junior |
EUR |
Private |
US |
Mezz |
60.0 |
Digitalisation |
Telecom Towers |
4.4% |
|
Grange Backup Power |
EUR |
Private |
US |
Senior |
57.1 |
Power |
Standby Generators |
4.1% |
|
Kenai & KWO |
EUR |
Private |
Germany |
HoldCo & Mezz |
56.4 |
Power |
Base Load |
4.1% |
|
OCU |
GBP |
Public |
UK |
Senior |
52.5 |
Utility |
Utility Services |
3.8% |
|
Salt Creek 1L & 2L Facilities |
USD |
Private |
US |
Senior |
52.4 |
Utility |
Midstream |
3.8% |
|
Muehlhan |
EUR |
Private |
Germany |
Senior |
51.9 |
Other |
Renewables Equipment |
3.8% |
|
Project Hero |
EUR |
Private |
Spain |
Senior |
49.5 |
Transport - vehicles |
Health & Safety |
3.6% |
|
Expedient |
USD |
Private |
US |
Senior |
49.1 |
Digitalisation |
Data Centres |
3.6% |
|
Project Sienna |
GBP |
Private |
UK |
Senior |
48.8 |
Renewables |
Waste to Energy |
3.5% |
|
Hawkeye Solar |
USD |
Private |
US |
HoldCo |
48.4 |
Renewables |
Solar & Wind |
3.5% |
Equity or Equity-like Investments
|
Transaction name |
Currency |
Type |
Country |
Ranking |
Value £mm |
Sector |
Sub-sector |
% of SEQI Portfolio |
|
Gadwall Holdings Ltd |
GBP |
Private |
UK |
HoldCo |
17.4 |
Accommodation |
Health Care |
1.3% |
|
Clyde Street Earn-out |
GBP |
Private |
UK |
Senior |
11.2 |
Other |
Hospitality |
0.8% |
|
Salt Creek Equity |
USD |
Private |
US |
HoldCo |
9.3 |
Utility |
Midstream |
0.7% |
Notes:
· De minimis positions excluded
· Valuations are independently reviewed each month by PwC.
http://www.rns-pdf.londonstockexchange.com/rns/0225Z_1-2026-10-14.pdf
http://www.rns-pdf.londonstockexchange.com/rns/0225Z_2-2026-10-14.pdf
Share Buybacks - September 2026
|
· |
SEQI did not repurchase any ordinary shares during September 2026.
|
|
· |
SEQI first started buying back shares in July 2022 and since then to the end of September 2026, has spent £242.1 million buying back 300,905,720 ordinary shares.
|
|
· |
The Board applies a dynamic approach to share buybacks which takes into account available portfolio liquidity, the relative trading discount to NAV per share and other relevant factors.
|
|
· |
The share buyback programme will continue to remain in place and delivers a positive contribution to NAV per share.
|
About Sequoia Economic Infrastructure Income Fund Limited
|
· |
SEQI is the UK's largest listed debt fund, investing in economic infrastructure private loans and bonds across a range of industries in stable, low-risk jurisdictions, creating equity-like returns with the protections of debt. |
|
· |
SEQI's loans are high quality and have robust covenants. It lends to companies that have a track record of consistent cash flow generation and which are backed by physical assets. This enables SEQI to benefit from exposure to an asset class with robust fundamentals as well as the opportunity for attractive returns. |
|
· |
SEQI seeks to provide investors with regular, sustained, long-term income with opportunity to benefit from NAV upside from its well diversified portfolio. Investments are typically non-cyclical, in industries that provide essential public services or in evolving sectors such as energy transition, digitalisation or healthcare. |
|
· |
Since its launch in 2015, SEQI has provided investors with 11 years of quarterly income, consistently meeting its annual dividend per share target, which has grown from 5.0 pence in 2015 to 6.875 pence per share. |
|
· |
SEQI has a comprehensive sustainability framework, combining i) negative screening, ii) thematic investing (positive screening), both of which again received independent limited assurance this year, and iii) a proprietary ESG scoring methodology, which has been redesigned this year and now comprises a new ESG Risk Score and a new Externality Score. This new dual-scoring framework represents a significant evolution from the previous single-score approach and is designed to provide more structured, balanced, value-focused decision-useful insights. |
|
· |
SEQI is advised by SIMCo, a long-standing investment advisory team with extensive infrastructure debt origination, analysis, structuring and investment execution experience. |
|
· |
SEQI's monthly updates are available here: Seqifund/investors/monthly-updates |
For further information please contact:
|
Investment Adviser Sequoia Investment Management Company Limited Steve Cook Dolf Kohnhorst Randall Sandstrom Anurag Gupta |
+44 (0)20 7079 0480
|
|
|
|||||
|
|
|
|
|
|||||
|
Joint Corporate Brokers and Financial Advisers Jefferies International Limited Gaudi Le Roux Harry Randall |
+44 (0)20 7029 8000 |
|
|
|||||
|
|
|
|||||||
|
J.P. Morgan Cazenove Rupert Budge William Simmonds
|
+44 (0)20 7742 4000 |
|
|
|||||
|
Public Relations Sodali Justin Griffiths Gilly Lock Madeleine Gordon-Foxwell
|
+44 (0)20 7250 1446
|
|
|
|||||
|
Alternative Investment Fund Manager (AIFM) FundRock Management Company (Guernsey) Limited Ben Snook Chris Hickling
|
|
|
|
|||||
|
Administrator / Company Secretary Apex Fund and Corporate Services (Guernsey) Limited Aoife Bennett
|
+44 (0)20 7592 0419 admin.sequoia@apexgroup.com |
|
|
This announcement is not for publication or distribution, directly or indirectly, in or into the United States of America. This announcement is not an offer of securities for sale into the United States. The securities referred to herein have not been and will not be registered under the U.S. Securities Act of 1933, as amended, and may not be offered or sold in the United States, except pursuant to an applicable exemption from registration. No public offering of securities is being made in the United States.
[1] The dividend yield is calculated by dividing the annual dividend target by the relevant share price.
[2] The pull-to-par includes the mark-to-market of SEQI's interest rate swaps, capturing the valuation impact of hedging floating rate assets into fixed rate exposure.
[3] SEQI now includes accrued interest when calculating non-performing loans as a percentage of the portfolio. This change explains the increase from 0.7% as at August 2026. The number of non-performing loans remains unchanged. Using the same methodology in August 2026, the two non-performing loans represented 1.4% of NAV.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 1 day ago Tesco
- 1 day ago Dr. Martens
- 1 day ago YouGov
- 1 day ago Vistry Group
- 1 day ago Cohort