
SPA executed for Kamiesberg Mineral Sands Project
Summary by AI BETAClose X

NOT FOR RELEASE, PUBLICATION OR DISTRIBUTION, IN WHOLE OR IN PART, IN, INTO OR FROM ANY JURISDICTION WHERE TO DO SO WOULD CONSTITUTE A VIOLATION OF THE RELEVANT LAWS OF THAT JURISDICTION. THIS ANNOUNCEMENT IS FOR INFORMATION PURPOSES ONLY AND IS NOT AN OFFER OF SECURITIES IN ANY JURISDICTION.
THIS IS AN ANNOUNCEMENT AND NOT A CIRCULAR OR PROSPECTUS AND INVESTORS SHOULD NOT MAKE ANY INVESTMENT DECISION ON THE BASIS OF ITS CONTENTS. A COMBINED CIRCULAR AND PROSPECTUS IN RELATION TO THE PROPOSED ACQUISITION DESCRIBED IN THIS ANNOUNCEMENT WILL BE PUBLISHED IN DUE COURSE.
THIS ANNOUNCEMENT CONTAINS INSIDE INFORMATION
FOR IMMEDIATE RELEASE
28 September 2026
Amigo Resources PLC
Share Purchase Agreement executed for the Kamiesberg Mineral Sands Project
Amigo Resources PLC ("Amigo", the "Company" or, together with its subsidiaries and subsidiary undertakings from time to time, the "Amigo Group"), is pleased to announce that its subsidiary, Rare Earths Development Pte Ltd ("Amigo SPV"), has agreed to acquire the Kamiesberg Project (defined below) through the acquisition of 100% of the equity of Zirco Resources (SA) Holdings (Pty) Ltd ("Zirco SA") and Cyndara 14 (Pty) Ltd ("Cyndara") (the "Proposed Acquisition") for USD 33 million on a working capital adjusted, cash-free and debt-free basis (the "Purchase Price").
Highlights
|
● |
SPA Executed: Amigo SPV has executed a share purchase agreement for the acquisition of the Kamiesberg Project through the acquisition of 100% of the equity of Zirco SA and Cyndara for USD 33 million on a working capital adjusted, cash-free and debt-free basis. |
|
|
● |
Acquisition and Development Funding: Amigo intends to fund the Purchase Price and Development Funding through a combination of internal sources of funds and raising debt and/or equity directly in the Amigo SPV. |
|
|
● |
Structure of Proposed Acquisition: Amigo to continue its ownership and investment strategy, consistent with its Tanzanian gold operations, through taking a controlling stake in the asset with equity dilution occurring at the asset level. |
|
|
● |
Proposed Structure at Completion: on Completion, and subject to Ownership Adjustments, Amigo intends to own 51% of Amigo SPV, that will own the Kamiesberg Project. |
|
|
● |
Amigo Appointed Operator: Amigo to be appointed the manager and operator of the Kamiesberg Project. |
|
|
● |
Transformative: the Proposed Acquisition will expand Amigo's African operating footprint to include South Africa. |
|
|
● |
Significant JORC Resource: 2.71 billion tonnes of JORC Resource, including 0.48 billion tonnes of Measured Resource. |
|
|
● |
Completion of Proposed Acquisition: subject to satisfaction of customary conditions precedent, Amigo is targeting to complete the Proposed Acquisition on or before 31 January 2027. |
|
|
● |
Disciplined, Phased Modular Development Strategy: |
|
|
|
- |
Shovel-ready project with advanced permitting, including a mining right, water use licence and environmental authorisation in place. |
|
|
- |
Phased execution plan targeting an aggregate processing capacity of approximately 16 Mtpa across up to five standardised units (delivering approximately 3.3 Mtpa each). |
|
|
- |
Module 1 estimated at approximately US$15 million, is targeted for commissioning within six months of Completion. |
|
|
- |
Early operational cash flows from Module 1 are intended to fund subsequent modules incrementally, significantly reducing upfront capital demands and avoiding excessive corporate debt or asset-level dilution. |
Overview of Proposed Acquisition
The Proposed Acquisition involves Amigo SPV entering into a share purchase agreement (the "SPA") with Zirco Resources Proprietary Limited, Millrex Investments Limited and Lelau Mohuba Trust (the "Sellers").
The Proposed Acquisition, should it complete, will constitute a reverse takeover for the purposes of the UK Listing Rules of the Financial Conduct Authority (the "FCA") (the "UKLRs") and is therefore notifiable in accordance with UKLR 7.5.1R(1). Pursuant to UKLR 7.5.1R(2), a combined prospectus and a shareholder circular for the Proposed Acquisition will be published by the Company in due course (the "Prospectus").
Unless otherwise stated, all information provided is based on the successful completion of the Proposed Acquisition ("Completion").
With respect to the financial information presented within this announcement for Zirco SA, Zirco Roode, and Cyndara, it has been prepared in line with accounting policies and presentation applied in Zirco SA's audited financial statements for the year ended 31 December 2024.
In the event that the Proposed Acquisition cannot proceed to Completion, the Company will provide an update through the Regulatory News Service of London Stock Exchange plc (the "London Stock Exchange") as appropriate.
Overview of Kamiesberg Project
Zirco Roode's principal asset is the Kamiesberg Mineral Sands Project, located on the West Coast of South Africa in the Namaqualand Administrative District of the Northern Cape Province (the "Kamiesberg Project"):
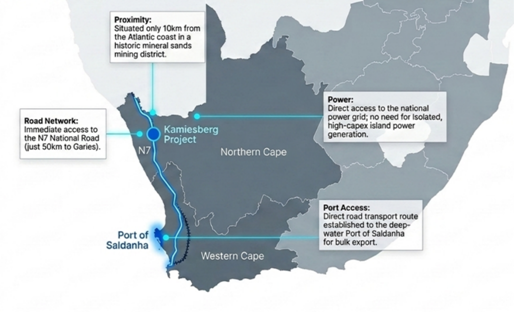
The Kamiesberg Project has a JORC Resource of 2.71 billion tonnes, including 0.48 billion tonnes of Measured Resource:
|
Resource Category |
Volume (Mm³) |
Tonnes (M) |
THM % |
Silt % |
Ovz % |
Ilm % |
Leu % |
Mon % |
Rut % |
Zir % |
RD |
|
Measured |
256.63 |
482.29 |
3.91 |
14.98 |
2.13 |
3.14 |
0.08 |
0.04 |
0.06 |
0.15 |
1.88 |
|
Indicated |
894.49 |
1,692.13 |
3.25 |
19.37 |
3.23 |
2.59 |
0.10 |
0.03 |
0.05 |
0.13 |
1.89 |
|
Inferred |
286.80 |
540.30 |
2.91 |
17.01 |
4.22 |
2.39 |
0.07 |
0.03 |
0.04 |
0.11 |
1.89 |
|
Grand Total |
1,437.92 |
2,714.72 |
3.30 |
18.12 |
3.23 |
2.65 |
0.09 |
0.03 |
0.05 |
0.13 |
1.89 |
Source: The above technical information has been extracted from the GeoActiv Competent Person's Report on the Kamiesberg Project, which will be included in the Prospectus (subject to any necessary updates and amendments in accordance with the JORC Code and other applicable reporting standards, as determined by the Competent Person).
Refer to Appendix III, Part One for further information on the Kamiesberg Project.
Target Financial Statements
As indicated above, Amigo SPV is acquiring 100% of the Kamiesberg Project through the acquisition of 100% of the equity of Zirco SA and Cyndara. The Purchase Price is on a working capital adjusted, cash-free and debt-free basis - and therefore, the external debt owing to Zirco Resources Pty Ltd reduces the Purchase Price payable.
A combined view (non-IFRS compliant) of the entities being acquired by Amigo SPV is outlined below:
Statement of Financial Position: Zirco SA (including Zirco Roode), Cyndara
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Unaudited |
Unaudited |
Unaudited |
|
Property, plant and equipment |
638,716 |
505,923 |
362,295 |
|
Intangible assets |
256,093,412 |
318,807,461 |
324,238,401 |
|
Non-current assets |
256,732,128 |
319,313,384 |
324,600,696 |
|
Trade and other receivables |
6,189,377 |
646,575 |
374,379 |
|
Cash and cash equivalents |
8,597,706 |
2,948,249 |
853,644 |
|
Current assets |
14,787,083 |
3,594,824 |
1,228,023 |
|
Total assets |
271,519,211 |
322,908,208 |
325,828,719 |
|
Trade and other payables |
23,308,894 |
11,480,083 |
9,083,525 |
|
Current liabilities |
23,308,894 |
11,480,083 |
9,083,525 |
|
Loan from Zirco Resources Ltd |
309,669,121 |
380,675,816 |
390,231,147 |
|
Non-current liabilities |
309,669,121 |
380,675,816 |
390,231,147 |
|
Total liabilities |
332,978,015 |
392,155,899 |
399,314,672 |
|
Share capital |
100 |
100 |
100 |
|
Accumulated loss |
(61,458,904) |
(69,247,791) |
(73,486,053) |
|
Equity |
(61,458,804) |
(69,247,691) |
(73,485,953) |
|
Total equity and liabilities |
271,519,211 |
322,908,208 |
325,828,719 |
Statement of Comprehensive Income: Zirco SA (including Zirco Roode), Cyndara
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Unaudited |
Unaudited |
Unaudited |
|
Other operating income |
3,817 |
4,577 |
5,232 |
|
Other operating expenses |
(6,141,061) |
(7,798,057) |
(4,245,695) |
|
Operating loss |
(6,137,244) |
(7,793,480) |
(4,240,463) |
|
Investment income |
3,429 |
4,666 |
2,202 |
|
Loss for the year |
(6,133,815) |
(7,788,814) |
(4,238,261) |
|
Other comprehensive income |
- |
- |
- |
|
Total comprehensive loss for the year |
(6,133,815) |
(7,788,814) |
(4,238,261) |
Statement of Cash Flows: Zirco SA (including Zirco Roode), Cyndara
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Unaudited |
Unaudited |
Unaudited |
|
Loss before taxation |
(6,133,815) |
(7,788,814) |
(4,238,261) |
|
Adjustments for non-cash items |
|
|
|
|
Depreciation |
- |
158,792 |
143,628 |
|
Changes in working capital: |
|
|
|
|
(Increase)/decrease in trade and other receivables |
(5,879,288) |
5,542,802 |
272,196 |
|
Increase/(decrease) in trade and other payables |
12,107,478 |
(11,828,810) |
(2,396,559) |
|
Net cash from operating activities |
94,375 |
(13,916,030) |
(6,218,996) |
|
Purchase of property, plant and equipment |
(715,580) |
(25,999) |
- |
|
Purchases of intangible assets |
(58,634,801) |
(62,714,049) |
(5,430,940) |
|
Net cash from investing activities |
(59,350,381) |
(62,740,048) |
(5,430,940) |
|
Repayments of loans from group companies |
- |
- |
- |
|
Increase/(decrease) in shareholders loans |
67,375,220 |
71,006,695 |
9,555,331 |
|
Net cash from financing activities |
67,375,220 |
71,006,695 |
9,555,331 |
|
Total cash movement for the year |
8,119,214 |
(5,649,383) |
(2,094,605) |
|
Cash and cash equivalents at the beginning of the year |
478,492 |
8,597,706 |
2,948,323 |
|
Cash and cash equivalents at the end of the year |
8,597,706 |
2,948,323 |
853,718 |
Refer to Appendix III, Part Three for the financial statements of Zirco SA (including Zirco Roode) and Cyndara.
Proposed Acquisition Highlights
The Amigo Group's strategic focus is to:
|
● |
Expand its geographical footprint in Africa; |
|
● |
Diversify its operations, including commodities and operations; and |
|
● |
Acquire shovel-ready, long-life projects. |
The board of directors of Amigo (the "Board") believes the Proposed Acquisition represents a material transaction that is in line with the Company's strategy and which will deliver significant value creation for Amigo shareholders ("Shareholders").
The Proposed Acquisition will deliver a step change in the Amigo Group's JORC Resources: the Kamiesberg Project holds more than 2.71 billion tonnes of JORC Resource, including 0.48 billion tonnes of Measured Resource.
Once developed and commercial production is achieved, the Kamiesberg Project is expected to provide:
|
● |
An operational and production step change, with operations in multiple jurisdictions: gold in Tanzania, and heavy mineral sands in South Africa. |
|
● |
Diversification of commodity base: producing free cash flow from gold and heavy mineral sands. |
|
● |
Balance sheet resilience: enhancing the financial strength of Amigo through an increased operating base. |
|
● |
Increased shareholder returns: more diversified framework for providing increased and more sustainable shareholder returns. |
Consideration Structure and Financing
Amigo's Board and senior management team have extensive experience in raising both equity and debt for mining transactions. The Company is drawing on this direct expertise and experience and intends to fund the Purchase Price and Development Funding by raising debt and/or equity directly in Amigo SPV and from internal sources of funds. The Company is in numerous discussions, all at varying stages, with institutions that provide debt and/or equity funding for projects like the Kamiesberg Project.
Proposed Ownership Structure on Completion
Under the proposed structure on Completion, which is subject to Ownership Adjustments, Amigo intends to own 51% of Amigo SPV, that will own the Kamiesberg Project.
Craig Ransley, Executive Chair of Amigo, commented:
"The Board unanimously intends to recommend this transformative transaction to shareholders as being in the best interests of both Amigo and our shareholders. Acquiring the world-class Kamiesberg Project, with its extensive JORC Resources, marks a dynamic new chapter in our growth as an African-focused miner, accelerating our strategic expansion into gold and critical rare earth commodities.
This transaction integrates seamlessly into Amigo's platform, extending our footprint into South Africa: a world-renowned mining jurisdiction with a legendary heritage and enduring leadership in critical minerals.
We are taking a fresh, disciplined approach to developing Kamiesberg through a phased, modular processing configuration. This strategy establishes a clear, scalable roadmap to reach an aggregate processing capacity of up to 16Mtpa across five standardised 3.3Mtpa units, while substantially de-risking early execution. Crucially, our initial module requires an estimated capital expenditure of approximately US$15 million and is targeted for commissioning within just six months of Completion. By achieving near-term production, operating cash flows generated from this first phase can be progressively reinvested into subsequent modular expansions-funding our growth organically while protecting shareholders from excessive debt or asset-level dilution."
Carlo Baravalle, Founding Partner of AMED Funds, commented:
"The divestment of the Kamiesberg Project to Amigo marks another key milestone for AMED, representing our second major transaction with this exceptional leadership team.
We previously partnered with Craig (Ransley) and Nathan (Boom) during their tenures as Executive Chair and Chief Commercial Officer at ASX-listed TerraCom Limited through the divestment of Universal Coal plc, a deal that remains one of our fund's standout investments. We backed Universal from its infancy during the development of its very first mine, continuing our support as it grew into a thriving operator of four thermal coal mines.
As an investment fund, our primary focus is ensuring our assets are entrusted to teams with the proven capability to realise their full potential. Amigo's management team has a compelling track record of doing precisely that. Their disciplined approach to operational delivery creates lasting value for all stakeholders, driving meaningful economic development, generating local employment, and supporting surrounding communities."
CONTACTS
|
Amigo Resources PLC |
investors@amigo.me |
|
Craig Ransley |
Executive Chair |
|
Nathan Boom
|
Chief Executive Officer |
|
|
|
|
Shore Capital (Corporate Broker & Sponsor) Toby Gibbs Sophie Collins |
020 7408 4090
|
APPENDIX I
FURTHER INFORMATION ABOUT THE PROPOSED ACQUISITION
Background on the Proposed Acquisition
Amigo is a public limited company registered in England and Wales with registered number 10024479. Amigo is focussed on gold, platinum group metals, and rare earth mining opportunities in Africa, principally in Tanzania and Mauritania.
The Amigo Group's strategic focus is to:
|
● |
Expand geographical footprint in Africa; |
|
● |
Diversify its operations, including commodities and operations; and |
|
● |
Acquire shovel-ready, long-life projects. |
The Board believes the Proposed Acquisition represents a material transaction that is in line with the Company's strategy and which will deliver significant value creation for Shareholders.
The Kamiesberg Project is a heavy mineral sands group of tenements composed of a mining right and two prospecting rights located in the Northern Cape Province of South Africa with an extensive 2.71 billion tonne JORC Resource. As a result of this, the Kamiesberg Project represents a large-scale tenement base with substantial JORC Resources that is expected to fit into Amigo's existing platform and focus - being an African-centric miner focused on gold and rare earth commodities.
Geographical diversification into South Africa for Amigo represents a logical step, with South Africa being a historically pioneering and globally significant mining jurisdiction with continued leadership in several critical mineral commodities.
Completion Conditions
As indicated above, the Proposed Acquisition constitutes a reverse takeover for Amigo for the purposes of the UKLRs. Therefore, the admission of the Company's ordinary shares (the "Ordinary Shares") in issue to the Equity Shares (Commercial Companies) category of the Official List maintained by the FCA (the "Official List") and to trading on the Main Market of the London Stock Exchange (the "Main Market") will be cancelled on Completion, with the intention that applications will be made to the FCA and the London Stock Exchange, respectively, to readmit the Ordinary Shares of the Company as enlarged by the Proposed Acquisition (the "Enlarged Group") to listing on the Equity Shares (Commercial Companies) category of the Official List and to trading on the Main Market of the London Stock Exchange following Completion.
The Proposed Acquisition is therefore conditional on, among other things:
|
● |
The approval by Shareholders of a resolution (the "Resolution") at a general meeting of the Company to be held at a time and date to be set out in the Prospectus (the "General Meeting"). |
|
● |
The publication of the Prospectus in relation to the Proposed Acquisition. |
|
● |
FCA and London Stock Exchange approval of the re-admission of all Ordinary Shares to listing on the Equity Shares (Commercial Companies) category of the Official List and to trading on the Main Market ("Re-admission"). |
The Proposed Acquisition is also conditional on the consent of the South African Minister of Mineral Resources and Energy under section 11 of the South African Mineral and Petroleum Resources Development Act, No. 28 of 2002, as amended (the "MPRDA"), for the change of control in Zirco Roode being obtained on an unconditional basis or on conditions acceptable to Amigo SPV.
There is no guarantee that the Completion Conditions will be satisfied (or waived, if applicable) before 31 March 2027 (the "Long Stop Date"), and the Proposed Acquisition may, therefore, be delayed or not complete. Provided the Completion Conditions are satisfied by the Long Stop Date, Completion is expected to occur on or before 31 January 2027. Re-admission is expected to occur on the business day following Completion.
The parties to the SPA have undertaken to use reasonable endeavours to fulfil the Completion Conditions.
Consideration Structure and Financing
Amigo's Board and senior management team have extensive experience in raising both equity and debt for mining transactions. The Company is drawing on this direct expertise and experience and intends to fund the Purchase Price and Development Funding by raising debt and/or equity directly in the Amigo SPV and from internal sources of funds. The Company is in numerous discussions, all at varying stages, with institutions that provide debt and/or equity funding for projects like the Kamiesberg Project.
Proposed Ownership Structure on Completion
Under the proposed structure on Completion, which is subject to Ownership Adjustments, Amigo intends to own 51% of Amigo SPV, that will own the Kamiesberg Project.
Rationale for and expected benefits of the Proposed Acquisition
The Proposed Acquisition will deliver a step change in the Amigo Group's JORC Resources: the Kamiesberg Project holds more than 2.71 billion tonnes of JORC Resource, including 0.48 billion tonnes of Measured Resource.
Once developed and commercial production is achieved, the Kamiesberg Project is expected to provide:
|
● |
An operational and production step change, with operations in multiple jurisdictions: gold in Tanzania, and heavy mineral sands in South Africa. |
|
● |
Diversification of commodity base: producing free cash flow from gold and heavy mineral sands. |
|
● |
Balance sheet resilience: enhancing the financial strength of Amigo through an increased operating base. |
|
● |
Increased shareholder returns: more diversified framework for providing increased and more sustainable shareholder returns. |
Effect of the Proposed Acquisition on the Enlarged Group - based on the 18 months to 30 September 2025
As detailed above, the Proposed Acquisition is the acquisition of the Kamiesberg Project, a shovel-ready portfolio of mineral sands mining tenements. Because the Kamiesberg Project is not an operational asset, there are limited operational and financial impacts of the Proposed Acquisition on the Enlarged Group based on the 18 months to 30 September 2025, including to the Enlarged Group earnings.
The largest financial impact of the Proposed Acquisition on the Enlarged Group is the increase in the net assets of the Enlarged Group through the recognition of Amigo's equity ownership of Amigo SPV, which is the case notwithstanding that the Purchase Price and Development Funding for the Proposed Acquisition is intended to be funded by raising debt and/or equity directly in the Amigo SPV and from internal sources of funds.
Risks to Amigo as a result of the Proposed Acquisition
A summary of the principal risks associated with the Proposed Acquisition is set out in Appendix II (Risk Factors Related to the Proposed Acquisition) to this announcement.
Board
The Proposed Acquisition is, in the opinion of the Board, in the best interests of the Shareholders as a whole.
Following Completion, it is expected that the composition of the Board will remain unchanged. The Proposed Acquisition will not result in any changes to the existing service contracts of the Directors, and no new service contracts are proposed to be entered into in connection with the Proposed Acquisition. The Company has not identified any key individuals, directors or management at Zirco SA, Cyndara or Zirco Roode important to the Kamiesberg Project.
The Company currently expects Completion to occur on or before 31 January 2027, subject to the satisfaction of the Completion Conditions.
Additional Information
The Proposed Acquisition constitutes a reverse takeover for the purposes of the UKLRs and is therefore notifiable in accordance with UKLR 7.5.1R(1).
As such, pursuant to UKLR 7.5.1R(2), the Prospectus in connection with the Proposed Acquisition will be published in due course. Shore Capital is acting as the Company's sponsor and Ashurst Perkins Coie LLP is acting as the Company's legal counsel in connection with the publication of the Prospectus.
This announcement contains inside information for the purposes of Article 7 of the Market Abuse Regulation (EU) No 596/2014 (as it forms part of UK domestic law by virtue of the European Union (Withdrawal) Act 2018, as amended by virtue of the Market Abuse (Amendment) (EU Exit) Regulations 2019). Upon publication of this announcement, this inside information will be considered to be in the public domain. The persons responsible for the release of this announcement are Craig Ransley (Executive Chair) and Nathan Boom (Chief Executive Officer).
Notes to editors
Amigo is a public limited company registered in England and Wales with registered number 10024479. Amigo is focussed on gold, platinum group metals, and rare earth mining opportunities in Africa. The Ordinary Shares are listed on the Official List and traded on the Main Market.
Please visit our website https://www.amigoplc.com/ for more information on Amigo's operations.
Forward-looking statements: This announcement may contain certain forward-looking statements with respect to Amigo's expectations and plans, strategy, management's objectives, future performance, production, reserves, costs, revenues and other trend information. These statements and forecasts involve risk and uncertainty because they relate to events and depend upon circumstances that may occur in the future. There are a number of factors which could cause actual results or developments to differ materially from those expressed or implied by these forward-looking statements and forecasts. The statements have been made with reference to forecast price changes, economic conditions and the current regulatory environment. Nothing in this announcement should be construed as a profit forecast or estimate and no statement in this announcement should be interpreted to mean that earnings, earnings per share or income, cash flow from operations or free cash flow for Amigo or the Enlarged Group, as appropriate, for the current or future years would necessarily match or exceed the amount set out in any forward-looking statement or historical published earnings, earnings per share or income, cash flow from operations or free cash flow for Amigo or the Enlarged Group, as appropriate. Past share performance cannot be relied upon as a guide to future performance.
Important Notices: Shore Capital and Corporate Limited ("Shore Capital"), which is authorised and regulated in the United Kingdom by the FCA, is acting exclusively for the Company as Sponsor and no one else in connection with the Proposed Acquisition and it will not regard any other person as a client in relation to the Proposed Acquisition and neither Shore Capital nor any of its affiliates (nor any of their partners, directors, officers, employees, advisers or agents) will be responsible to anyone other than the Company for providing the protections afforded to its clients or for providing advice in relation to the Proposed Acquisition or any other transaction, matter, or arrangement referred to in this announcement.
This announcement has been issued by, and is the sole responsibility of, the Company. No representation or warranty, express or implied, is or will be made as to, or in relation to, and no responsibility or liability whatever (whether direct or indirect, whether in contract, in tort, under statute or otherwise) is or will be accepted by Shore Capital or any other advisers to the Company or by any of their respective affiliates, partners, directors, officers, employees, advisers or agents as to or in relation to, the accuracy or completeness of this announcement or any other written or oral information made available to or publicly available to any interested party or its advisers, and any liability therefore is expressly disclaimed.
The statements contained in this announcement are made as at the date of this announcement, unless some other time is specified in relation to them, and publication of this announcement shall not give rise to any implication that there has been no change in the facts set forth in this announcement since such date.
The contents of this announcement are for information purposes only and are not to be construed as legal, business or tax advice. Each shareholder should consult its own legal adviser, financial adviser or tax adviser for legal, financial or tax advice, respectively.
Neither the content of the Company's website nor any website accessible by hyperlinks on the Company's website is incorporated in, or forms part of, this announcement.
APPENDIX II
RISK FACTORS RELATED TO THE PROPOSED ACQUISITION
The risks disclosed below are limited to those which Amigo considers are risks to Amigo as a result of the Proposed Acquisition.
The information given is as of the date of this announcement and, except as required by any applicable law, rules or regulations, will not be updated. The risks described below are not set out in any order of priority, assumed or otherwise.
The Proposed Acquisition presents a number of strategic, operational and financial risks that could affect the timing, scope and ultimate value delivered to the Enlarged Group.
1. Conditionality
The SPA is subject to a number of conditions, including Shareholder approval and regulatory consents (including the consent of the Minister of Mineral and Petroleum Resources under section 11 of the MPRDA to the change of control of Zirco Roode - the holder of the Kamiesberg Project). There can be no certainty that these conditions will be satisfied (or waived, if applicable) by the Long Stop Date, particularly as some are outside of the parties' control.
If any condition is refused or not satisfied, the Proposed Acquisition may not complete, and the SPA may lapse or be terminated in accordance with its terms. Any delay in satisfying these conditions may also result in the Long Stop Date being extended, or in Amigo incurring additional costs, and there is no guarantee that any such extension would be agreed by the parties.
2. Realisation of Value
The Proposed Acquisition is expected to deliver a step change in the Amigo Group's mineral resource base and cash flow potential, as well as providing significant organic opportunities for future growth. However, the Enlarged Group may not fully realise these benefits due to:
|
● |
lower-than-expected production or processing efficiency, or underperformance of the Kamiesberg assets relative to current forecasts; |
|
● |
higher-than-expected operating costs or capital expenditure required to develop or maintain the Kamiesberg assets; |
|
● |
infrastructure failures or unplanned shutdowns requiring remediation; |
|
● |
adverse shifts in macro‑economic conditions, trade policy, sovereign risk, market behaviour, product demand, or commodity pricing; and |
|
● |
foreign exchange volatility affecting project costs and revenues. |
Any of these factors could adversely affect the anticipated benefits of the Proposed Acquisition and the financial performance of the Enlarged Group.
3. Regulatory and Environmental Risk
The Kamiesberg Project is subject to extensive regulatory oversight in South Africa, including under the MPRDA, the National Environmental Management Act, 1998 (the "NEMA") and associated environmental and water legislation. The maintenance and renewal of mining rights, environmental authorisations, water use licences and other permits are critical to the development and operation of the Kamiesberg Project.
Key regulatory and environmental risks include:
|
● |
the risk that existing environmental authorisations may be subject to further legal challenge by third parties, including community groups or environmental organisations; |
|
● |
changes in South African mining, environmental or water legislation or policy that may impose additional compliance costs, restrict operational activities or delay project development; |
|
● |
conditions imposed by regulators that increase capital or operating costs; and |
|
● |
delays in obtaining or renewing critical permits. |
An adverse outcome in relation to any material regulatory or environmental matter could prevent or delay the development of the Kamiesberg Project and have a material adverse effect on the Enlarged Group.
4. Integration Risk
The Proposed Acquisition represents a significant expansion in Amigo's operations. Integrating operations, technology, systems, management, personnel, controls and pre-or post-Completion costs for the Proposed Acquisition may prove more difficult or expensive than anticipated.
Key integration risks include:
|
● |
challenges integrating systems, processes and operational practices; |
|
● |
differences in operating methodologies and potential disruption to existing operations; |
|
● |
difficulties maintaining internal controls and financial oversight; and |
|
● |
dependence on the successful transfer and retention of personnel. |
The Enlarged Group's performance will depend on the effective execution of operatorship transition and integration planning. Failure to do so could erode value and operational efficiency.
5. Due Diligence and Asset Quality Risk
As with all mining acquisitions, due diligence is inherently limited and may not identify all risks. Even an in-depth review may not reveal existing or potential problems, nor will it always permit a buyer to become sufficiently familiar with the assets to assess their deficiencies and capabilities fully.
Potential issues include:
|
● |
environmental or structural liabilities; |
|
● |
title defects or licensing constraints; |
|
● |
lower-than-expected mineral resource grades or tonnages; |
|
● |
failure of the resource to convert into an economically mineable mineral reserve; and |
|
● |
reliance on seller‑provided information and limited recourse under "as‑is" acquisition terms. |
6. Development Risk
The Proposed Acquisition relates to a mining asset which is not currently in commercial production. There can be no assurance that the asset will reach commercial production on the anticipated timeline, within budget, or at all. Developing a pre-production mining project is subject to a number of risks including:
(i) Geological and Resource Risk
Mineral resource estimates for the Kamiesberg Project are subject to inherent geological uncertainty. As the project has not yet been mined, there can be no assurance that resource tonnages, grades, mineral assemblage or geotechnical conditions will reconcile to forecast. Any adverse geological outcome may materially impact project economics and development viability.
(ii) Metallurgical and Processing Risk
The processing flowsheet for the Kamiesberg Project has not yet been proven at commercial scale. Variability in ore characteristics may affect recoveries, product quality and plant performance. Failure of pilot‑scale results to translate to full‑scale operations may require flowsheet redesign or additional capital expenditure.
(iii) Infrastructure and Logistics Risk
The Kamiesberg Project requires reliable access to power, water, transport corridors, port capacity and product handling infrastructure. Delays, capacity constraints or reliance on third‑party providers may increase costs or delay development.
(iv) Community and Social Licence Risk
The Kamiesberg Project's ability to proceed depends on maintaining constructive relationships with local communities, landholders and regional stakeholders. Community opposition, delays in land access agreements or social licence challenges may restrict or delay development.
(v) Permitting and Approvals Risk
Beyond the section 11 MPRDA approval, the Kamiesberg Project requires multiple additional permits, including environmental authorisations, water use licences and land access rights. Delays, conditions imposed by regulators or legal challenges may impact development timelines.
(vi) Construction and Execution Risk
Developing a new mining operation involves complex engineering, procurement and construction activities. Contractor performance issues, supply chain disruptions, cost inflation, weather impacts or schedule slippage may materially impact project economics.
(vii) Ramp‑Up and Operational Readiness Risk
Even if construction is completed, ramp‑up to steady‑state production may take longer than forecast due to equipment reliability issues, workforce competency gaps or lower initial recoveries.
(viii) Offtake and Market Access Risk
Mineral sands products are subject to specialised market dynamics. Inability to secure binding offtake agreements, product quality issues or buyer concentration may affect revenue certainty and financing viability.
(ix) ESG and Climate‑Related Risk
Evolving ESG expectations may impose additional obligations on the Enlarged Group. Climate‑related physical risks (extreme weather, drought, flooding) may impact operations or infrastructure. Transition risks may increase compliance costs or restrict operational flexibility.
(x) Labour and Contractor Availability Risk
Access to skilled labour, contractors and technical specialists may be constrained. Labour shortages, industrial action or increased labour costs may delay development or increase operating costs.
(xi) Modular Scale-Up and Phased Expansion Risk
While the modular development strategy is designed to establish a scalable pathway to 16 Mtpa via up to five standardised units, each processing module remains subject to technical performance, detailed engineering, and independent commercial feasibility decisions. No formal decision has yet been made to proceed beyond the initial module. Capital expenditure, schedule, and processing capacity assumptions have not yet been demonstrated at commercial operating scale, and there is no guarantee that Module 1 will generate sufficient operating cash flows to fund subsequent phases organically, which could delay or curtail ultimate expansion.
7. Political and Sovereign Risk
The Kamiesberg Project is exposed to sovereign and political risk in South Africa, including changes in mining policy, taxation, royalty regimes, regulatory enforcement and currency volatility. Sovereign risk may affect project economics and financing conditions.
8. Funding Risk (Acquisition and Development Funding)
The Proposed Acquisition and subsequent development of the Kamiesberg Project require internal and external funding. There can be no assurance that the Company, Amigo SPV and/or the Enlarged Group will be able to allocate sufficient internal funds or secure the necessary equity and debt financing on acceptable terms, in the required amounts, or within the timeframes needed to complete the Proposed Acquisition and develop the Kamiesberg Project. Funding the Purchase Price and Development Funding through internal sources of funds and debt and equity capital at the Amigo SPV level is vulnerable to liquidity constraints, market volatility, and investor appetite. The planned phased expansion to an aggregate capacity of approximately 16 Mtpa relies upon the successful commissioning and operational profitability of the initial US$15 million module to generate organic reinvestment capital. Any failure, delay, or underperformance of Module 1, or insufficient operational cash flow, would require the Company or Amigo SPV to seek additional third-party debt or equity financing. Such financing may not be available on commercially acceptable terms, or at all, which could result in project downsizing, schedule delays, or equity dilution.
APPENDIX III
ADDITIONAL INFORMATION ON KAMIESBERG PROJECT
PART ONE: KAMIESBERG PROJECT
(A) Location
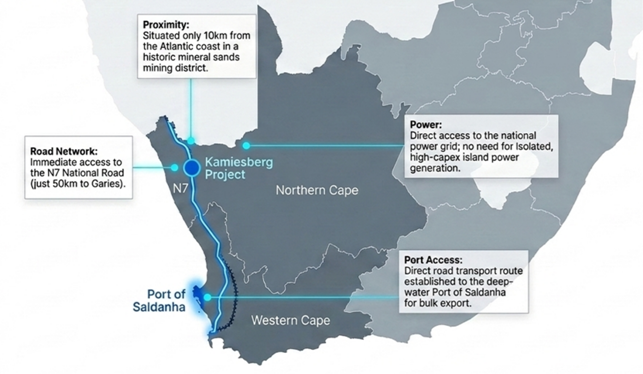
The Kamiesberg Project is located on the West Coast of South Africa in the Namaqualand Administrative District of the Northern Cape Province, approximately 500 kilometres north of Cape Town.
(B) Operating Methodology - Simple, Low-Tech Extraction from Surface
The deposit extends over an area of approximately 20 km by 14 km and is located near surface, requiring no complex ground engineering. Mineralisation is accessible from surface, without the need to pre strip the orebody, to a depth of approximately 25 metres in the initial mining areas, enabling extraction without the requirement for underground mining operations.
The proposed mining method involves conventional open-pit mining using standard earthmoving equipment, including excavators and front-end loaders. Ore would be extracted directly from the pit floor and transported to stockpiles for processing.
According to the current mine plan, the initial phases of extraction are expected to focus on areas containing higher-grade mineralisation. The Company estimates an average grade of approximately 3.91% total heavy minerals ("THM") are scheduled to be mined during the currently envisaged mine life, which subject to relevant mining approvals and consents is forecasted to exceed 30 years.
(C) Two Distinct Markets Targeted from One Ore Body 1
Once fully ramped up, the project is expected to produce approximately 542 Ktpa of heavy mineral concentrate ("HMC") based on the current mine plan and processing assumptions.
Following concentration, the HMC stream is expected to be separated into two principal product streams:
Bulk Commodities Product Stream
Approximately 93% of the HMC is expected to comprise sulphate ilmenite. Based on current estimates, this stream is expected to produce approximately 505 Ktpa of sulphate ilmenite together with approximately 32 Ktpa of non-magnetic mineral products, including rutile and zircon. Sulphate ilmenite is a feedstock used in the production of titanium dioxide pigment.
High Value Rare Earth Minerals Product Stream
A smaller proportion of the HMC is expected to comprise monazite concentrate. Based on current estimates, production of approximately 6 Ktpa of monazite concentrate (at a concentrate grade of approximately 60%) is anticipated. Monazite contains rare earth elements, including neodymium oxide (Nd₂O₃), praseodymium oxide (Pr2O3) and dysprosium oxide (Dy₂O₃), which are used in the manufacture of permanent magnets.
|
|
1 The expected product mix and production volumes are based on the current resource model, mine plan and processing flowsheet and may be subject to change following further technical studies, permitting, financing and operational optimisation. |
(D) Monazite - the strategic value of the Kamiesberg Project 2
While Light Rare Earth Elements ("REEs") provide the bulk volume, Kamiesberg's true strategic leverage lies in its ~14% concentration of highly sought-after Magnet REEs. This positions the project directly upstream of the most critical supply chain bottlenecks in the green and strategic defence economies.
Based on the current mineralogical analysis, the project's monazite concentrate is expected to comprise approximately 13.8% magnet rare earth oxides, 34.6% light rare earth oxides and 8.9% radioactive constituents, with the balance comprising other mineral matrix material.
|
● |
The estimated magnet rare earth oxide content includes approximately 10.4% neodymium oxide (Nd₂O₃), 2.7% praseodymium oxide (Pr2O3) and 0.7% dysprosium oxide (Dy₂O₃). Essential for high-temperature permanent magnets and NdFeB alloys. |
|
● |
The estimated light rare earth oxide content includes approximately 24.0% cerium oxide (CeO₂) and 10.6% lanthanum oxide (La₂O₃). The industrial backbone elements utilised widely for catalysts, alloys, optics, and standard batteries. |
|
● |
The radioactive component is estimated to comprise approximately 8.4% thorium oxide (ThO₂) and 0.5% uranium oxide (UO₂). Handling, storage, transport and processing of materials containing these constituents would be subject to applicable regulatory requirements and operating procedures. |
|
|
2 The composition estimates set out above are based on current metallurgical and mineralogical testwork and may be subject to revision following further study and optimisation work. |
(E) Advanced Permitting
The Board believes that the Kamiesberg Project's permitting status differentiates it from many mineral sands development projects, having secured key regulatory approvals required for development, including a mining right, water use licence and environmental authorisation.
Mining right
|
● |
Integrated mining rights secured covering the full Roode Heuvel and Leeuvlei properties. |
|
● |
Prospecting rights and/or mining right applications for the Sabies and Langkuil properties. |
Water use licence
|
● |
Granted for Roode Heuvel and Leeuvlei properties. |
Environmental authorisation
|
● |
Approved for Roode Heuvel and Leeuvlei properties. |
(F) Tenements and JORC Resource
The Kamiesberg Project is composed of:
|
● |
A mining right totalling 12,319 hectares, covering Roode Heuvel and Leeuvlei; and |
|
● |
Prospecting rights and/or mining right applications totalling 14,390 hectares, covering Sabies and Langkuil. |
The total hectarage is 26,709 hectares. All rights are issued for heavy minerals.
To date, three sub-facies within the sand assemblage have been identified:
|
● |
Red Aeolian Sand; |
|
● |
Feldspathic Aeolian Sand; and |
|
● |
Basal grits and conglomerates. |
Colours range from yellow red to red-brown depending on the oxidation of the iron coatings to grains. The basal grits and conglomerates tend to be predominantly a deep red. In total 921 drill holes totalling 10,673 metres were completed in 2011, of which 655 holes were on Roode Heuvel and 266 on Leeuvlei. In December 2012, an additional 166 holes totalling 2,170 metres of infill drilling were completed on Roode Heuvel. Tronox drilled 309 aircore holes on Langkuil in 2015. In 2017, 115 holes were completed on Sabies and 118 holes were completed in 2019 on Langkuil.
All primary analyses were undertaken at Scientific Services cc, a DEKRA certified laboratory in Cape Town. All drill holes that intersected mineralisation were analysed. In total 264 drill holes were analysed on Leeuvlei, 815 on Roode Heuvel, 115 on Sabies and 417 on Langkuil.
Quality assurance and quality control procedures were in place and have been reported on. Univariate statistical analysis was carried out on the 1 metre composited drill hole data in their respective domains.
A block model with block sizes of 100 metres x 100 metres x 4 metres and minimum sub blocking of 25 metres x 25 metres x 1 metre were created within Surpac for the whole project area.
The wireframes of the Red Aeolian Sand, the 3% THM and 1% THM grade shells on the project area, were assigned to the block model as material "ore", each with their respective ore type name.
A relative density of 1.75 was assigned to the Red Aeolian Sand ore type and a relative density of 1.92 to the Feldspathic Aeolian Sand (3% and 1%) ore types in the project area.
Block model validations were done by visual checking, grade conformance and swath plot checking.
The mineral resource estimations reported from the block model without a cut-off, are shown below in "Part Two: JORC Resources".
(G) Mineral Processing Approach - Beneficiation Process
Ore mined from the Kamiesberg Project will initially be subjected to physical separation techniques, including gravity and magnetic processing, with the objective of removing a significant proportion of lower-value material prior to chemical treatment.
Following this stage, a concentrated mineral stream, representing approximately 0.6% to 1.0% of the mined material, will be processed using flotation methods. By restricting chemical treatment to this concentrated stream rather than the entire mined ore, the Company expects to reduce reagent consumption and associated processing costs.
(H) Modular Development Strategy 3
The Company intends to develop the Kamiesberg Project through a phased, modular processing configuration, establishing a scalable pathway to an aggregate processing capacity of approximately 16 million tonnes per annum via the progressive deployment of up to five standardised units (each delivering approximately 3.3 million tonnes per annum).
The first processing module requires an estimated capital expenditure of approximately US$15 million and is targeted for commissioning within approximately six months of Completion.
This modular approach is intended to facilitate near-immediate production and early operating cash flow generation.
Subject to the initial module achieving target operational and financial benchmarks, operating cash flows are intended to be progressively reinvested to fund subsequent module expansions, significantly reducing upfront capital requirements and avoiding excessive corporate debt or asset-level dilution.
While the Company intends to reinvest cash flows from operational modules into additional capacity, no formal decision has been taken to proceed with any subsequent module. Each phase remains subject to technical performance, detailed engineering, financing availability, regulatory approvals, and separate commercial development decisions. Capital expenditure, timetable, and capacity estimates are based on current conceptual development assumptions that have not yet been demonstrated at commercial operating scale, and actual outcomes may differ materially.
|
|
3 The Company currently intends that, if the first module performs in accordance with expectations, a proportion of the resulting operating cash flow could be reinvested in additional processing capacity. However, no decision has been taken to proceed with any subsequent module, and each phase would remain subject to further technical assessment, detailed engineering, financing, applicable approvals and a separate development decision. The capital cost, timetable, and processing capacity and gross operating profit estimates are based on the assumptions underlying the current development concept. These assumptions have not yet been demonstrated through construction and operation of the proposed modules. Actual capital expenditure, commissioning timescales, production levels, operating costs, commodity prices and financial results may differ materially from the estimates presented. |
PART TWO: JORC RESOURCES
The following table sets forth certain information with respect to the Proposed Acquisition resources as of March 2020, with confirmation provided to Amigo on 24 July 2026 from the Competent Person that the March 2020 JORC Resource remains valid, current, and materially accurate as at 24 July 2026. The mineral resource estimations reported by resource category are shown below.
|
Resource Category |
Volume (Mm³) |
Tonnes (M) |
THM % |
Silt % |
Ovz % |
Ilm % |
Leu % |
Mon % |
Rut % |
Zir % |
RD |
|
Measured |
256.63 |
482.29 |
3.91 |
14.98 |
2.13 |
3.14 |
0.08 |
0.04 |
0.06 |
0.15 |
1.88 |
|
Indicated |
894.49 |
1,692.13 |
3.25 |
19.37 |
3.23 |
2.59 |
0.10 |
0.03 |
0.05 |
0.13 |
1.89 |
|
Inferred |
286.80 |
540.30 |
2.91 |
17.01 |
4.22 |
2.39 |
0.07 |
0.03 |
0.04 |
0.11 |
1.89 |
|
Grand Total |
1,437.92 |
2,714.72 |
3.30 |
18.12 |
3.23 |
2.65 |
0.09 |
0.03 |
0.05 |
0.13 |
1.89 |
Proposed Acquisition: Total Resources as of 24 July 2026
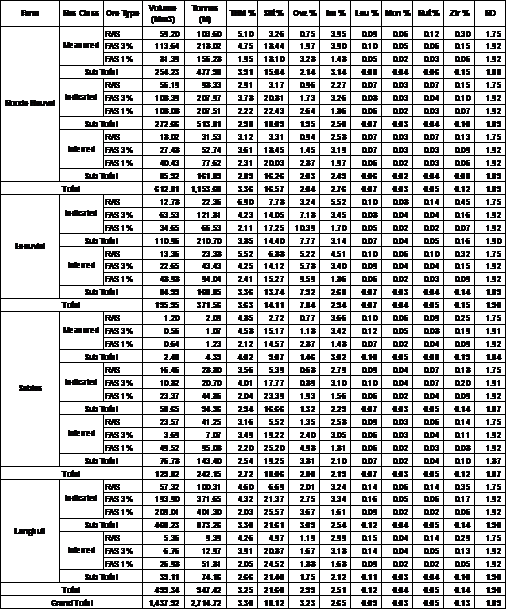
The average mineral assemblage percentages of the valuable heavy minerals are shown in the table below per farm and domain.
|
|
|
Mineral Assemblage % of VHM of the THM |
||||||
|
Farm |
Ore Type |
THM % |
Ilm % |
Leu % |
Mon % |
Rut % |
Zir % |
Other % |
|
Roode Heuvel |
RAS |
3.91 |
78.26 |
2.05 |
1.02 |
2.56 |
5.37 |
10.74 |
|
FAS 3% |
4.20 |
84.52 |
2.14 |
0.95 |
1.19 |
2.86 |
8.34 |
|
|
FAS 1% |
2.14 |
81.31 |
2.34 |
0.93 |
1.40 |
2.80 |
11.22 |
|
|
Sub Total |
3.36 |
82.14 |
2.08 |
0.89 |
1.49 |
3.57 |
9.83 |
|
|
Leeuvlei |
RAS |
6.19 |
80.78 |
1.62 |
1.13 |
1.94 |
6.14 |
8.39 |
|
FAS 3% |
4.24 |
81.13 |
1.89 |
0.94 |
0.94 |
3.77 |
11.33 |
|
|
FAS 1% |
2.28 |
78.51 |
2.19 |
0.88 |
0.88 |
3.51 |
14.03 |
|
|
Sub Total |
3.63 |
80.99 |
1.93 |
1.10 |
1.10 |
4.13 |
10.75 |
|
|
Sabies |
RAS |
3.37 |
79.82 |
2.67 |
0.89 |
2.08 |
4.75 |
9.79 |
|
FAS 3% |
3.90 |
79.49 |
2.31 |
1.03 |
1.54 |
4.62 |
11.01 |
|
|
FAS 1% |
2.15 |
80.47 |
2.79 |
0.93 |
1.40 |
3.72 |
10.69 |
|
|
Sub Total |
2.72 |
80.51 |
2.57 |
1.10 |
1.84 |
4.41 |
9.57 |
|
|
Langkuil |
RAS |
4.57 |
70.46 |
3.06 |
1.31 |
3.06 |
7.44 |
14.67 |
|
FAS 3% |
4.30 |
77.67 |
3.72 |
1.16 |
1.40 |
3.95 |
12.10 |
|
|
FAS 1% |
2.03 |
79.80 |
4.43 |
0.99 |
0.99 |
2.96 |
10.83 |
|
|
Sub Total |
3.25 |
77.23 |
3.69 |
1.23 |
1.54 |
4.31 |
12.00 |
|
|
Grand Total |
3.30 |
80.30 |
2.73 |
0.91 |
1.52 |
3.94 |
10.60 |
|
The above technical information has been extracted from the GeoActiv Competent Person's Report on the Kamiesberg Project, which will be included in the Prospectus (subject to any necessary updates and amendments in accordance with the JORC Code and other applicable reporting standards, as determined by the Competent Person).
PART THREE: FINANCIAL STATEMENTS
(A) Summary Financial Information on Zirco SA (including Zirco Roode)
Consolidated Statement of Financial Position
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Audited |
Audited |
Unaudited |
|
Property, plant and equipment |
638,716 |
505,923 |
362,295 |
|
Intangible assets |
256,093,412 |
318,807,461 |
324,238,401 |
|
Loans to group companies |
66,584,287 |
- |
- |
|
Non-current assets |
323,316,415 |
319,313,384 |
324,600,696 |
|
Trade and other receivables |
6,189,377 |
646,575 |
374,379 |
|
Cash and cash equivalents |
8,597,706 |
2,948,249 |
853,644 |
|
Current assets |
14,787,083 |
3,594,824 |
1,228,023 |
|
Total assets |
338,103,498 |
322,908,208 |
325,828,719 |
|
Trade and other payables |
23,308,894 |
11,480,083 |
9,083,525 |
|
Current liabilities |
23,308,894 |
11,480,083 |
9,083,525 |
|
Loans from shareholder |
309,669,121 |
380,675,816 |
390,231,147 |
|
Loans from group companies |
66,584,287 |
- |
- |
|
Non-current liabilities |
376,253,408 |
380,675,816 |
390,231,147 |
|
Total liabilities |
399,562,302 |
392,155,899 |
399,314,672 |
|
Share capital |
100 |
100 |
100 |
|
Accumulated loss |
(58,822,444) |
(66,257,475) |
(70,730,726) |
|
Non-controlling interest |
(2,636,460) |
(2,990,316) |
(2,755,327) |
|
Equity |
(61,458,804) |
(69,247,691) |
(73,485,953) |
|
Total equity and liabilities |
338,103,498 |
322,908,208 |
325,828,719 |
Consolidated Statement of Comprehensive Income
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Audited |
Audited |
Unaudited |
|
Other operating income |
3,817 |
4,577 |
5,232 |
|
Other operating expenses |
(6,141,061) |
(7,798,131) |
(4,245,696) |
|
Operating loss |
(6,137,244) |
(7,793,554) |
(4,240,464) |
|
Investment income |
3,429 |
4,666 |
2,202 |
|
Loss for the year |
(6,133,815) |
(7,788,888) |
(4,238,262) |
|
Other comprehensive income |
- |
- |
- |
|
Total comprehensive loss for the year |
(6,133,815) |
(7,788,888) |
(4,238,262) |
Consolidated Statement of Cash Flows
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Audited |
Audited |
Unaudited |
|
Cash (used in) / generated from operations |
148,380 |
(13,920,770) |
(6,221,198) |
|
Interest income |
3,429 |
4,666 |
2,202 |
|
Net cash from operating activities |
151,809 |
(13,916,104) |
(6,218,996) |
|
Purchase of property, plant and equipment |
(715,580) |
(25,999) |
- |
|
Purchases of intangible assets |
(58,692,235) |
(62,714,049) |
(5,430,940) |
|
Net cash from investing activities |
(59,407,815) |
(62,740,048) |
(5,430,940) |
|
Repayments of loans from group companies |
- |
- |
- |
|
Increase/(decrease) in shareholders loans |
67,375,220 |
71,006,695 |
9,555,331 |
|
Net cash from financing activities |
67,375,220 |
71,006,695 |
9,555,331 |
|
Total cash movement for the year |
8,119,214 |
(5,649,457) |
(2,094,605) |
|
Cash and cash equivalents at the beginning of the year |
478,492 |
8,597,706 |
2,948,249 |
|
Cash and cash equivalents at the end of the year |
8,597,706 |
2,948,249 |
853,644 |
(B) Summary Financial Information on Cyndara
Statement of Financial Position
|
|
FY23 |
FY24 |
FY25 |
|
|
RAND |
RAND |
RAND |
|
|
Unaudited |
Unaudited |
Unaudited |
|
Investment |
26 |
47,890,946 |
47,890,946 |
|
Loans to group companies |
66,584,287 |
86,078,015 |
87,717,615 |
|
Non-current assets |
66,584,313 |
133,968,961 |
135,608,561 |
|
Cash and cash equivalents |
74 |
74 |
74 |
|
Current assets |
74 |
74 |
74 |
|
Total assets |
66,584,387 |
133,969,035 |
135,608,635 |
|
Loans from group companies |
66,584,287 |
133,968,935 |
135,608,535 |
|
Non-current liabilities |
66,584,287 |
133,968,935 |
135,608,535 |
|
Total liabilities |
66,584,287 |
133,968,935 |
135,608,535 |
|
Share capital |
100 |
100 |
100 |
|
Equity |
100 |
100 |
100 |
|
Total equity and liabilities |
66,584,387 |
133,969,035 |
135,608,635 |
APPENDIX IV
DEFINITIONS
The following definitions apply in this announcement unless the context otherwise requires:
|
Key Word |
Definition |
|
Amigo Group |
the Company and its subsidiaries and subsidiary undertakings from time to time |
|
Amigo Shareholders or Shareholders |
the holders of Ordinary Shares in the capital of the Company |
|
Amigo SPV |
Rare Earths Development Pte Ltd |
|
B-BBEE Obligations |
means broad-based black economic empowerment as contemplated in the Broad-Based Black Economic Empowerment Act 53 of 2003, as amended |
|
Board |
the board of directors of the Company |
|
Company or Amigo |
Amigo Resources PLC |
|
Competent Person or GeoActiv |
GeoActiv (Pty) Ltd |
|
Completion |
completion of the Proposed Acquisition |
|
Completion Conditions |
the successful publication of the Prospectus in relation to the Proposed Acquisition, the approval (without amendment) of the Resolution by Shareholders at the General Meeting and the approval of the FCA and the LSE of Readmission, amongst other things |
|
Cyndara |
Cyndara 14 (Pty) Ltd, the 30% shareholder of Zirco Roode |
|
Development Funding |
funding required for project implementation, including but not limited to the estimated capital expenditure of approximately US$15 million for the initial processing module (ROM capacity of approximately 3.3Mtpa), early production and site establishment works, infrastructure establishment, working capital, and associated pre-commissioning activities preceding subsequent modular expansion phases |
|
Directors |
the directors of the Company from time to time |
|
Enlarged Group |
the Amigo Group as enlarged by the Proposed Acquisition |
|
FCA |
the UK Financial Conduct Authority |
|
General Meeting |
the general meeting of the Company to be held at the time and date set out in the Prospectus |
|
GeoActiv Competent Person's Report on the Kamiesberg Project |
the competent person's report relating to the Kamiesberg Project produced by GeoActiv |
|
HMC |
heavy mineral concentrate |
|
HMS |
heavy mineral sand |
|
Ilm |
ilmenite |
|
Indicated Resource |
Indicated Mineral Resource as such term is defined in Clause 22 of the JORC Code |
|
Inferred Resource |
Inferred Mineral Resource as such term is defined in Clause 21 of the JORC Code |
|
JORC |
the Australasian Joint Ore Reserves Committee |
|
JORC Code |
the 2012 Edition of the Australasian code for reporting of exploration results, mineral resources and ore reserves |
|
JORC Resource |
the aggregate of Inferred Resource, Indicated Resource and Measured Resource |
|
Kamiesberg Project |
the Kamiesberg heavy mineral sands project, located on the West Coast of South Africa in the Namaqualand Administrative District of the Northern Cape Province |
|
Ktpa |
thousand tonnes per annum |
|
Leu |
leucoxene |
|
London Stock Exchange |
London Stock Exchange plc |
|
Long Stop Date |
31 March 2027, as amended by agreement between the parties to the SPA |
|
Main Market |
the London Stock Exchange's main market for listed securities |
|
Measured Resource |
Measured Mineral Resource as such term is defined in Clause 23 of the JORC Code |
|
Mon |
monazite |
|
MPRDA |
the South African Mineral and Petroleum Resources Development Act, No. 28 of 2002, as amended |
|
Mtpa |
million tonnes per annum |
|
NEMA |
the National Environmental Management Act, 1998 (South Africa) |
|
Official List |
the Official List maintained by the FCA |
|
Ordinary Shares |
the ordinary shares of 0.25p each in the capital of the Company |
|
Ovz |
oversize |
|
Ownership Adjustments |
potential adjustments to be made to the level of Amigo ownership in Amigo SPV to reflect B-BBEE Obligations and the impact of the intended equity raising by Amigo SPV |
|
Proposed Acquisition |
the proposed acquisition by Amigo SPV of Zirco SA and Cyndara, which together hold 100% of the issued share capital of Zirco Roode |
|
Prospectus |
a combined prospectus and a shareholder circular to be published in due course in connection with the Proposed Acquisition and Re-admission |
|
Purchase Price |
USD 33 million on a working capital adjusted, cash-free and debt-free basis |
|
RD |
relative density |
|
Re-admission |
the re-admission of the Ordinary Shares to the Equity Shares (Commercial Companies) category of the Official List and to trading on the Main Market |
|
REE |
rare earth element |
|
Resolution |
the resolution to be set out in the notice of General Meeting in the Prospectus |
|
ROM |
run-of-mine |
|
Rut |
rutile |
|
Sellers |
Zirco Resources Proprietary Limited, Millrex Investments Limited and Lelau Mohuba Trust |
|
Shareholders |
the holders of Ordinary Shares |
|
SPA |
the share purchase agreement entered into between Zirco Resources Proprietary Limited, Lelau Mohuba Trust, Amigo SPV, Cyndara, Zirco Roode and Zirco SA |
|
Sponsor or Shore Capital |
Shore Capital and Corporate Limited, sponsor to the Company |
|
THM |
total heavy mineral |
|
UKLRs |
the UK Listing Rules Sourcebook of the FCA made under Part VI of the Financial Services and Markets Act 2000 |
|
United Kingdom or UK |
the United Kingdom of Great Britain and Northern Ireland |
|
Zir |
zircon |
|
Zirco Roode |
Zirco Roode Heuwel (Pty) Ltd, the holder of the Kamiesberg Project |
|
Zirco SA |
Zirco Resources (SA) Holdings (Pty) Ltd, the 70% shareholder of Zirco Roode |
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.

Latest directors dealings
- 4 hours ago Admiral Group
- 5 hours ago Oryx International Growth Fund Ltd.
- 5 hours ago ASA International Group
- 5 hours ago Standard Life plc
- 5 hours ago Imperial Brands